Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
What Is a Deductible in Car Insurance? A Simple Guide
What Is a Deductible in Car Insurance? A Simple Guide
What Is a Deductible in Car Insurance? A Simple Guide
What Is a Deductible in Car Insurance? A Simple Guide
What Is a Deductible in Car Insurance? A Simple Guide

Quick Answer: - A deductible in car insurance is the amount you pay out of pocket on a covered claim before your insurance company pays the rest. For example, with a $500 deductible and $3,000 in damage, you pay $500, and your insurer pays $2,500. Deductibles usually apply to collision and comprehensive coverage, not to liability.
When you buy car insurance, you pick a deductible, usually $250, $500, $1,000, or more. It is one of the few numbers on your policy that you control directly, and it affects both your monthly premium and how much you pay when something goes wrong. Yet many drivers don't really know what a deductible in car insurance is until they file their first claim and get a bill they weren't expecting.
The deductible is your share of the repair cost. Your insurance company covers the rest, up to your policy limits. Choosing the right amount is a balance between paying less each month and being able to afford that share when you need it.
This guide explains how car insurance deductibles work with real examples, which coverages have one and which don't, how your deductible changes your premium, how Texas weather claims affect it, and how to choose the right amount for your budget.
How a Car Insurance Deductible Works
Your deductible applies each time you file a claim under a coverage that has one. It is not an annual amount like a health insurance deductible. If you file two separate collision claims in one year, you generally pay the deductible twice.
Here is how a typical claim plays out:
1. You have an accident or your car is damaged by a covered event, such as hail.
2. You file a claim with your insurance company.
3. An adjuster inspects the car and estimates the repair cost.
4. Your insurer subtracts your deductible from the approved amount.
5. The insurer pays the rest to you or directly to the repair shop, and you pay your deductible to the shop.
Example of a $500 Deductible
Jose in Katy backs into a pole, and the repair estimate is $2,400. He has a $500 collision deductible. Jose pays $500 to the body shop, and his insurer pays $1,900.
What If the Damage is Less Than the Deductible?
your insurer pays nothing. A $400 scratch with a $500 deductible is fully your cost, so it usually doesn't make sense to file a claim.
How does a deductible apply to a total loss?
the insurer pays the car's actual cash value minus your deductible. If your car is worth $12,000 and your deductible is $1,000, you would receive $11,000, minus any loan payoff owed to your lender.
What Is a Deductible for Car Insurance Coverages? Which Have One and Which Don't
Not every part of your car insurance policy is deductible. Understanding what a deductible for car insurance applies to helps you know what to expect on different types of claims.
Coverage | Has a Deductible? | What It Covers |
Liability (bodily injury & property damage) | No | Damage and injuries you cause to others |
Collision | Yes | Damage to your car from hitting another car or object |
Comprehensive | Yes | Theft, hail, flood, fire, vandalism, hitting an animal |
Uninsured motorist property damage (TX) | Yes, typically $250 | Damage to your car caused by an uninsured driver |
Personal Injury Protection (PIP) | No | Medical bills and lost wages for you and your passengers |
Uninsured/underinsured motorist bodily injury | No | Your injuries caused by a driver without enough insurance |
Liability has no deductible because it pays other people, not you. If you cause an accident, your insurer pays the other driver's damages up to your limits, and you don't owe a deductible on that part of the claim.
Collision and comprehensive can have different deductibles. Many drivers choose a lower comprehensive deductible, such as $250 or $500, because hail and flood damage are common in Houston, and a higher collision deductible, such as $1,000, to keep premiums down.
How Your Deductible Affects Your Premium
Your deductible and your premium move in opposite directions. A higher deductible means a lower premium, because you are agreeing to take on more of the cost of smaller claims. A lower deductible means a higher premium, because the insurer is taking on more risk.
Deductible | Estimated 6-Month Collision + Comp Premium | Your Cost on a $3,000 Claim | Best For |
$250 | About $520 | $250 | Drivers who want minimal out-of-pocket costs |
$500 | About $450 | $500 | Most drivers; balanced option |
$1,000 | About $380 | $1,000 | Drivers with emergency savings |
$2,000 | About $320 | $2,000 | Drivers with strong savings and older cars |
*Prices may vary based on your specific provider, coverage selections, driving/claims history, and other individual factors. The figures above are estimates only and are not a guarantee of your actual rate. *
In this example, moving from a $500 to a $1,000 deductible saves about $140 a year but costs $500 more if you file a claim. If you go more than three and a half years without a collision or comprehensive claim, the higher deductible comes out ahead. That break-even math is a useful way to compare any two deductible options.
Do I Have to Pay a Deductible if I'm Not at Fault?
Many drivers wonder what a deductible on car insurance means when someone else caused the accident. Generally, you don't pay a deductible when the other driver is at fault and you file with their insurance company. Their liability coverage pays for your repairs.
You can also file with your own collision coverage if you want repairs to start faster or the other insurer is slow to accept fault. In that case, you pay your deductible up front. Your insurer then tries to recover the money from the at-fault driver's insurer through a process called subrogation. If they succeed, you typically get your deductible back, either in full or in part.
If the at-fault Driver is Uninsured
a real risk with about 1 in 5 Texas drivers uninsured, your uninsured motorist property damage coverage can pay for repairs, usually after a $250 deductible. If you don't carry this coverage, you would need to use your collision coverage and pay your collision deductible instead.
Deductibles for Hail, Flood, and Glass Claims in Texas
Houston drivers file a lot of weather-related claims, and most of them fall under comprehensive coverage, so your comprehensive deductible is the one that applies.
Hail
Hail damage is covered under comprehensive. Dent repairs from a major storm can easily run $2,000 to $6,000 or more, so a moderate comprehensive deductible is worth considering in the Houston area.
Flood
Unlike homeowners insurance, car insurance does cover flood damage, but only if you have comprehensive coverage. Flooded cars are often declared a total loss, and the payout is the car's value minus your deductible.
Windshield and Glass
Windshield chips and cracks usually fall under comprehensive. Texas does not require zero-deductible glass coverage, but many insurers offer optional full glass coverage for a small added cost. Ask about it if you drive on highways where rock chips are common.
Tip: If you only lower one deductible, lowering comprehensive often costs less than lowering collision, and it protects you against the weather claims Houston drivers file most often.
How to Choose the Right Car Insurance Deductible
There isn't one right deductible for everyone. Use these questions to find yours:
1. How much could you pay tomorrow without borrowing?
Your deductible should never be more than your available emergency savings.
2. How much does each option save you?
Ask your agent for quotes at $500 and $1,000 and calculate the yearly difference.
3. What is the break-even point?
Divide the extra out-of-pocket cost by the yearly savings to see how many claim-free years it takes to come ahead.
4. How often do you file claims?
If you have had several claims in recent years, a lower deductible may be worth the higher premium.
5. What is your car worth?
On an older car, a high deductible can eat up most of a potential payout.
6. Does your lender have a limit?
If your car is financed or leased, your lender will likely require collision and comprehensive, and many cap the deductible at $500 or $1,000.
Deductible vs. Premium vs. Coverage Limit: Key Terms Explained
Three numbers on your policy work together, and mixing them up is one of the most common sources of confusion:
Term | What It Means | Example |
Premium | What you pay the insurer to keep your policy active, monthly or every six months | $150 per month |
Deductible | What you pay toward your own covered claim before insurance pays | $500 per collision claim |
Coverage limit | The most your insurer will pay on a covered claim | $30,000 per person for bodily injury |
Out-of-pocket cost | Your total cost on a claim, including the deductible and anything above your limits | $500 deductible + any amount over your limit |
Think of it this way: your premium is the price of the policy, your deductible is your share of each claim on your own car, and your limit is the ceiling on what the insurer pays. Raising your deductible lowers your premium, while raising your limits raises your premium but gives you more protection.
Should You File a Claim or Pay Out of Pocket?
Just because damage is covered doesn't always mean you should file a claim. Filing a small claim can raise your premium at renewal, especially for an at-fault collision, and that increase can last for several years. Before you file, compare the repair estimate with your deductible and the possible rate increase.
Repair Estimate | Deductible | Insurance Would Pay | Usually Makes Sense To… |
$700 | $500 | $200 | Pay out of pocket |
$1,400 | $500 | $900 | Get advice; depends on fault and your record |
$4,500 | $500 | $4,000 | File a claim |
$6,000 (hail) | $500 | $5,500 | File a claim |
Not-at-fault and weather claims generally affect your rate less than at-fault accidents, but every carrier treats claims differently. Your agent can help you weigh the numbers before you file. If anyone was injured, always report the accident to your insurer, even if the vehicle damage is small.

Can You Change Your Car Insurance Deductible?
Yes. You can usually change your deductible at any time by contacting your agent or insurer, not just at renewal. The new deductible applies to claims that happen after the change takes effect, so you can't lower it after an accident to reduce what you owe on that claim.
It is smart to review your deductible when your finances change. If you have built up more emergency savings, raising your deductible can lower your premium. If money is tighter, lowering it can protect you from a large bill at a bad time. A good time to check is also right before hurricane and hail season, when comprehensive claims in the Houston area tend to rise.
Example: Linh in Pearland had a $1,000 deductible when she started a new job. After six months of building savings, she kept her $1,000 collision deductible but lowered her comprehensive deductible to $500 ahead of spring hail season. The small premium increase gave her more protection against the claims she was most likely to file.
Quick rule of thumb: If you have at least $1,000 set aside for emergencies and a clean claims history, a $1,000 collision deductible usually gives you the best value. If your savings are thin, you drive in heavy Houston traffic every day, or you've had a claim in the last few years, a $500 deductible is often the safer middle ground. Whatever you choose, write your deductible amounts down and keep them with your insurance card, so you know exactly what to expect if you ever need to file a claim.
What If You Can't Afford Your Deductible?
If your car is damaged and you don't have the deductible ready, you still have options:
Ask the body shop about a payment plan.
Many repair shops will let you pay for the deductible installments.
Check whether the other driver is at fault.
If so, filing with their liability insurance means you don't owe a deductible.
Ask your insurer about direct payment.
In many cases, the insurer pays the shop directly and you only pay your deductible when you pick up the car, giving you a little time to arrange it.
Review your deductible going forward.
If this situation surprised you, lowering your deductible at your next policy change can prevent it from happening again.
Financed or leased car? Your lender cares about your deductible too, because the car is their collateral. Most loan and lease contracts require collision and comprehensive with a maximum deductible, commonly $500 or $1,000. If you raise your deductible above your lender's limit, you could be in violation of your contract, so check your paperwork before making a change.
Common Myths About Car Insurance Deductibles
Myth: You pay your deductible once a year.
Car insurance deductibles apply per claim, not per year.
Myth: You pay a deductible if you hit someone else's car.
Damage you cause to other people is paid by your liability coverage, which has no deductible. You only pay a deductible if you use a collision to fix your own car.
Myth: The lowest deductible is always the smartest choice.
A $250 deductible can cost you more in premiums over a few years than you would ever save on claims.
Myth: Your insurer pays the deductible if you're not at fault.
You avoid it by claiming against the other driver's insurance, or you can get it back through subrogation, but your own insurer does not waive it automatically.
Myth: Car insurance doesn't cover floods.
Comprehensive coverage does cover flood damage to your car.
Frequently Asked Questions
What is a deductible in car insurance in simple terms?
A deductible is the part of a covered claim you pay yourself before your insurance pays the rest. If you have a $500 deductible and $2,000 in damage, you pay $500 and your insurer pays $1,500.
What is a deductible for car insurance, and do I pay it every time?
Yes, you generally pay your deductible each time you file a collision or comprehensive claim. It is a per-claim amount, not an annual total.
What is a deductible on car insurance if I'm not at fault?
If the other driver is at fault and you file with their insurance, you typically don't pay a deductible. If you use your own collision coverage, you pay it first and your insurer may recover it from the other driver's insurer.
Is a $500 or $1,000 deductible better?
A $1,000 deductible lowers your premium but costs you more when you file a claim. Choose $1,000 only if you have that amount in savings and the yearly premium savings make sense over a few claim-free years.
Does liability insurance have a deductible?
No. Liability coverage pays for damage and injuries you cause to others, and it does not have a deductible.
Can I have different deductibles for collision and comprehensive?
Yes. Most insurers let you choose separate deductibles for each. Many Houston drivers pick a lower comprehensive deductible to protect against hail and flood damage.
Get a Quote in Houston Today
Not sure which deductible fits your budget? AZ Insurance Agency's bilingual agents can quote different deductible options side by side so you can see exactly how much you'd save and what you'd pay on a claim.
Quick Answer: - A deductible in car insurance is the amount you pay out of pocket on a covered claim before your insurance company pays the rest. For example, with a $500 deductible and $3,000 in damage, you pay $500, and your insurer pays $2,500. Deductibles usually apply to collision and comprehensive coverage, not to liability.
When you buy car insurance, you pick a deductible, usually $250, $500, $1,000, or more. It is one of the few numbers on your policy that you control directly, and it affects both your monthly premium and how much you pay when something goes wrong. Yet many drivers don't really know what a deductible in car insurance is until they file their first claim and get a bill they weren't expecting.
The deductible is your share of the repair cost. Your insurance company covers the rest, up to your policy limits. Choosing the right amount is a balance between paying less each month and being able to afford that share when you need it.
This guide explains how car insurance deductibles work with real examples, which coverages have one and which don't, how your deductible changes your premium, how Texas weather claims affect it, and how to choose the right amount for your budget.
How a Car Insurance Deductible Works
Your deductible applies each time you file a claim under a coverage that has one. It is not an annual amount like a health insurance deductible. If you file two separate collision claims in one year, you generally pay the deductible twice.
Here is how a typical claim plays out:
1. You have an accident or your car is damaged by a covered event, such as hail.
2. You file a claim with your insurance company.
3. An adjuster inspects the car and estimates the repair cost.
4. Your insurer subtracts your deductible from the approved amount.
5. The insurer pays the rest to you or directly to the repair shop, and you pay your deductible to the shop.
Example of a $500 Deductible
Jose in Katy backs into a pole, and the repair estimate is $2,400. He has a $500 collision deductible. Jose pays $500 to the body shop, and his insurer pays $1,900.
What If the Damage is Less Than the Deductible?
your insurer pays nothing. A $400 scratch with a $500 deductible is fully your cost, so it usually doesn't make sense to file a claim.
How does a deductible apply to a total loss?
the insurer pays the car's actual cash value minus your deductible. If your car is worth $12,000 and your deductible is $1,000, you would receive $11,000, minus any loan payoff owed to your lender.
What Is a Deductible for Car Insurance Coverages? Which Have One and Which Don't
Not every part of your car insurance policy is deductible. Understanding what a deductible for car insurance applies to helps you know what to expect on different types of claims.
Coverage | Has a Deductible? | What It Covers |
Liability (bodily injury & property damage) | No | Damage and injuries you cause to others |
Collision | Yes | Damage to your car from hitting another car or object |
Comprehensive | Yes | Theft, hail, flood, fire, vandalism, hitting an animal |
Uninsured motorist property damage (TX) | Yes, typically $250 | Damage to your car caused by an uninsured driver |
Personal Injury Protection (PIP) | No | Medical bills and lost wages for you and your passengers |
Uninsured/underinsured motorist bodily injury | No | Your injuries caused by a driver without enough insurance |
Liability has no deductible because it pays other people, not you. If you cause an accident, your insurer pays the other driver's damages up to your limits, and you don't owe a deductible on that part of the claim.
Collision and comprehensive can have different deductibles. Many drivers choose a lower comprehensive deductible, such as $250 or $500, because hail and flood damage are common in Houston, and a higher collision deductible, such as $1,000, to keep premiums down.
How Your Deductible Affects Your Premium
Your deductible and your premium move in opposite directions. A higher deductible means a lower premium, because you are agreeing to take on more of the cost of smaller claims. A lower deductible means a higher premium, because the insurer is taking on more risk.
Deductible | Estimated 6-Month Collision + Comp Premium | Your Cost on a $3,000 Claim | Best For |
$250 | About $520 | $250 | Drivers who want minimal out-of-pocket costs |
$500 | About $450 | $500 | Most drivers; balanced option |
$1,000 | About $380 | $1,000 | Drivers with emergency savings |
$2,000 | About $320 | $2,000 | Drivers with strong savings and older cars |
*Prices may vary based on your specific provider, coverage selections, driving/claims history, and other individual factors. The figures above are estimates only and are not a guarantee of your actual rate. *
In this example, moving from a $500 to a $1,000 deductible saves about $140 a year but costs $500 more if you file a claim. If you go more than three and a half years without a collision or comprehensive claim, the higher deductible comes out ahead. That break-even math is a useful way to compare any two deductible options.
Do I Have to Pay a Deductible if I'm Not at Fault?
Many drivers wonder what a deductible on car insurance means when someone else caused the accident. Generally, you don't pay a deductible when the other driver is at fault and you file with their insurance company. Their liability coverage pays for your repairs.
You can also file with your own collision coverage if you want repairs to start faster or the other insurer is slow to accept fault. In that case, you pay your deductible up front. Your insurer then tries to recover the money from the at-fault driver's insurer through a process called subrogation. If they succeed, you typically get your deductible back, either in full or in part.
If the at-fault Driver is Uninsured
a real risk with about 1 in 5 Texas drivers uninsured, your uninsured motorist property damage coverage can pay for repairs, usually after a $250 deductible. If you don't carry this coverage, you would need to use your collision coverage and pay your collision deductible instead.
Deductibles for Hail, Flood, and Glass Claims in Texas
Houston drivers file a lot of weather-related claims, and most of them fall under comprehensive coverage, so your comprehensive deductible is the one that applies.
Hail
Hail damage is covered under comprehensive. Dent repairs from a major storm can easily run $2,000 to $6,000 or more, so a moderate comprehensive deductible is worth considering in the Houston area.
Flood
Unlike homeowners insurance, car insurance does cover flood damage, but only if you have comprehensive coverage. Flooded cars are often declared a total loss, and the payout is the car's value minus your deductible.
Windshield and Glass
Windshield chips and cracks usually fall under comprehensive. Texas does not require zero-deductible glass coverage, but many insurers offer optional full glass coverage for a small added cost. Ask about it if you drive on highways where rock chips are common.
Tip: If you only lower one deductible, lowering comprehensive often costs less than lowering collision, and it protects you against the weather claims Houston drivers file most often.
How to Choose the Right Car Insurance Deductible
There isn't one right deductible for everyone. Use these questions to find yours:
1. How much could you pay tomorrow without borrowing?
Your deductible should never be more than your available emergency savings.
2. How much does each option save you?
Ask your agent for quotes at $500 and $1,000 and calculate the yearly difference.
3. What is the break-even point?
Divide the extra out-of-pocket cost by the yearly savings to see how many claim-free years it takes to come ahead.
4. How often do you file claims?
If you have had several claims in recent years, a lower deductible may be worth the higher premium.
5. What is your car worth?
On an older car, a high deductible can eat up most of a potential payout.
6. Does your lender have a limit?
If your car is financed or leased, your lender will likely require collision and comprehensive, and many cap the deductible at $500 or $1,000.
Deductible vs. Premium vs. Coverage Limit: Key Terms Explained
Three numbers on your policy work together, and mixing them up is one of the most common sources of confusion:
Term | What It Means | Example |
Premium | What you pay the insurer to keep your policy active, monthly or every six months | $150 per month |
Deductible | What you pay toward your own covered claim before insurance pays | $500 per collision claim |
Coverage limit | The most your insurer will pay on a covered claim | $30,000 per person for bodily injury |
Out-of-pocket cost | Your total cost on a claim, including the deductible and anything above your limits | $500 deductible + any amount over your limit |
Think of it this way: your premium is the price of the policy, your deductible is your share of each claim on your own car, and your limit is the ceiling on what the insurer pays. Raising your deductible lowers your premium, while raising your limits raises your premium but gives you more protection.
Should You File a Claim or Pay Out of Pocket?
Just because damage is covered doesn't always mean you should file a claim. Filing a small claim can raise your premium at renewal, especially for an at-fault collision, and that increase can last for several years. Before you file, compare the repair estimate with your deductible and the possible rate increase.
Repair Estimate | Deductible | Insurance Would Pay | Usually Makes Sense To… |
$700 | $500 | $200 | Pay out of pocket |
$1,400 | $500 | $900 | Get advice; depends on fault and your record |
$4,500 | $500 | $4,000 | File a claim |
$6,000 (hail) | $500 | $5,500 | File a claim |
Not-at-fault and weather claims generally affect your rate less than at-fault accidents, but every carrier treats claims differently. Your agent can help you weigh the numbers before you file. If anyone was injured, always report the accident to your insurer, even if the vehicle damage is small.
Can You Change Your Car Insurance Deductible?
Yes. You can usually change your deductible at any time by contacting your agent or insurer, not just at renewal. The new deductible applies to claims that happen after the change takes effect, so you can't lower it after an accident to reduce what you owe on that claim.
It is smart to review your deductible when your finances change. If you have built up more emergency savings, raising your deductible can lower your premium. If money is tighter, lowering it can protect you from a large bill at a bad time. A good time to check is also right before hurricane and hail season, when comprehensive claims in the Houston area tend to rise.
Example: Linh in Pearland had a $1,000 deductible when she started a new job. After six months of building savings, she kept her $1,000 collision deductible but lowered her comprehensive deductible to $500 ahead of spring hail season. The small premium increase gave her more protection against the claims she was most likely to file.
Quick rule of thumb: If you have at least $1,000 set aside for emergencies and a clean claims history, a $1,000 collision deductible usually gives you the best value. If your savings are thin, you drive in heavy Houston traffic every day, or you've had a claim in the last few years, a $500 deductible is often the safer middle ground. Whatever you choose, write your deductible amounts down and keep them with your insurance card, so you know exactly what to expect if you ever need to file a claim.
What If You Can't Afford Your Deductible?
If your car is damaged and you don't have the deductible ready, you still have options:
Ask the body shop about a payment plan.
Many repair shops will let you pay for the deductible installments.
Check whether the other driver is at fault.
If so, filing with their liability insurance means you don't owe a deductible.
Ask your insurer about direct payment.
In many cases, the insurer pays the shop directly and you only pay your deductible when you pick up the car, giving you a little time to arrange it.
Review your deductible going forward.
If this situation surprised you, lowering your deductible at your next policy change can prevent it from happening again.
Financed or leased car? Your lender cares about your deductible too, because the car is their collateral. Most loan and lease contracts require collision and comprehensive with a maximum deductible, commonly $500 or $1,000. If you raise your deductible above your lender's limit, you could be in violation of your contract, so check your paperwork before making a change.
Common Myths About Car Insurance Deductibles
Myth: You pay your deductible once a year.
Car insurance deductibles apply per claim, not per year.
Myth: You pay a deductible if you hit someone else's car.
Damage you cause to other people is paid by your liability coverage, which has no deductible. You only pay a deductible if you use a collision to fix your own car.
Myth: The lowest deductible is always the smartest choice.
A $250 deductible can cost you more in premiums over a few years than you would ever save on claims.
Myth: Your insurer pays the deductible if you're not at fault.
You avoid it by claiming against the other driver's insurance, or you can get it back through subrogation, but your own insurer does not waive it automatically.
Myth: Car insurance doesn't cover floods.
Comprehensive coverage does cover flood damage to your car.
Frequently Asked Questions
What is a deductible in car insurance in simple terms?
A deductible is the part of a covered claim you pay yourself before your insurance pays the rest. If you have a $500 deductible and $2,000 in damage, you pay $500 and your insurer pays $1,500.
What is a deductible for car insurance, and do I pay it every time?
Yes, you generally pay your deductible each time you file a collision or comprehensive claim. It is a per-claim amount, not an annual total.
What is a deductible on car insurance if I'm not at fault?
If the other driver is at fault and you file with their insurance, you typically don't pay a deductible. If you use your own collision coverage, you pay it first and your insurer may recover it from the other driver's insurer.
Is a $500 or $1,000 deductible better?
A $1,000 deductible lowers your premium but costs you more when you file a claim. Choose $1,000 only if you have that amount in savings and the yearly premium savings make sense over a few claim-free years.
Does liability insurance have a deductible?
No. Liability coverage pays for damage and injuries you cause to others, and it does not have a deductible.
Can I have different deductibles for collision and comprehensive?
Yes. Most insurers let you choose separate deductibles for each. Many Houston drivers pick a lower comprehensive deductible to protect against hail and flood damage.
Get a Quote in Houston Today
Not sure which deductible fits your budget? AZ Insurance Agency's bilingual agents can quote different deductible options side by side so you can see exactly how much you'd save and what you'd pay on a claim.
Latest Blogs

Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Dropped by Your Texas Home Insurer? What a Nonrenewal Notice Must Tell You and What to Do in the Next 60 Days
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
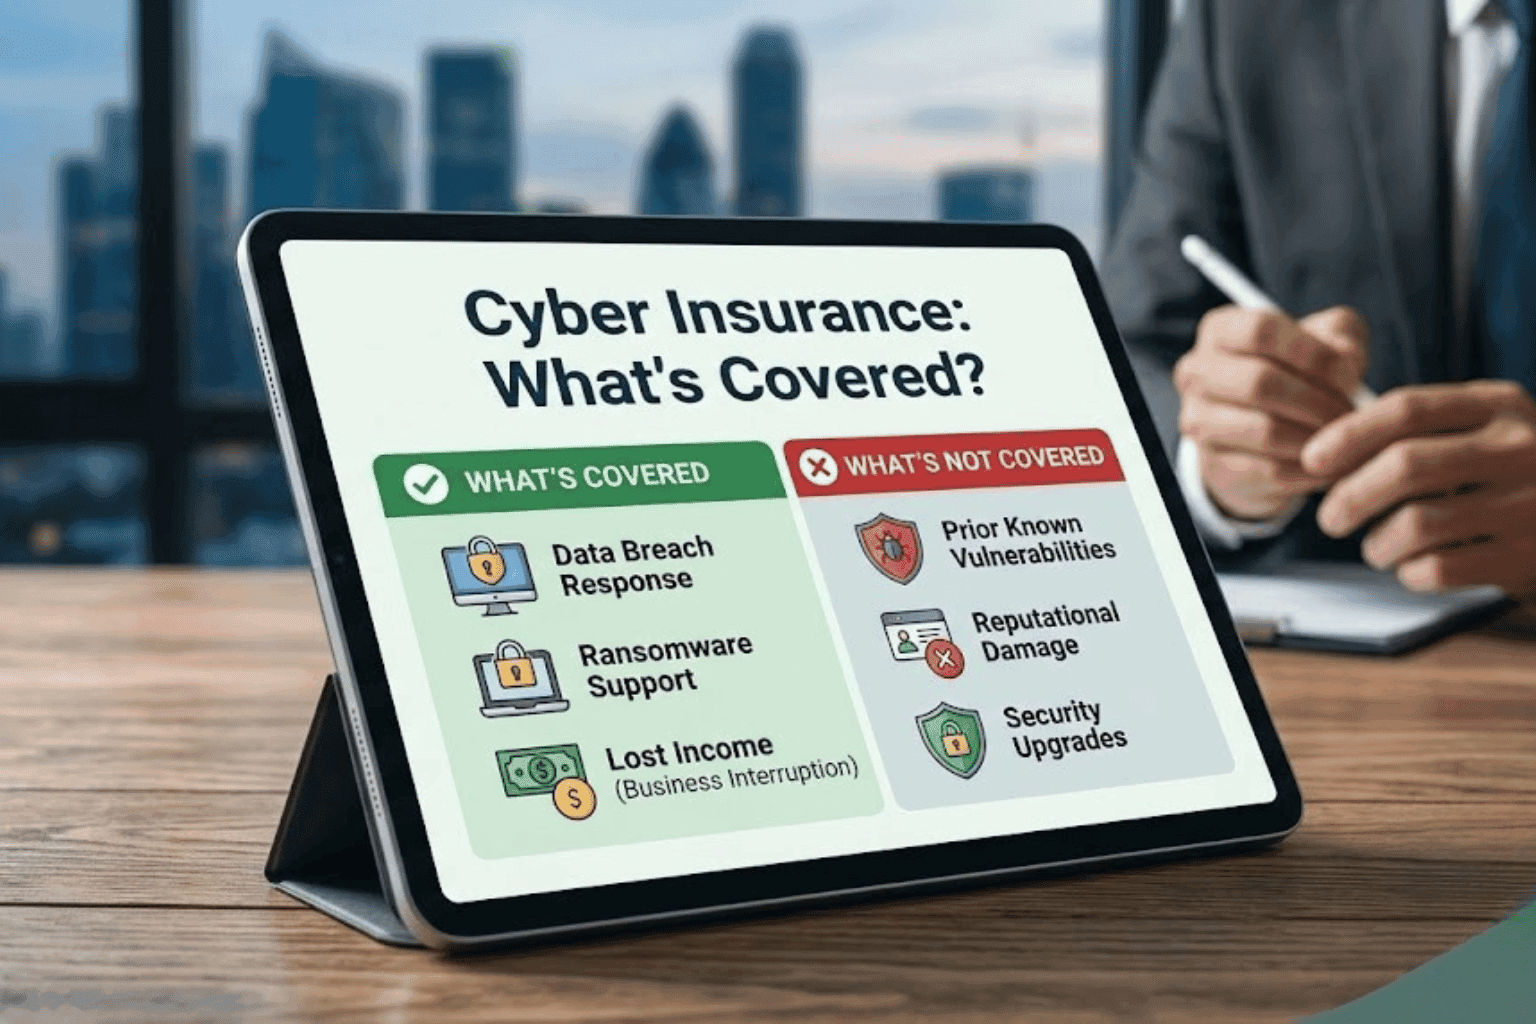
What Does Cyber Insurance Cover (and Not Cover)? Full Guide

How Much Is ATV Insurance? Average Costs and Factors
Your Tools Were Stolen Off the Truck. Which Policy Actually Pays?
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
Your general liability answers for a dropped ladder, not for bad advice or a wrong drawing. Here is where the line sits in Texas, and the rule that makes suing a designer harder here.
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
Your general liability answers for a dropped ladder, not for bad advice or a wrong drawing. Here is where the line sits in Texas, and the rule that makes suing a designer harder here.
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
Your general liability answers for a dropped ladder, not for bad advice or a wrong drawing. Here is where the line sits in Texas, and the rule that makes suing a designer harder here.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
Your general liability answers for a dropped ladder, not for bad advice or a wrong drawing. Here is where the line sits in Texas, and the rule that makes suing a designer harder here.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.