Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For

Quick Answer: At a 2026 Texas home insurance renewal you can ask an insurer that uses credit to rerun it and rerate your policy, once every 12 months. Your home policy cannot be made conditional on buying auto from the same company, and a widowed homeowner cannot be charged differently. The roof age rule announced in September is only planned.
What this article covers
Why renewal is the moment that matters
Right 1: ask for a credit recheck
Right 2: bundling is your choice, not a condition
Right 3: a widowed homeowner keeps the married rate
Right 4: notice before the price jumps or the coverage shrinks
What changed on September 16, and what did not
Your renewal checklist
Frequently asked questions
Why renewal is the moment that matters
Most homeowners treat the renewal packet like a bill. Check the total, sigh, pay it, put it in the drawer.
That is the one moment of the year when the most rights are in your hands. Three Texas laws that took effect September 1, 2025 all work at renewal, and one of them only works if you ask. Whether you live in Baytown, Humble, Spring, Plano or Lewisville, these are state laws, so they apply to your policy the same way.
This article is for everyone whose policy is renewing. If your insurer sent a letter saying it will not renew you, that is a different set of rules with a different clock, and we cover it step by step in what a Texas nonrenewal notice must tell you and what to do in the next 60 days.
Key Takeaways
You can ask for a credit recheck at renewal, once every 12 months. It is a request, not an automatic benefit. You or your agent has to make it.
Homeowners already in their insurer's best priced tier are exempt, because there is no better tier to move to.
Your home policy cannot be tied to buying your auto policy from the same insurer or an affiliate. A bundle can be offered. It cannot be required.
A widowed homeowner cannot be charged a different rate than a married one, or dropped because a spouse died.
A renewal increase of 10 percent or more requires notice at least 30 days before it takes effect.
The roof age rule announced September 16 is not in effect. The Texas Department of Insurance says it plans to propose it.
Your right | The law | In effect | What you do |
|---|---|---|---|
Ask for a credit recheck and rerate | SB 1644, Insurance Code 559.058 | Policies issued or renewed on or after January 1, 2026 | Ask at renewal, ideally in writing |
Buy home and auto from different companies | SB 213, Insurance Code 551.254 | September 1, 2025 | Shop each policy on its own merits |
Same rate as a married homeowner after a spouse dies | SB 1238, Insurance Code 544.002 | Policies issued or renewed on or after September 1, 2025 | Check the rate after your marital status changes |
30 days notice of a 10 percent or larger increase | Insurance Code 2251.005 | Long standing | Compare the notice date to your renewal date |
Right 1: ask for a credit recheck
Texas lets insurers use credit based insurance scores to help set home and auto rates. What changed is that you now have a way to make that score current.
Senate Bill 1644 added Section 559.058 to the Insurance Code. On renewal of a policy, the insurer "shall, on request of an insured or the insured's agent, re underwrite and re rate the policy based upon a current credit report or insurance score, not exceeding once each 12 month period." It applies to policies delivered, issued or renewed on or after January 1, 2026, which means every renewal happening now. You can read the enrolled bill text yourself.
Three details decide whether it helps you.
It is a request. Nothing in the statute requires your insurer to tell you the option exists. If nobody asks, nothing happens. The law names two people who can ask: you, or your agent. That second name is not an accident. It is one of the reasons to have an agent who reads your renewal before you pay it.
The best tier is exempt. The law does not require a rerate if you are already in the insurer's most favorably priced tier, or if the insurer does not use credit on that policy at all.
There is also a slower automatic refresh. Separately, an insurer that uses credit must review and update your credit report at least every 36 months and reassess your rating. So the most you should wait for a refreshed score without asking is three years. Asking cuts that to one.
Your situation | Is a recheck worth asking for? |
|---|---|
Your credit improved since you bought the policy | Yes, this is exactly who the law was written for |
You paid off a loan or cleared a collection | Yes, ask at the next renewal |
You are already in the insurer's best priced tier | Not required, and there is nowhere better to move |
Your insurer does not use credit on your policy | The rule does not apply |
Your credit got worse | Think first, because a current score works in both directions |
You already asked within the last 12 months | The insurer can wait until the 12 months pass |
Two protections sit next to this one. The Texas Department of Insurance says on its credit scoring page that a company cannot refuse to sell you a policy, or cancel or not renew it, based solely on your credit. TDI also says companies must make exceptions when your credit was hurt by certain life events, including a divorce, a temporary loss of a job, identity theft, or the death of a spouse, child or parent. If one of those applies to you, tell your agent before the recheck, not after.
Right 2: bundling is your choice, not a condition
The fear shows up in almost every renewal conversation: "If I move my car insurance, will they raise my house or drop it?"
Senate Bill 213 answered the second half. Since September 1, 2025, Section 551.254 of the Insurance Code makes it an unfair practice "to make the issuance, delivery, or renewal of a residential property insurance policy contingent on the purchase of a personal automobile insurance policy from the same insurer or an affiliated insurer," and the reverse. Here is the enrolled text.
The law bans the condition. It does not ban the discount. A company can still offer you a lower price for carrying both policies with it, and for many households a bundle is still the better deal. What changed is that the bundle has to win on price and coverage, because your home policy is no longer hostage to it.
At renewal, your insurer CAN | At renewal, your insurer CANNOT |
|---|---|
Offer a multi policy discount for home and auto together | Make renewing your home policy depend on buying its auto policy |
Price your home policy without that discount if you move your auto | Refuse to renew your home only because your auto is elsewhere |
Ask what other policies you carry | Require an affiliated company's auto policy as the price of a home policy |
Three kinds of policies are outside the law: Texas Windstorm Insurance Association policies, National Flood Insurance Program policies and personal umbrella policies.
In practice, this is what makes it safe to shop each policy separately. If your car insurance is the one that has gone up, we covered how to move it cleanly in how to switch car insurance easily in 2026. Moving it does not put your house at risk.
Right 3: a widowed homeowner keeps the married rate
This one gets almost no attention, and it matters most to the people least likely to be reading insurance news in the weeks after a funeral.
Senate Bill 1238 amended Section 544.002 of the Insurance Code. An insurer may not refuse to continue to insure someone, or limit their coverage, "because the individual is widowed or the individual's marital status otherwise reflects the death of a spouse," and it may not charge a widowed person "a rate that is different from the rate that would be charged if the individual's marital status was married." The rule applies to policies delivered, issued or renewed on or after September 1, 2025, and it sits in the general unfair discrimination chapter, so it is not limited to home insurance. Read the enrolled bill.
What to do with it: after a spouse dies, the policy usually needs to be updated anyway, to change the named insured or confirm who owns the home. When you make that change, compare the renewal premium to the prior year. If the only thing that changed is marital status, the rate should not move because of it.
Get a free home insurance renewal review or call (281) 833-5060. Hablamos Español.
Right 4: notice before the price jumps or the coverage shrinks
Two older rules protect you at every renewal, and both come with a 30 day clock.
A big increase needs advance notice. Under Section 2251.005 of the Insurance Code, if a rate increase at renewal will make your premium at least 10 percent higher than what you paid for the prior period, the insurer must notify you before the renewal date and no later than the 30th day before the increase takes effect.
A coverage cut needs plain language notice. A renewal that reduces your coverage, such as moving your roof from replacement cost to actual cash value, must come with a notice that clearly states each material change, at least 30 days before the renewal date, under Section 551.1055. That is the quiet version of losing coverage, and our guide to actual cash value vs replacement cost in Texas shows what it costs after a claim.
Weather claims have their own protection. Under TDI's Consumer Bill of Rights for homeowners, a claim for damage from natural causes cannot be used to raise your premium or to refuse your renewal, which we explain in will a storm claim raise my Texas home insurance rate. If a storm hit close to your renewal date, the timing questions are in what happens when a storm hits before your renewal.
And if you have been loyal for years and the price keeps climbing anyway, TDI addressed that directly. Commissioner's Bulletin B-0007-26, dated September 2, 2026, describes price optimization as varying premiums based on factors unrelated to risk or expense so a company can charge the highest price policyholders will tolerate before shopping, and states: "Any use of price optimization in the ratemaking or pricing process, or in establishing a rating plan, is unfairly discriminatory and violates the Insurance Code." That is TDI's reading of existing law, not a new ban. You can read the bulletin.
What changed on September 16, and what did not
September brought a lot of headlines about Texas home insurance. Here is what each one actually is, as of the date this was written.
Item | Date | Status today |
|---|---|---|
Price optimization bulletin, B-0007-26 | September 2, 2026 | In effect as TDI's reading of existing law |
FORTIFIED roof bulletin, B-0008-26 | September 16, 2026 | Encouragement only. TDI encourages insurers to offer discounts. No requirement |
Roof age rule | Announced September 16, 2026 | Not in effect and not yet formally proposed. TDI plans to propose it |
Updated Consumer Bill of Rights for home and auto | Adopted September 18, 2026 | Takes effect January 1, 2027 |
ZIP code tool showing why home policies are declined, canceled or not renewed | September 23, 2026 | Live now for home. TDI plans to add auto later this year |
FORTIFIED roofs. In Bulletin B-0008-26, titled "Premium discounts for loss mitigation," TDI "encourages all property and casualty insurance companies operating in Texas to develop meaningful, actuarially supported premium discounts" for mitigation such as a FORTIFIED roof, impact resistant roofing and wildfire protection. You may have seen it described as a requirement. The bulletin itself says encourages. In its release the same day, TDI said it recommends changes to state law that would require insurers to consider mitigation when setting rates, for the legislative session that begins in January. If you are replacing a roof anyway, ask which companies give real credit for a FORTIFIED roof before you choose the roofing spec.
Roof age. Texas already prohibits an insurer from refusing to renew based on the age of your property. It can still refuse based on the condition of the property, including the roof. In its September 14 letter to the Governor, TDI said some companies use the age of individual components as a stand in for condition, and that it "plans to propose a rule clarifying the prohibition on considering the age of individual components." A planned rule is not a rule. Until one is proposed, adopted and in effect, the condition of your roof still matters at renewal. Our guide to how roof age affects Texas home insurance covers what carriers look at today, and does home insurance cover roof damage or leaks covers what a claim pays.
Your renewal checklist
TDI publishes its own renewal checklist. Here it is combined with the rights above, in the order we would work through it.
What to check | Where to find it | Why it matters |
|---|---|---|
Did the roof coverage change? | Declarations page, loss settlement line | A switch to actual cash value can cut a roof claim sharply |
Are the details about your house right? | Declarations page | Wrong square footage, roof age or construction type can misprice the policy |
What are your deductibles, in dollars? | Declarations page, wind and hail line | A percentage deductible is a percentage of your dwelling limit |
Were coverages added or taken away? | Endorsement list at the back | New exclusions arrive quietly at renewal |
Did the premium rise 10 percent or more? | The renewal notice | Confirm the notice came at least 30 days ahead |
Has your credit improved? | Your own credit report | You or your agent can ask for a rerate |
Did your marital status change? | Named insured section | A widowed homeowner cannot be charged differently |
Three of those rows deserve a second look. The wind and hail deductible is where most renewal surprises hide, and our explainer on why a 2 percent storm deductible does not mean $200 does the math. Your dwelling limit should track what it costs to rebuild today, which we walk through in how much dwelling coverage your Houston home needs. And the policy form itself decides what is covered at all, so it is worth knowing the difference between HO-A, HO-B and HO-3 policies in Texas before you accept a renewal on a narrower form.
If an endorsement page leaves you unsure what the base policy still covers, start with what homeowners insurance covers and does not cover.
One thing no renewal changes: flood is still not in a homeowners policy anywhere in Texas. If you have never priced it, renewal is a natural time, and we explain the gap in does homeowners insurance cover flood in Texas. For the ten minute version of reading your own policy, see your roof before the storm, the four things to check.
If you decide to shop, a new company will ask for the same handful of documents, and our list of information needed for a homeowners insurance quote saves a round of phone calls.
Frequently asked questions
Q: Can I ask my Texas home insurer to recheck my credit at renewal?
Yes. Under Insurance Code Section 559.058, added by SB 1644, an insurer that uses credit must, on request of the insured or the insured's agent, rerate the policy on a current credit report or insurance score at renewal, no more than once every 12 months. It applies to policies issued or renewed on or after January 1, 2026.
Q: Will my insurer recheck my credit automatically?
Only slowly. An insurer that uses credit must update your credit report at least every 36 months and reassess your rating. The once a year recheck happens only if you or your agent asks for it.
Q: Who is not eligible for the credit recheck?
The law does not require it if you are already in the insurer's most favorably priced tier, or if the insurer does not use credit on that policy.
Q: Do I have to buy my car insurance from my home insurance company?
No. Since September 1, 2025, Texas law makes it an unfair practice to make a home policy's issuance or renewal contingent on buying a personal auto policy from the same or an affiliated insurer. The company can still offer a bundle discount. It cannot require the bundle.
Q: My husband passed away. Can my home insurance rate go up because I am now a widow?
Not because of that. SB 1238 bars an insurer from charging a widowed person a different rate than it would charge if they were married, and from refusing to continue coverage for that reason. It applies to policies issued or renewed on or after September 1, 2025.
Q: Is the new Texas roof age rule in effect?
No. The Governor announced on September 16, 2026 that TDI would propose a rule clarifying the existing prohibition on using the age of the property, including components like the roof. TDI says it plans to propose that rule. As of this writing it has not been proposed. The condition of your roof can still be a reason for nonrenewal.
Q: Are insurers now required to give a discount for a FORTIFIED roof?
No. TDI Bulletin B-0008-26 encourages insurers to offer meaningful discounts for homes built to resist wind and hail. It does not require them. Ask your agent which companies actually give credit for it.
Q: How much notice do I get before a big renewal increase?
If a rate increase at renewal raises your premium by 10 percent or more, Section 2251.005 of the Insurance Code requires the insurer to notify you no later than the 30th day before the increase takes effect.
Related Articles
What a Texas nonrenewal notice must tell you, and your next 60 days
Your roof and Texas home insurance: age, depreciation and nonrenewal
Why AZ Insurance Stands Apart
Every right in this article either has to be asked for or has to be noticed. A credit recheck only happens on request, and the law names your agent as someone who can make it. A bundle only helps if someone prices both policies apart and together. A coverage cut only matters if someone reads the endorsement page before the premium is paid. That is the job we do. AZ Insurance has served Texas homeowners since 2003 from 15 offices across Houston and Dallas, we compare multiple insurance companies rather than defending one, and we read renewals in English or Spanish.
Bring us your renewal packet before you pay it. Request a free home insurance renewal review or call our homeowners line at (281) 833-5060, and we will tell you which of these four rights applies to your policy and ask for the ones that do.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. We are happy to read it with you.
Quick Answer: At a 2026 Texas home insurance renewal you can ask an insurer that uses credit to rerun it and rerate your policy, once every 12 months. Your home policy cannot be made conditional on buying auto from the same company, and a widowed homeowner cannot be charged differently. The roof age rule announced in September is only planned.
What this article covers
Why renewal is the moment that matters
Right 1: ask for a credit recheck
Right 2: bundling is your choice, not a condition
Right 3: a widowed homeowner keeps the married rate
Right 4: notice before the price jumps or the coverage shrinks
What changed on September 16, and what did not
Your renewal checklist
Frequently asked questions
Why renewal is the moment that matters
Most homeowners treat the renewal packet like a bill. Check the total, sigh, pay it, put it in the drawer.
That is the one moment of the year when the most rights are in your hands. Three Texas laws that took effect September 1, 2025 all work at renewal, and one of them only works if you ask. Whether you live in Baytown, Humble, Spring, Plano or Lewisville, these are state laws, so they apply to your policy the same way.
This article is for everyone whose policy is renewing. If your insurer sent a letter saying it will not renew you, that is a different set of rules with a different clock, and we cover it step by step in what a Texas nonrenewal notice must tell you and what to do in the next 60 days.
Key Takeaways
You can ask for a credit recheck at renewal, once every 12 months. It is a request, not an automatic benefit. You or your agent has to make it.
Homeowners already in their insurer's best priced tier are exempt, because there is no better tier to move to.
Your home policy cannot be tied to buying your auto policy from the same insurer or an affiliate. A bundle can be offered. It cannot be required.
A widowed homeowner cannot be charged a different rate than a married one, or dropped because a spouse died.
A renewal increase of 10 percent or more requires notice at least 30 days before it takes effect.
The roof age rule announced September 16 is not in effect. The Texas Department of Insurance says it plans to propose it.
Your right | The law | In effect | What you do |
|---|---|---|---|
Ask for a credit recheck and rerate | SB 1644, Insurance Code 559.058 | Policies issued or renewed on or after January 1, 2026 | Ask at renewal, ideally in writing |
Buy home and auto from different companies | SB 213, Insurance Code 551.254 | September 1, 2025 | Shop each policy on its own merits |
Same rate as a married homeowner after a spouse dies | SB 1238, Insurance Code 544.002 | Policies issued or renewed on or after September 1, 2025 | Check the rate after your marital status changes |
30 days notice of a 10 percent or larger increase | Insurance Code 2251.005 | Long standing | Compare the notice date to your renewal date |
Right 1: ask for a credit recheck
Texas lets insurers use credit based insurance scores to help set home and auto rates. What changed is that you now have a way to make that score current.
Senate Bill 1644 added Section 559.058 to the Insurance Code. On renewal of a policy, the insurer "shall, on request of an insured or the insured's agent, re underwrite and re rate the policy based upon a current credit report or insurance score, not exceeding once each 12 month period." It applies to policies delivered, issued or renewed on or after January 1, 2026, which means every renewal happening now. You can read the enrolled bill text yourself.
Three details decide whether it helps you.
It is a request. Nothing in the statute requires your insurer to tell you the option exists. If nobody asks, nothing happens. The law names two people who can ask: you, or your agent. That second name is not an accident. It is one of the reasons to have an agent who reads your renewal before you pay it.
The best tier is exempt. The law does not require a rerate if you are already in the insurer's most favorably priced tier, or if the insurer does not use credit on that policy at all.
There is also a slower automatic refresh. Separately, an insurer that uses credit must review and update your credit report at least every 36 months and reassess your rating. So the most you should wait for a refreshed score without asking is three years. Asking cuts that to one.
Your situation | Is a recheck worth asking for? |
|---|---|
Your credit improved since you bought the policy | Yes, this is exactly who the law was written for |
You paid off a loan or cleared a collection | Yes, ask at the next renewal |
You are already in the insurer's best priced tier | Not required, and there is nowhere better to move |
Your insurer does not use credit on your policy | The rule does not apply |
Your credit got worse | Think first, because a current score works in both directions |
You already asked within the last 12 months | The insurer can wait until the 12 months pass |
Two protections sit next to this one. The Texas Department of Insurance says on its credit scoring page that a company cannot refuse to sell you a policy, or cancel or not renew it, based solely on your credit. TDI also says companies must make exceptions when your credit was hurt by certain life events, including a divorce, a temporary loss of a job, identity theft, or the death of a spouse, child or parent. If one of those applies to you, tell your agent before the recheck, not after.
Right 2: bundling is your choice, not a condition
The fear shows up in almost every renewal conversation: "If I move my car insurance, will they raise my house or drop it?"
Senate Bill 213 answered the second half. Since September 1, 2025, Section 551.254 of the Insurance Code makes it an unfair practice "to make the issuance, delivery, or renewal of a residential property insurance policy contingent on the purchase of a personal automobile insurance policy from the same insurer or an affiliated insurer," and the reverse. Here is the enrolled text.
The law bans the condition. It does not ban the discount. A company can still offer you a lower price for carrying both policies with it, and for many households a bundle is still the better deal. What changed is that the bundle has to win on price and coverage, because your home policy is no longer hostage to it.
At renewal, your insurer CAN | At renewal, your insurer CANNOT |
|---|---|
Offer a multi policy discount for home and auto together | Make renewing your home policy depend on buying its auto policy |
Price your home policy without that discount if you move your auto | Refuse to renew your home only because your auto is elsewhere |
Ask what other policies you carry | Require an affiliated company's auto policy as the price of a home policy |
Three kinds of policies are outside the law: Texas Windstorm Insurance Association policies, National Flood Insurance Program policies and personal umbrella policies.
In practice, this is what makes it safe to shop each policy separately. If your car insurance is the one that has gone up, we covered how to move it cleanly in how to switch car insurance easily in 2026. Moving it does not put your house at risk.
Right 3: a widowed homeowner keeps the married rate
This one gets almost no attention, and it matters most to the people least likely to be reading insurance news in the weeks after a funeral.
Senate Bill 1238 amended Section 544.002 of the Insurance Code. An insurer may not refuse to continue to insure someone, or limit their coverage, "because the individual is widowed or the individual's marital status otherwise reflects the death of a spouse," and it may not charge a widowed person "a rate that is different from the rate that would be charged if the individual's marital status was married." The rule applies to policies delivered, issued or renewed on or after September 1, 2025, and it sits in the general unfair discrimination chapter, so it is not limited to home insurance. Read the enrolled bill.
What to do with it: after a spouse dies, the policy usually needs to be updated anyway, to change the named insured or confirm who owns the home. When you make that change, compare the renewal premium to the prior year. If the only thing that changed is marital status, the rate should not move because of it.
Get a free home insurance renewal review or call (281) 833-5060. Hablamos Español.
Right 4: notice before the price jumps or the coverage shrinks
Two older rules protect you at every renewal, and both come with a 30 day clock.
A big increase needs advance notice. Under Section 2251.005 of the Insurance Code, if a rate increase at renewal will make your premium at least 10 percent higher than what you paid for the prior period, the insurer must notify you before the renewal date and no later than the 30th day before the increase takes effect.
A coverage cut needs plain language notice. A renewal that reduces your coverage, such as moving your roof from replacement cost to actual cash value, must come with a notice that clearly states each material change, at least 30 days before the renewal date, under Section 551.1055. That is the quiet version of losing coverage, and our guide to actual cash value vs replacement cost in Texas shows what it costs after a claim.
Weather claims have their own protection. Under TDI's Consumer Bill of Rights for homeowners, a claim for damage from natural causes cannot be used to raise your premium or to refuse your renewal, which we explain in will a storm claim raise my Texas home insurance rate. If a storm hit close to your renewal date, the timing questions are in what happens when a storm hits before your renewal.
And if you have been loyal for years and the price keeps climbing anyway, TDI addressed that directly. Commissioner's Bulletin B-0007-26, dated September 2, 2026, describes price optimization as varying premiums based on factors unrelated to risk or expense so a company can charge the highest price policyholders will tolerate before shopping, and states: "Any use of price optimization in the ratemaking or pricing process, or in establishing a rating plan, is unfairly discriminatory and violates the Insurance Code." That is TDI's reading of existing law, not a new ban. You can read the bulletin.
What changed on September 16, and what did not
September brought a lot of headlines about Texas home insurance. Here is what each one actually is, as of the date this was written.
Item | Date | Status today |
|---|---|---|
Price optimization bulletin, B-0007-26 | September 2, 2026 | In effect as TDI's reading of existing law |
FORTIFIED roof bulletin, B-0008-26 | September 16, 2026 | Encouragement only. TDI encourages insurers to offer discounts. No requirement |
Roof age rule | Announced September 16, 2026 | Not in effect and not yet formally proposed. TDI plans to propose it |
Updated Consumer Bill of Rights for home and auto | Adopted September 18, 2026 | Takes effect January 1, 2027 |
ZIP code tool showing why home policies are declined, canceled or not renewed | September 23, 2026 | Live now for home. TDI plans to add auto later this year |
FORTIFIED roofs. In Bulletin B-0008-26, titled "Premium discounts for loss mitigation," TDI "encourages all property and casualty insurance companies operating in Texas to develop meaningful, actuarially supported premium discounts" for mitigation such as a FORTIFIED roof, impact resistant roofing and wildfire protection. You may have seen it described as a requirement. The bulletin itself says encourages. In its release the same day, TDI said it recommends changes to state law that would require insurers to consider mitigation when setting rates, for the legislative session that begins in January. If you are replacing a roof anyway, ask which companies give real credit for a FORTIFIED roof before you choose the roofing spec.
Roof age. Texas already prohibits an insurer from refusing to renew based on the age of your property. It can still refuse based on the condition of the property, including the roof. In its September 14 letter to the Governor, TDI said some companies use the age of individual components as a stand in for condition, and that it "plans to propose a rule clarifying the prohibition on considering the age of individual components." A planned rule is not a rule. Until one is proposed, adopted and in effect, the condition of your roof still matters at renewal. Our guide to how roof age affects Texas home insurance covers what carriers look at today, and does home insurance cover roof damage or leaks covers what a claim pays.
Your renewal checklist
TDI publishes its own renewal checklist. Here it is combined with the rights above, in the order we would work through it.
What to check | Where to find it | Why it matters |
|---|---|---|
Did the roof coverage change? | Declarations page, loss settlement line | A switch to actual cash value can cut a roof claim sharply |
Are the details about your house right? | Declarations page | Wrong square footage, roof age or construction type can misprice the policy |
What are your deductibles, in dollars? | Declarations page, wind and hail line | A percentage deductible is a percentage of your dwelling limit |
Were coverages added or taken away? | Endorsement list at the back | New exclusions arrive quietly at renewal |
Did the premium rise 10 percent or more? | The renewal notice | Confirm the notice came at least 30 days ahead |
Has your credit improved? | Your own credit report | You or your agent can ask for a rerate |
Did your marital status change? | Named insured section | A widowed homeowner cannot be charged differently |
Three of those rows deserve a second look. The wind and hail deductible is where most renewal surprises hide, and our explainer on why a 2 percent storm deductible does not mean $200 does the math. Your dwelling limit should track what it costs to rebuild today, which we walk through in how much dwelling coverage your Houston home needs. And the policy form itself decides what is covered at all, so it is worth knowing the difference between HO-A, HO-B and HO-3 policies in Texas before you accept a renewal on a narrower form.
If an endorsement page leaves you unsure what the base policy still covers, start with what homeowners insurance covers and does not cover.
One thing no renewal changes: flood is still not in a homeowners policy anywhere in Texas. If you have never priced it, renewal is a natural time, and we explain the gap in does homeowners insurance cover flood in Texas. For the ten minute version of reading your own policy, see your roof before the storm, the four things to check.
If you decide to shop, a new company will ask for the same handful of documents, and our list of information needed for a homeowners insurance quote saves a round of phone calls.
Frequently asked questions
Q: Can I ask my Texas home insurer to recheck my credit at renewal?
Yes. Under Insurance Code Section 559.058, added by SB 1644, an insurer that uses credit must, on request of the insured or the insured's agent, rerate the policy on a current credit report or insurance score at renewal, no more than once every 12 months. It applies to policies issued or renewed on or after January 1, 2026.
Q: Will my insurer recheck my credit automatically?
Only slowly. An insurer that uses credit must update your credit report at least every 36 months and reassess your rating. The once a year recheck happens only if you or your agent asks for it.
Q: Who is not eligible for the credit recheck?
The law does not require it if you are already in the insurer's most favorably priced tier, or if the insurer does not use credit on that policy.
Q: Do I have to buy my car insurance from my home insurance company?
No. Since September 1, 2025, Texas law makes it an unfair practice to make a home policy's issuance or renewal contingent on buying a personal auto policy from the same or an affiliated insurer. The company can still offer a bundle discount. It cannot require the bundle.
Q: My husband passed away. Can my home insurance rate go up because I am now a widow?
Not because of that. SB 1238 bars an insurer from charging a widowed person a different rate than it would charge if they were married, and from refusing to continue coverage for that reason. It applies to policies issued or renewed on or after September 1, 2025.
Q: Is the new Texas roof age rule in effect?
No. The Governor announced on September 16, 2026 that TDI would propose a rule clarifying the existing prohibition on using the age of the property, including components like the roof. TDI says it plans to propose that rule. As of this writing it has not been proposed. The condition of your roof can still be a reason for nonrenewal.
Q: Are insurers now required to give a discount for a FORTIFIED roof?
No. TDI Bulletin B-0008-26 encourages insurers to offer meaningful discounts for homes built to resist wind and hail. It does not require them. Ask your agent which companies actually give credit for it.
Q: How much notice do I get before a big renewal increase?
If a rate increase at renewal raises your premium by 10 percent or more, Section 2251.005 of the Insurance Code requires the insurer to notify you no later than the 30th day before the increase takes effect.
Related Articles
What a Texas nonrenewal notice must tell you, and your next 60 days
Your roof and Texas home insurance: age, depreciation and nonrenewal
Why AZ Insurance Stands Apart
Every right in this article either has to be asked for or has to be noticed. A credit recheck only happens on request, and the law names your agent as someone who can make it. A bundle only helps if someone prices both policies apart and together. A coverage cut only matters if someone reads the endorsement page before the premium is paid. That is the job we do. AZ Insurance has served Texas homeowners since 2003 from 15 offices across Houston and Dallas, we compare multiple insurance companies rather than defending one, and we read renewals in English or Spanish.
Bring us your renewal packet before you pay it. Request a free home insurance renewal review or call our homeowners line at (281) 833-5060, and we will tell you which of these four rights applies to your policy and ask for the ones that do.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. We are happy to read it with you.
Latest Blogs
Dropped by Your Texas Home Insurer? What a Nonrenewal Notice Must Tell You and What to Do in the Next 60 Days
General Liability Will Not Pay for a Mistake. What Professional Liability Covers in Texas
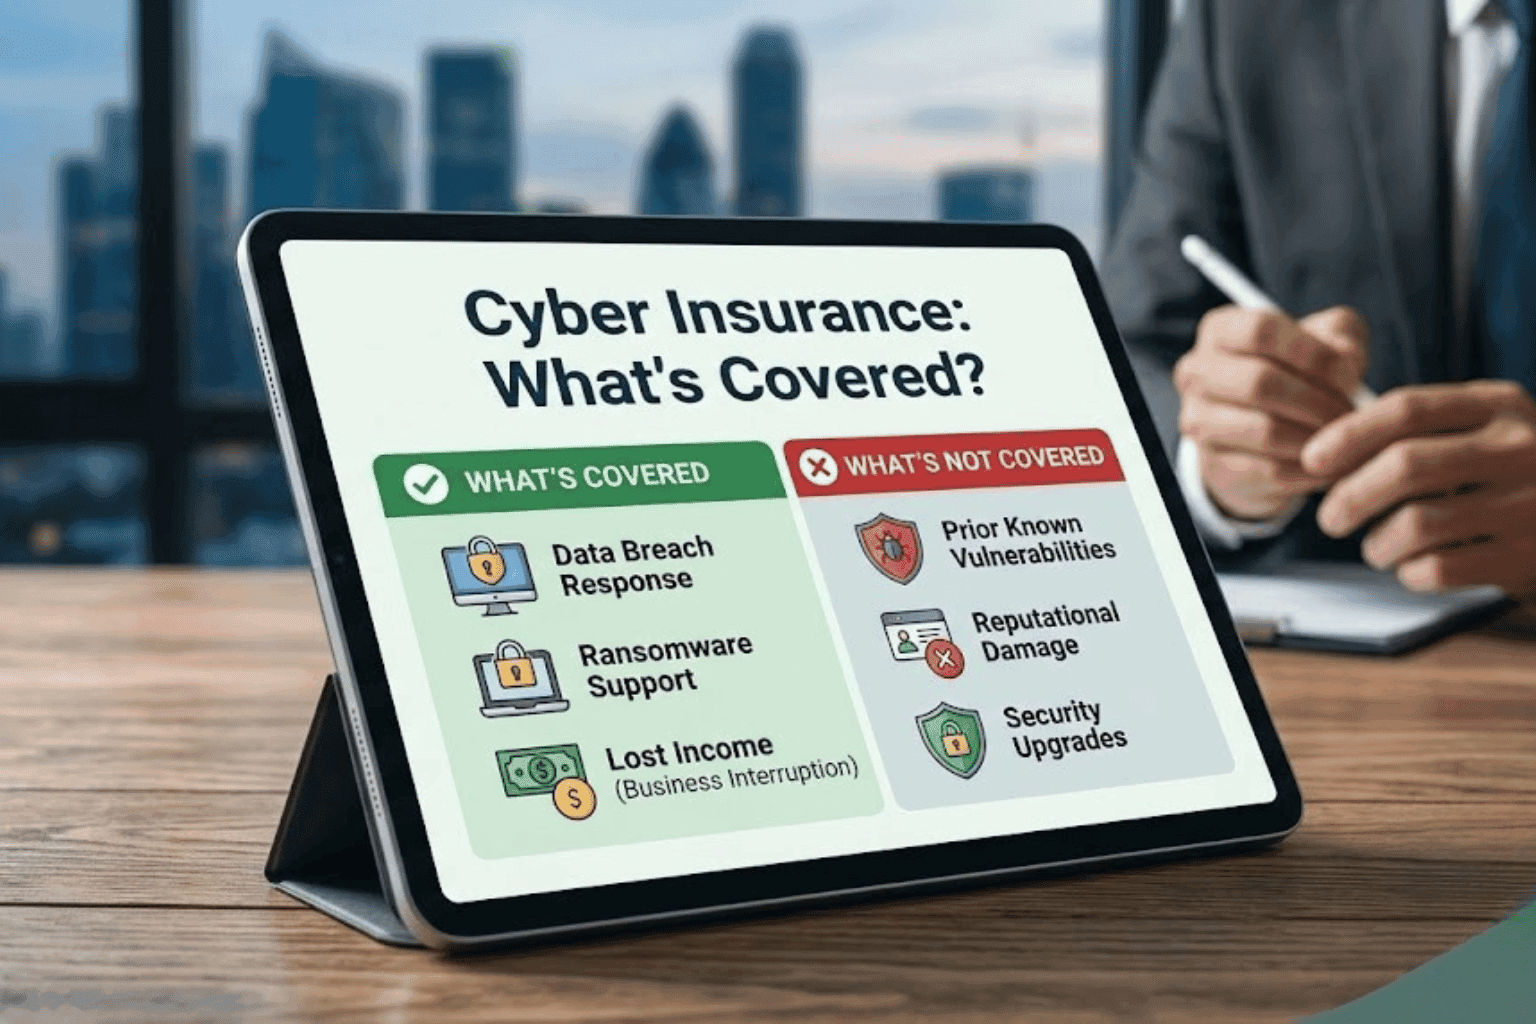
What Does Cyber Insurance Cover (and Not Cover)? Full Guide

How Much Is ATV Insurance? Average Costs and Factors
Your Tools Were Stolen Off the Truck. Which Policy Actually Pays?

What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!
Your Tools Were Stolen Off the Truck. Which Policy Actually Pays?
General liability covers other people's property. Commercial auto pays for the broken window, not what was inside. Here is the policy that actually replaces your tools.
Your Tools Were Stolen Off the Truck. Which Policy Actually Pays?
General liability covers other people's property. Commercial auto pays for the broken window, not what was inside. Here is the policy that actually replaces your tools.
Your Tools Were Stolen Off the Truck. Which Policy Actually Pays?
General liability covers other people's property. Commercial auto pays for the broken window, not what was inside. Here is the policy that actually replaces your tools.
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Not sure what does cyber insurance cover? See exactly what's included what's excluded, and whether your Texas business needs a policy.
How Much Is ATV Insurance? Average Costs and Factors
Learn how much ATV insurance costs, from liability to full coverage, plus the factors that affect your premium and ways to save. Visit now!