Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
BOP or General Liability? And Do You Need Either With No Employees?
BOP or General Liability? And Do You Need Either With No Employees?
BOP or General Liability? And Do You Need Either With No Employees?
BOP or General Liability? And Do You Need Either With No Employees?
BOP or General Liability? And Do You Need Either With No Employees?
Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
Ask three agents to quote the same Houston business and you can get back a general liability quote, a business owners policy quote, and a package with a third name entirely. Laid side by side they look like three competing options at three different prices.
They are not competing options. One of them contains the other, and once you can see the structure the decision takes about two minutes.
Short answer: General liability is a single coverage. A business owners policy, usually called a BOP, is a package that contains general liability and bundles it with coverage for your own property and, in most forms, business interruption. So the real question is never which one, it is whether you also need the property side. And on the second question: no. Having no employees removes nothing, because general liability exists for harm to other people. What changes when you hire is workers compensation, and that is a separate policy your general liability will never fill.
Key Takeaways
A BOP contains general liability. They sit on different levels, which is why quoting them against each other produces nonsense.
The deciding question is property and income, not headcount. If losing your space would stop your revenue, you want the package.
Employees were never in the general liability equation. It covers customers, clients, landlords and passersby. A solo operator has the same third party exposure as a crew of six.
The Texas Department of Insurance states the workers compensation exclusion outright. A CGL policy is not intended to provide it and the exclusion prohibits it.
Workers compensation is optional for most private Texas employers, which is genuinely unusual, and "optional" is not the same as "covered elsewhere."
Not every business qualifies for a BOP. Carriers set eligibility by type, size, revenue and location, and general liability plus separate property coverage gets to the same place.
Why the question gets confusing in the first place
Because the two things are not on the same level, and they get presented as though they were.
General liability is one coverage that answers one question: what happens when your business harms somebody else or their property. A BOP is a container. It holds that same general liability coverage and adds others alongside it. Comparing them is a little like comparing an engine to a car.
Once you see that, the decision is no longer "which product" but "how much of the container do I need."
What general liability actually covers
The Texas Department of Insurance describes commercial general liability as protecting business owners against claims for bodily injury, property damage, and personal and advertising injury, that last category covering things like slander and false advertising.
It arrives in two halves. Premises and operations responds to what happens at your location or while you are performing work. Products and completed operations responds after you have finished and left.
In practice:
A customer slips in your shop and breaks a wrist.
You are working in a client's home and put a ladder through their window.
A fixture you installed six months ago fails and damages the ceiling below it.
A competitor claims something you published about them was false.
Every one of those is harm to somebody else. That word is the whole article, and it comes back shortly. For the long form version of what sits inside the coverage, we wrote a complete breakdown of general liability for business.
What a BOP adds on top
Coverage | General liability alone | Business owners policy |
|---|---|---|
Bodily injury to others | Yes | Yes |
Damage to other people's property | Yes | Yes |
Personal and advertising injury | Yes | Yes |
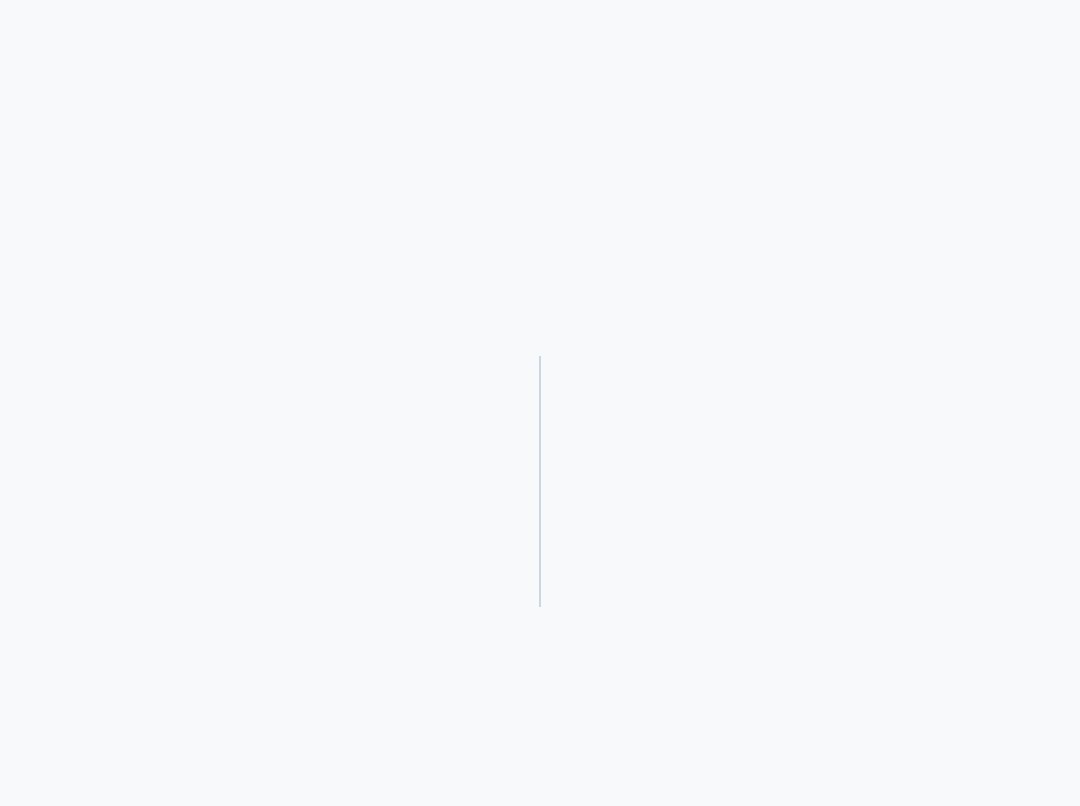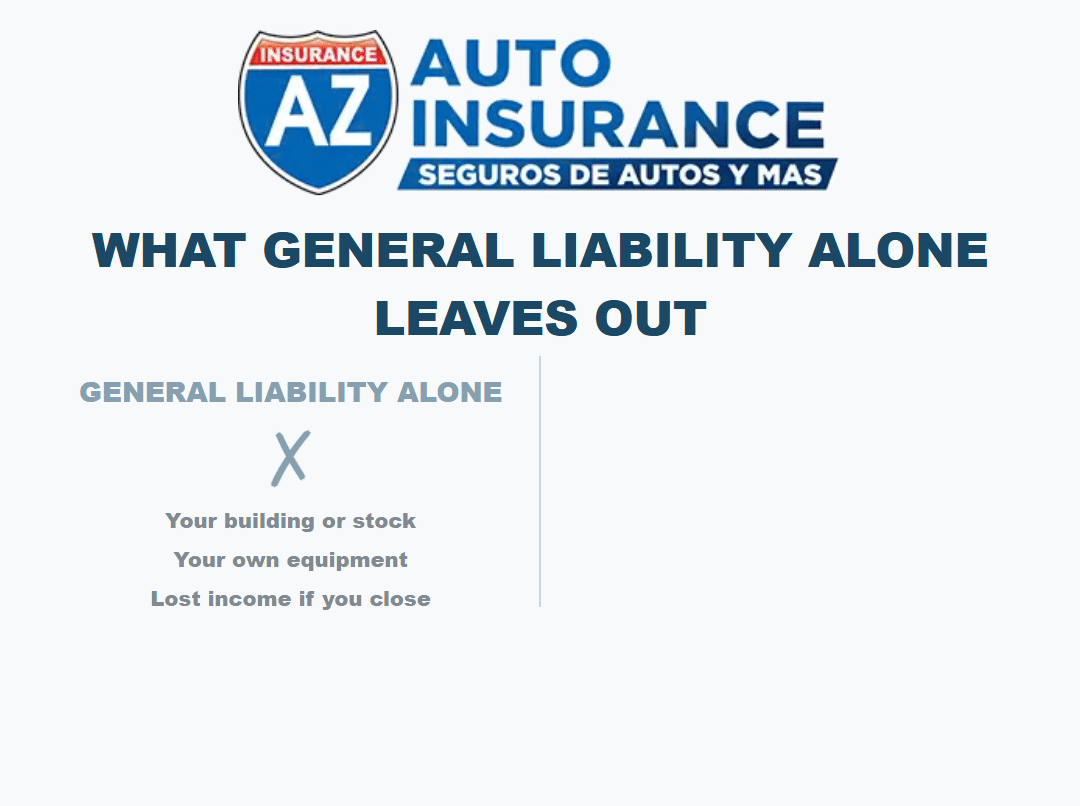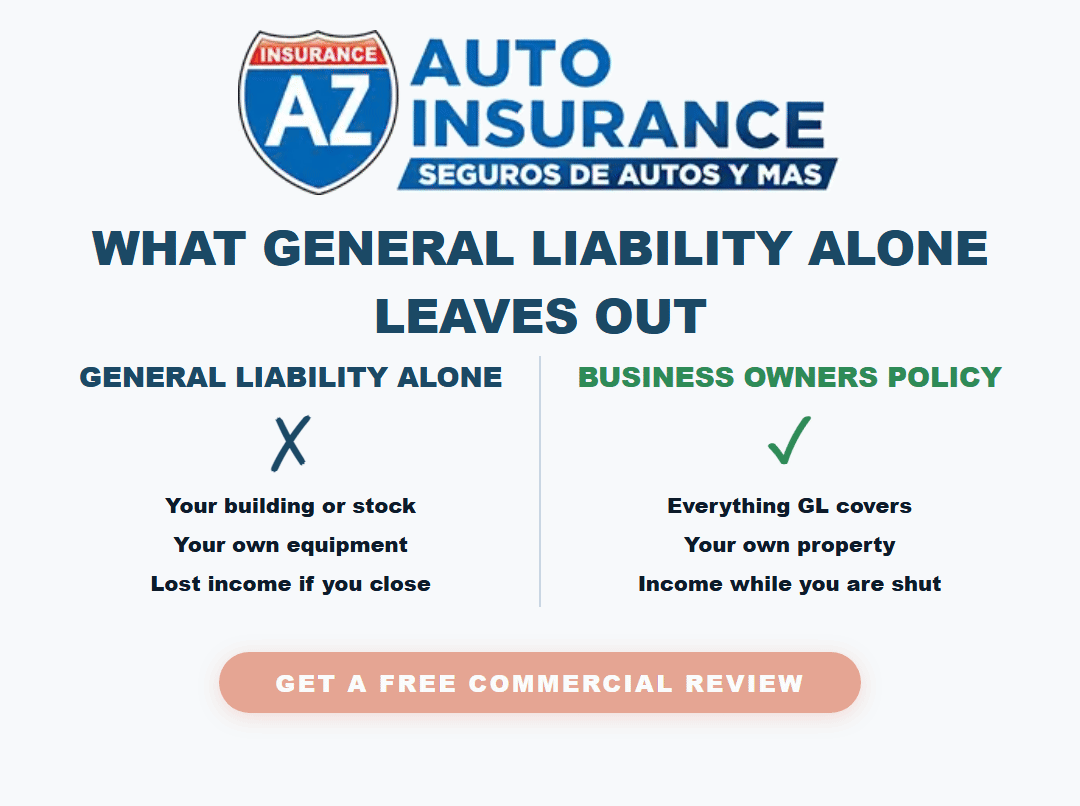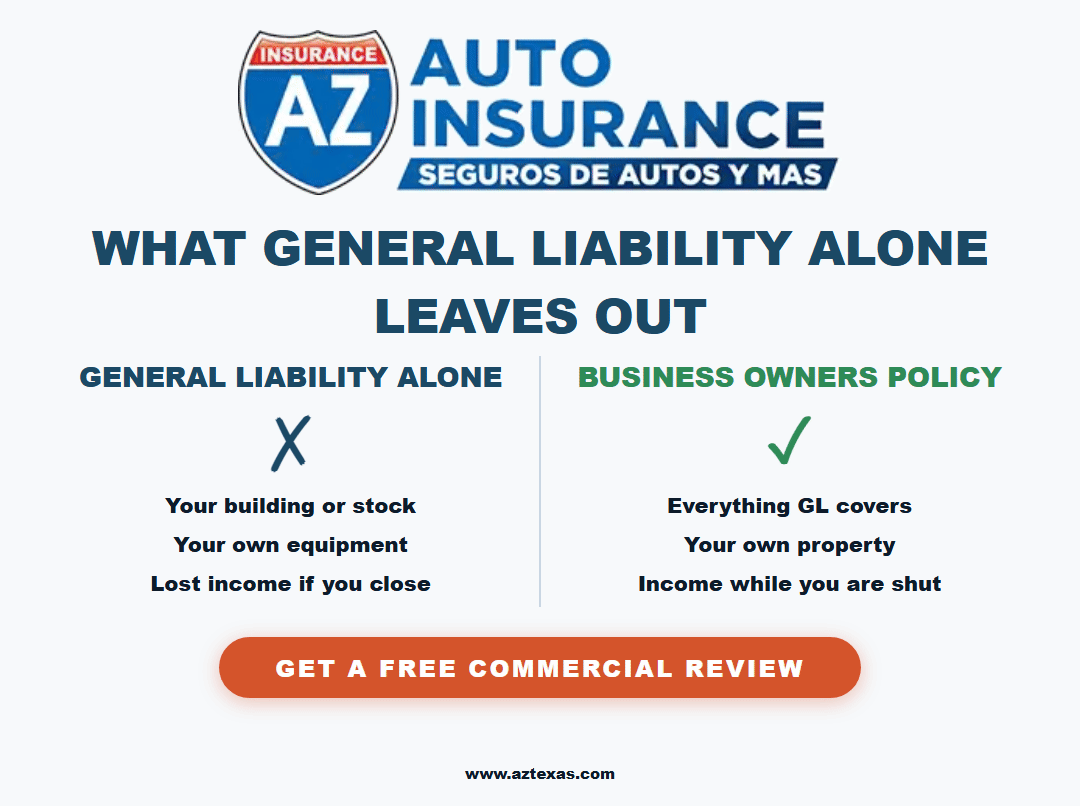
Your own building, stock, equipment, fixtures | No | Yes |
Leasehold improvements you paid for | No | Usually |
Income while you cannot trade | No | Usually |
Your employees' injuries | No | No |
Your vehicles | No | No |
The third row from the bottom is the one people underestimate. If a fire shuts your shop for two months, general liability does nothing at all, because nobody else was harmed. Business interruption is what pays the rent and replaces the income while the doors are closed.
Packages exist because bundling is normally cheaper than assembling the pieces separately, and because they close the specific gap where a business is well defended against being sued and has nothing when its own building or stock burns. Our explainer on business personal property coverage covers what the property half is actually counting, and the BOP itself gets its own walkthrough.
Which one do you actually need
The question that decides it is this: do you have property and income to protect, or only liability exposure?
Your situation | Usually the right shape |
|---|---|
Shop, salon, clinic, restaurant, office with stock and fit out | BOP |
Losing access to your space would stop your income | BOP |
Consultant working from home, few physical assets | Standalone general liability |
Contractor whose main assets are tools and a vehicle | General liability, with tools and vehicle insured separately |
Declined for a BOP because of trade or revenue | General liability plus separate property coverage |
That last row is real and it is not a failure. BOPs carry eligibility rules set by business type, size, revenue and location. Plenty of Houston trades get declined and end up with general liability alongside a property policy, which reaches the same destination by a different road.
A contractor's case is worth pulling out on its own, because tools are usually the biggest asset and a BOP is often the wrong container for them. Tools travelling to and from a job site normally belong on an inland marine or tools and equipment policy rather than on property coverage written for a fixed location. It is the most common gap we find on solo operators, and it sits next to the ones we mapped for landscaping and lawn care businesses and for cleaning companies.
Get a free commercial insurance review or call (281) 833-6755. Hablamos Español.
"It is just me." Do I still need this?
Yes, and the reason is that word from earlier.
General liability responds to harm suffered by other people. Customers, clients, tenants, passersby, the homeowner whose floor you damaged, the landlord whose building you work inside. Employees were never on that list.
So having no employees removes nothing from your general liability exposure. A solo handyman can put a foot through a kitchen ceiling exactly as easily as a crew of six can. If anything the solo operator carries it more personally, because there is no larger balance sheet standing behind the claim, and for a sole proprietor the line between business assets and personal ones is thin to begin with.
There is also a reason that has nothing to do with risk. If you subcontract, work for property managers, hold a city license or lease commercial space, you will be asked for a certificate. The general contractor does not care how many people you employ. They care whether the paper satisfies their contract, and they check it before they check anything else. We wrote about how fast that can be turned around in our piece on same day certificates of insurance, and about the wording they will ask for in certificate holder versus additional insured.
So yes, we write solo operators, sole proprietors and single member businesses, and they are a large share of the contractors on our books. The same is true if you hire help as 1099 contractors, which carries its own wrinkle worth reading before your next audit.
The moment you hire, a different policy starts
Here is where the two questions in this article finally meet.
When you take on an employee, the exposure you just added is not a general liability exposure. It is a workers compensation exposure, and it lives in a separate policy.
In Texas, workers compensation is optional for most private employers. The Texas Department of Insurance is clear that private employers may choose to carry it and that it is not required in most cases. Texas really is the outlier here.
Do not read "optional" as "covered somewhere else." The Texas Department of Insurance states it directly: CGL policies are not intended to provide coverage for workers compensation or employer's liability, and the exclusion prohibits such coverage. That is explicit. Your general liability, and the general liability sitting inside your BOP, will not answer for your own injured employee.
Going without it carries consequences past the injury. Carrying comp protects you from most lawsuits by injured employees. Without it you are a non subscriber: you can be sued directly, and you pick up reporting duties, including notifying the state that you have no coverage and reporting work related injuries involving more than one day of lost time along with all work related illnesses and deaths. We went through that trade in detail in the Texas non subscriber rules, and the straightforward version of the coverage itself is in workers compensation insurance.
One specific caution, because these are sold hard: Texas law does not treat alternative plans, or coverage bought from unlicensed insurance companies, as workers compensation. Buy one of those and you lose the lawsuit protection you thought you were paying for.
What neither one covers
A short list, so none of it is a surprise later.
Your vehicles. That is commercial auto. A personal auto policy excludes business use and the exclusion tends to be all or nothing.
Your employees' injuries. Workers compensation, as above.
Your own tools and equipment, unless you carry property coverage that reaches them or a dedicated tools and equipment policy.
Professional mistakes, meaning bad advice or a design error rather than physical damage. That is professional liability, sometimes called errors and omissions.
Pollution events. The Texas Department of Insurance describes the pollution exclusion as eliminating coverage for injuries or damages to a third party resulting from a pollution event arising from your business operations.
Redoing your own defective work. The repair is excluded; the damage it caused to other property often is not, which we untangled in does general liability cover faulty workmanship.
None of these are failures of the policy. They are simply other policies. The only real mistake is assuming one contract is doing all six jobs.
A note on limits, which is not the same as coverage
Worth separating out, because it costs business owners as much as any exclusion does.
A claim that exceeds your limit is not a denied claim. It is a covered claim that ran out. A $500,000 limit against a $900,000 judgment pays $500,000 and leaves the rest with you. Contracts increasingly demand more than a base policy carries, which is the usual reason a commercial umbrella gets added on top rather than buying a bigger primary.
And separately from limits: a policy that is perfectly valid can still end. What can and cannot cancel a Texas general liability policy, including the five permitted reasons after day 60 and the surplus lines carve out that catches a lot of contractors, is its own subject and we covered it in what can actually cancel or void your general liability policy in Texas.
Frequently asked questions
Q: Is a BOP the same as general liability?
No. A BOP is a package that contains general liability and adds coverage for your own property and usually business interruption. General liability on its own covers harm to other people and their property and does nothing for your own building, stock or lost income.
Q: Do I need general liability if I have no employees?
Yes. General liability responds to harm suffered by other people: customers, clients, landlords, passersby. Employees are not part of that exposure and never were. A solo operator has the same third party risk as a crew, and will still be asked for a certificate by any general contractor, property manager or landlord.
Q: Is a BOP cheaper than buying the coverages separately?
Usually, which is much of the point of bundling. It is not automatic, and it depends on whether you qualify for a BOP at all. Carriers set eligibility by business type, size, revenue and location.
Q: Does my general liability cover my employee if they get hurt?
No. The Texas Department of Insurance states that CGL policies are not intended to provide workers compensation or employer's liability coverage and that the exclusion prohibits it. Injured employees are a workers compensation question, or a non subscriber question if you carry none.
Q: Is workers compensation required in Texas?
Not for most private employers, which makes Texas unusual. Going without makes you a non subscriber, which means you lose the lawsuit protection comp provides, you can be sued directly by an injured worker, and you take on state reporting duties.
Q: My tools are my main asset. Does a BOP cover them?
Often not in the way you need. BOP property coverage is written around a fixed location, and tools that travel to and from job sites usually belong on an inland marine or tools and equipment policy. This is the most common gap we find on solo contractors.
Q: What if I get declined for a BOP?
It is common and it is not a problem. You buy general liability and add property coverage alongside it. Same protection, assembled differently. Call our business line at (281) 833-6755 and we will tell you which route your trade actually qualifies for.
Q: Does a certificate of insurance prove I have a BOP rather than general liability?
Not usefully. A certificate confirms that coverage existed on a given date. It does not list your exclusions, your endorsements or the structure of the package, which is why a general contractor asking for specific wording will usually want more than the certificate itself.
Related Articles
Why AZ Insurance Stands Apart
Most quotes for a small Houston business start with a price and work backwards. We start with what you actually do on a Tuesday, because that is what decides whether you need a container or a single coverage, and whether your tools are sitting outside every policy you own. We are independent, we have been doing this from Houston since 2003, and we compare multiple insurance companies rather than defending one carrier's form.
Tell us what the business does day to day and we will tell you which structure fits: general liability on its own, a BOP, or general liability with property alongside it. If you have a contract in hand, send us the insurance section and we will tell you whether what you carry actually satisfies it. And if you are already covered properly, we will say so, which happens more often than you would expect.
Request a free commercial insurance review or call our business line at (281) 833-6755.
Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
Ask three agents to quote the same Houston business and you can get back a general liability quote, a business owners policy quote, and a package with a third name entirely. Laid side by side they look like three competing options at three different prices.
They are not competing options. One of them contains the other, and once you can see the structure the decision takes about two minutes.
Short answer: General liability is a single coverage. A business owners policy, usually called a BOP, is a package that contains general liability and bundles it with coverage for your own property and, in most forms, business interruption. So the real question is never which one, it is whether you also need the property side. And on the second question: no. Having no employees removes nothing, because general liability exists for harm to other people. What changes when you hire is workers compensation, and that is a separate policy your general liability will never fill.
Key Takeaways
A BOP contains general liability. They sit on different levels, which is why quoting them against each other produces nonsense.
The deciding question is property and income, not headcount. If losing your space would stop your revenue, you want the package.
Employees were never in the general liability equation. It covers customers, clients, landlords and passersby. A solo operator has the same third party exposure as a crew of six.
The Texas Department of Insurance states the workers compensation exclusion outright. A CGL policy is not intended to provide it and the exclusion prohibits it.
Workers compensation is optional for most private Texas employers, which is genuinely unusual, and "optional" is not the same as "covered elsewhere."
Not every business qualifies for a BOP. Carriers set eligibility by type, size, revenue and location, and general liability plus separate property coverage gets to the same place.
Why the question gets confusing in the first place
Because the two things are not on the same level, and they get presented as though they were.
General liability is one coverage that answers one question: what happens when your business harms somebody else or their property. A BOP is a container. It holds that same general liability coverage and adds others alongside it. Comparing them is a little like comparing an engine to a car.
Once you see that, the decision is no longer "which product" but "how much of the container do I need."
What general liability actually covers
The Texas Department of Insurance describes commercial general liability as protecting business owners against claims for bodily injury, property damage, and personal and advertising injury, that last category covering things like slander and false advertising.
It arrives in two halves. Premises and operations responds to what happens at your location or while you are performing work. Products and completed operations responds after you have finished and left.
In practice:
A customer slips in your shop and breaks a wrist.
You are working in a client's home and put a ladder through their window.
A fixture you installed six months ago fails and damages the ceiling below it.
A competitor claims something you published about them was false.
Every one of those is harm to somebody else. That word is the whole article, and it comes back shortly. For the long form version of what sits inside the coverage, we wrote a complete breakdown of general liability for business.
What a BOP adds on top
Coverage | General liability alone | Business owners policy |
|---|---|---|
Bodily injury to others | Yes | Yes |
Damage to other people's property | Yes | Yes |
Personal and advertising injury | Yes | Yes |
Your own building, stock, equipment, fixtures | No | Yes |
Leasehold improvements you paid for | No | Usually |
Income while you cannot trade | No | Usually |
Your employees' injuries | No | No |
Your vehicles | No | No |
The third row from the bottom is the one people underestimate. If a fire shuts your shop for two months, general liability does nothing at all, because nobody else was harmed. Business interruption is what pays the rent and replaces the income while the doors are closed.
Packages exist because bundling is normally cheaper than assembling the pieces separately, and because they close the specific gap where a business is well defended against being sued and has nothing when its own building or stock burns. Our explainer on business personal property coverage covers what the property half is actually counting, and the BOP itself gets its own walkthrough.
Which one do you actually need
The question that decides it is this: do you have property and income to protect, or only liability exposure?
Your situation | Usually the right shape |
|---|---|
Shop, salon, clinic, restaurant, office with stock and fit out | BOP |
Losing access to your space would stop your income | BOP |
Consultant working from home, few physical assets | Standalone general liability |
Contractor whose main assets are tools and a vehicle | General liability, with tools and vehicle insured separately |
Declined for a BOP because of trade or revenue | General liability plus separate property coverage |
That last row is real and it is not a failure. BOPs carry eligibility rules set by business type, size, revenue and location. Plenty of Houston trades get declined and end up with general liability alongside a property policy, which reaches the same destination by a different road.
A contractor's case is worth pulling out on its own, because tools are usually the biggest asset and a BOP is often the wrong container for them. Tools travelling to and from a job site normally belong on an inland marine or tools and equipment policy rather than on property coverage written for a fixed location. It is the most common gap we find on solo operators, and it sits next to the ones we mapped for landscaping and lawn care businesses and for cleaning companies.
Get a free commercial insurance review or call (281) 833-6755. Hablamos Español.
"It is just me." Do I still need this?
Yes, and the reason is that word from earlier.
General liability responds to harm suffered by other people. Customers, clients, tenants, passersby, the homeowner whose floor you damaged, the landlord whose building you work inside. Employees were never on that list.
So having no employees removes nothing from your general liability exposure. A solo handyman can put a foot through a kitchen ceiling exactly as easily as a crew of six can. If anything the solo operator carries it more personally, because there is no larger balance sheet standing behind the claim, and for a sole proprietor the line between business assets and personal ones is thin to begin with.
There is also a reason that has nothing to do with risk. If you subcontract, work for property managers, hold a city license or lease commercial space, you will be asked for a certificate. The general contractor does not care how many people you employ. They care whether the paper satisfies their contract, and they check it before they check anything else. We wrote about how fast that can be turned around in our piece on same day certificates of insurance, and about the wording they will ask for in certificate holder versus additional insured.
So yes, we write solo operators, sole proprietors and single member businesses, and they are a large share of the contractors on our books. The same is true if you hire help as 1099 contractors, which carries its own wrinkle worth reading before your next audit.
The moment you hire, a different policy starts
Here is where the two questions in this article finally meet.
When you take on an employee, the exposure you just added is not a general liability exposure. It is a workers compensation exposure, and it lives in a separate policy.
In Texas, workers compensation is optional for most private employers. The Texas Department of Insurance is clear that private employers may choose to carry it and that it is not required in most cases. Texas really is the outlier here.
Do not read "optional" as "covered somewhere else." The Texas Department of Insurance states it directly: CGL policies are not intended to provide coverage for workers compensation or employer's liability, and the exclusion prohibits such coverage. That is explicit. Your general liability, and the general liability sitting inside your BOP, will not answer for your own injured employee.
Going without it carries consequences past the injury. Carrying comp protects you from most lawsuits by injured employees. Without it you are a non subscriber: you can be sued directly, and you pick up reporting duties, including notifying the state that you have no coverage and reporting work related injuries involving more than one day of lost time along with all work related illnesses and deaths. We went through that trade in detail in the Texas non subscriber rules, and the straightforward version of the coverage itself is in workers compensation insurance.
One specific caution, because these are sold hard: Texas law does not treat alternative plans, or coverage bought from unlicensed insurance companies, as workers compensation. Buy one of those and you lose the lawsuit protection you thought you were paying for.
What neither one covers
A short list, so none of it is a surprise later.
Your vehicles. That is commercial auto. A personal auto policy excludes business use and the exclusion tends to be all or nothing.
Your employees' injuries. Workers compensation, as above.
Your own tools and equipment, unless you carry property coverage that reaches them or a dedicated tools and equipment policy.
Professional mistakes, meaning bad advice or a design error rather than physical damage. That is professional liability, sometimes called errors and omissions.
Pollution events. The Texas Department of Insurance describes the pollution exclusion as eliminating coverage for injuries or damages to a third party resulting from a pollution event arising from your business operations.
Redoing your own defective work. The repair is excluded; the damage it caused to other property often is not, which we untangled in does general liability cover faulty workmanship.
None of these are failures of the policy. They are simply other policies. The only real mistake is assuming one contract is doing all six jobs.
A note on limits, which is not the same as coverage
Worth separating out, because it costs business owners as much as any exclusion does.
A claim that exceeds your limit is not a denied claim. It is a covered claim that ran out. A $500,000 limit against a $900,000 judgment pays $500,000 and leaves the rest with you. Contracts increasingly demand more than a base policy carries, which is the usual reason a commercial umbrella gets added on top rather than buying a bigger primary.
And separately from limits: a policy that is perfectly valid can still end. What can and cannot cancel a Texas general liability policy, including the five permitted reasons after day 60 and the surplus lines carve out that catches a lot of contractors, is its own subject and we covered it in what can actually cancel or void your general liability policy in Texas.
Frequently asked questions
Q: Is a BOP the same as general liability?
No. A BOP is a package that contains general liability and adds coverage for your own property and usually business interruption. General liability on its own covers harm to other people and their property and does nothing for your own building, stock or lost income.
Q: Do I need general liability if I have no employees?
Yes. General liability responds to harm suffered by other people: customers, clients, landlords, passersby. Employees are not part of that exposure and never were. A solo operator has the same third party risk as a crew, and will still be asked for a certificate by any general contractor, property manager or landlord.
Q: Is a BOP cheaper than buying the coverages separately?
Usually, which is much of the point of bundling. It is not automatic, and it depends on whether you qualify for a BOP at all. Carriers set eligibility by business type, size, revenue and location.
Q: Does my general liability cover my employee if they get hurt?
No. The Texas Department of Insurance states that CGL policies are not intended to provide workers compensation or employer's liability coverage and that the exclusion prohibits it. Injured employees are a workers compensation question, or a non subscriber question if you carry none.
Q: Is workers compensation required in Texas?
Not for most private employers, which makes Texas unusual. Going without makes you a non subscriber, which means you lose the lawsuit protection comp provides, you can be sued directly by an injured worker, and you take on state reporting duties.
Q: My tools are my main asset. Does a BOP cover them?
Often not in the way you need. BOP property coverage is written around a fixed location, and tools that travel to and from job sites usually belong on an inland marine or tools and equipment policy. This is the most common gap we find on solo contractors.
Q: What if I get declined for a BOP?
It is common and it is not a problem. You buy general liability and add property coverage alongside it. Same protection, assembled differently. Call our business line at (281) 833-6755 and we will tell you which route your trade actually qualifies for.
Q: Does a certificate of insurance prove I have a BOP rather than general liability?
Not usefully. A certificate confirms that coverage existed on a given date. It does not list your exclusions, your endorsements or the structure of the package, which is why a general contractor asking for specific wording will usually want more than the certificate itself.
Related Articles
Why AZ Insurance Stands Apart
Most quotes for a small Houston business start with a price and work backwards. We start with what you actually do on a Tuesday, because that is what decides whether you need a container or a single coverage, and whether your tools are sitting outside every policy you own. We are independent, we have been doing this from Houston since 2003, and we compare multiple insurance companies rather than defending one carrier's form.
Tell us what the business does day to day and we will tell you which structure fits: general liability on its own, a BOP, or general liability with property alongside it. If you have a contract in hand, send us the insurance section and we will tell you whether what you carry actually satisfies it. And if you are already covered properly, we will say so, which happens more often than you would expect.
Request a free commercial insurance review or call our business line at (281) 833-6755.
Latest Blogs

How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)

What Can Actually Cancel or Void Your General Liability Policy in Texas
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Average Hazard Insurance Cost: What Homeowners Can Expect

What Is Home Hazard Insurance and What Does It Cover?

Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Average Hazard Insurance Cost: What Homeowners Can Expect
Curious about the average hazard insurance cost? See what Texas homeowners actually pay, what drives the price, and how to get a lower quote.
Average Hazard Insurance Cost: What Homeowners Can Expect
Curious about the average hazard insurance cost? See what Texas homeowners actually pay, what drives the price, and how to get a lower quote.
Average Hazard Insurance Cost: What Homeowners Can Expect
Curious about the average hazard insurance cost? See what Texas homeowners actually pay, what drives the price, and how to get a lower quote.
What Is Home Hazard Insurance and What Does It Cover?
Learn what home hazard insurance is, what it covers in TX, & what's left out. See how AZ Insurance Agency helps Houston homeowners close the gaps.
What Is Home Hazard Insurance and What Does It Cover?
Learn what home hazard insurance is, what it covers in TX, & what's left out. See how AZ Insurance Agency helps Houston homeowners close the gaps.
What Is Home Hazard Insurance and What Does It Cover?
Learn what home hazard insurance is, what it covers in TX, & what's left out. See how AZ Insurance Agency helps Houston homeowners close the gaps.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Average Hazard Insurance Cost: What Homeowners Can Expect
Curious about the average hazard insurance cost? See what Texas homeowners actually pay, what drives the price, and how to get a lower quote.