Quick support from trusted insurance professionals Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense

Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
A general contractor in Katy requires every sub on the job to name him as additional insured. The certificates come in, each one listing him in the box at the lower left, and he files them. Two years after the job closes, a tenant is injured by a stair rail one of those subs installed. The general contractor is named in the suit, forwards the certificate to the sub's carrier, and receives a letter explaining that he was a certificate holder, not an additional insured, and that no coverage is owed.
He collected the right paperwork for two years and it bought him nothing. This is one of the most expensive misunderstandings in Texas construction, and it is entirely avoidable. If you are reviewing contracts right now, our business insurance team will read the actual endorsement rather than the certificate.
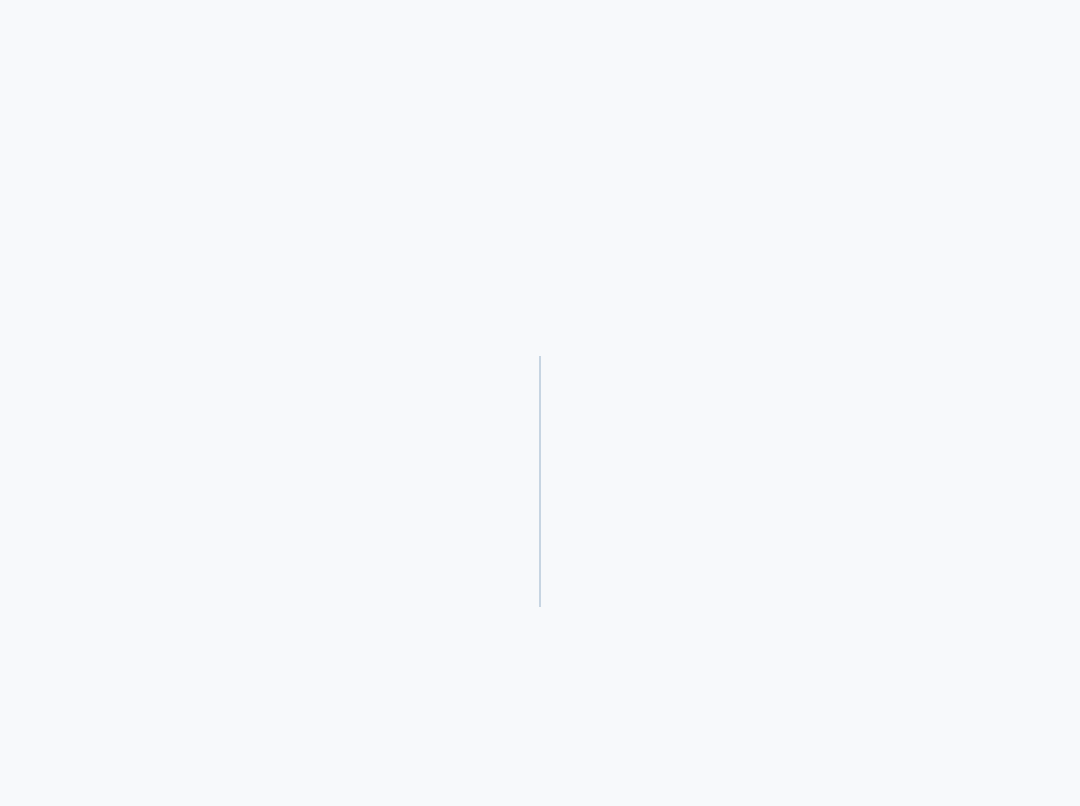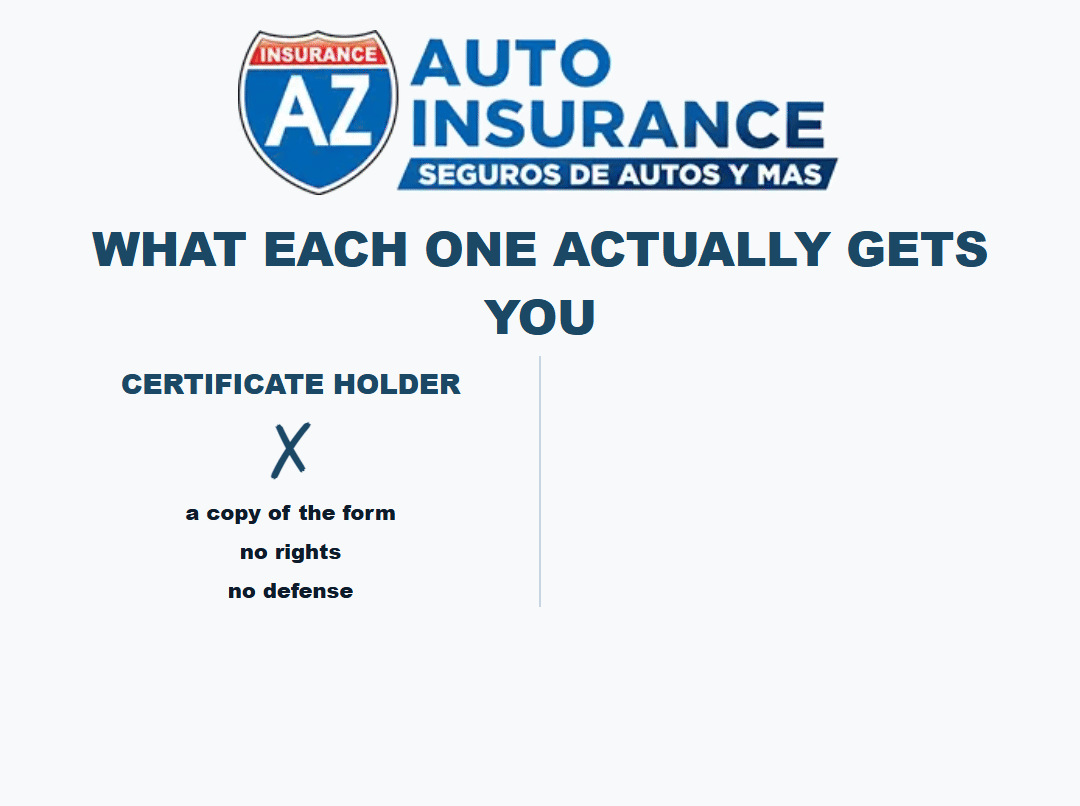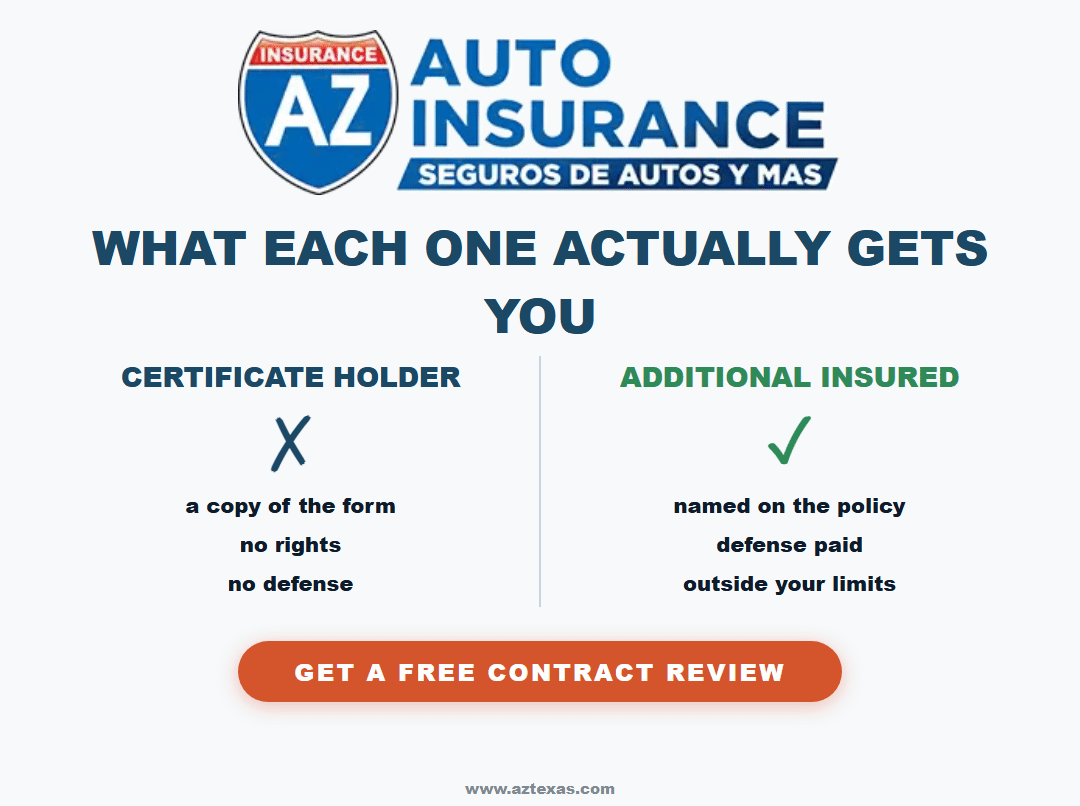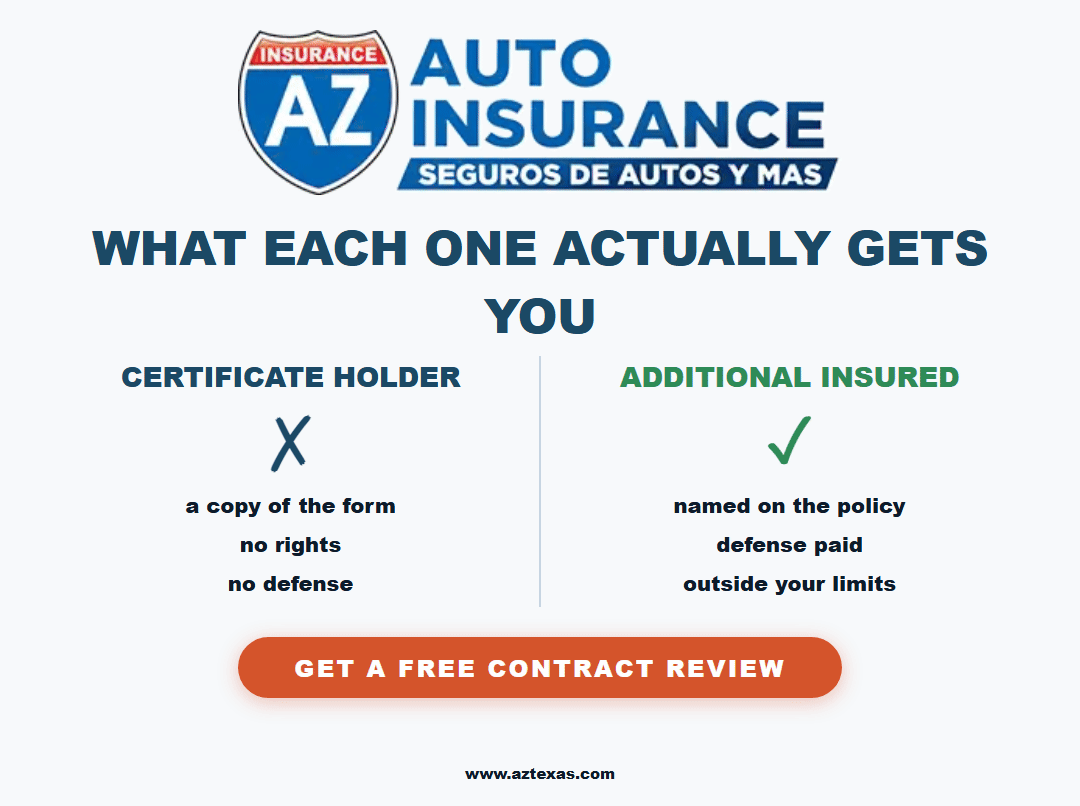
Short answer: A certificate holder is simply the person who received a copy of the certificate. It grants no rights and no coverage. An additional insured has been added to the policy itself by endorsement and can claim a defense and indemnity under someone else's coverage. The ACORD certificate says so in its own text: it is issued as a matter of information only and confers no rights upon the certificate holder.
Key Takeaways
A certificate is evidence, not coverage. The ACORD 25 form states on its face that it confers no rights upon the certificate holder.
Additional insured status comes only from an endorsement attached to the policy, identified by form number.
CG 20 10 covers ongoing operations. CG 20 37 covers products and completed operations. Requiring only the first leaves you exposed after the job is finished.
Completed operations claims are the ones that arrive late, often years after the work, which is exactly when the missing form is discovered.
Primary and non contributory is a separate requirement from additional insured status, and without it the other carrier can chase your policy for contribution.
Additional insured status expires with the policy period, so it has to be re confirmed at every renewal, not collected once and filed.
What a certificate of insurance actually proves
A certificate of insurance is a snapshot. It says that on the day it was issued, a policy existed with certain limits and certain dates. That is the entire scope of what it establishes.
The certificate form itself is unusually candid about this. The standard ACORD 25 carries language stating that it is issued as a matter of information only, that it confers no rights upon the certificate holder, and that it does not amend, extend or alter the coverage afforded by the policies listed.
What a certificate does establish:
That a policy was in force on the issue date
The carrier, the policy number and the policy period
The limits shown for each line of coverage
Whether boxes for additional insured or subrogation waiver have been checked
Who requested the document
What a certificate does not establish:
That you have any rights under the policy
Which exclusions or endorsements apply
That any checked box is backed by an actual endorsement form
That the policy is still in force today
That the policy will not be changed or cancelled tomorrow
That fourth point deserves emphasis. A checked box on a certificate is a description written by whoever prepared it. It is not the endorsement, and it is not binding on the insurer. Our full guide to the Texas certificate of insurance covers how to read one properly and how quickly a real one can be issued.
What additional insured status actually gives you
Additional insured status changes the policy itself. Someone else's insurer now owes you obligations directly, and the most valuable of them is usually the defense.
Concretely, it delivers:
A defense paid by the other party's insurer when you are named in a covered suit
Defense costs treated as supplementary payments, which generally sit outside the policy limits
Indemnity for covered judgments and settlements within the scope of the endorsement
Access to limits that are not your own, preserving your loss history
A direct relationship with that carrier rather than a request routed through the named insured
That second point is the one contractors underestimate. Defense costs on a construction claim routinely reach six figures before fault is ever determined. Having those costs paid from outside your limits, by a carrier that is not yours, is frequently worth more than the indemnity itself. The same structural benefit appears in the commercial umbrella discussion, where contract required limits are the usual driver, and a commercial umbrella quote is often cheaper than raising the underlying limit.
Additional insured status also has boundaries. It generally covers liability arising out of the named insured's work for you. It does not convert the other party's policy into blanket protection for everything your business does, and it does not cover your own independent negligence in most modern forms.
The endorsement forms, by number
This is the part of the conversation that separates contractors who get paid from contractors who get letters. Ask for the forms by number.
Form | What it covers | When it matters |
|---|---|---|
CG 20 10 | Ongoing operations, while the work is in progress | Injuries and damage during construction |
CG 20 37 | Products and completed operations, after the work is finished | Claims that surface months or years later |
CG 20 33 | Blanket version of ongoing operations, triggered by written contract | Automatic status without a scheduled name |
CG 20 38 | Blanket version reaching upstream parties, ongoing and completed | Tiered jobs where you are not in direct contract |
The practical rules that follow from this table:
Require CG 20 10 and CG 20 37 together, by number, in the contract. One without the other leaves half the timeline uncovered.
Understand that blanket forms depend on a written pre loss contract. No signed contract, no status.
Know that CG 20 33 reaches only parties who contract directly with the named insured, which can leave an upper tier general contractor out.
Ask for the endorsement pages themselves, not a certificate describing them.
Check the edition date, because newer editions narrow coverage to liability caused in whole or in part by the named insured.
Watch for proprietary forms. If the number is not a standard ISO form, request the wording and compare it.
Newer editions matter more than most people expect. Courts have restricted additional insured coverage to injury proximately caused by the named insured, which means the causation wording in the edition you receive can matter as much as the form number on the front.
Get a free contract and coverage review or call (281) 833-6755. Hablamos Español.
Primary and non contributory, and waiver of subrogation
These two clauses travel alongside additional insured status in almost every Texas construction contract, and they solve different problems. Neither is automatic.
Primary and non contributory means the other party's policy responds first and does not seek contribution from yours. Without it, both carriers can argue about sharing, your policy is drawn into a claim that was supposed to be someone else's, and your loss history absorbs it.
Waiver of subrogation means the insurer gives up its right to recover from you after paying a claim. Without it, the carrier can pay its insured and then pursue your business for the same money, which defeats the point of the arrangement entirely.
Checklist for both:
Confirm the primary and non contributory language appears in the Description of Operations box, and confirm an endorsement backs it
Confirm a waiver of subrogation endorsement is attached, not merely a checked box
Understand that many waivers require a written contract executed before the loss
Verify the waiver applies to the specific project or party named in your contract
Remember that both are separate endorsements, each with its own cost and each requiring its own request
How to actually verify status before a claim
The process below takes about fifteen minutes per subcontractor and prevents the scenario at the top of this article.
Ask for the certificate and the additional insured endorsement pages
Confirm the form numbers match what your contract requires
Confirm the edition dates and read the causation wording
Confirm your exact legal entity name appears, spelled correctly, on the schedule or covered by blanket wording
Confirm the policy period covers the entire term of your work, not merely the day the certificate was issued
Confirm products and completed operations coverage is included and carries a limit
Confirm the primary and non contributory and waiver of subrogation endorsements are attached
Diary every renewal date and request fresh documents at each one
Store the endorsement pages for the full statutory period, not just the certificate
Escalate immediately if a sub cannot produce an endorsement, because that usually means it does not exist
A note on timing that trips up contractors: certificates are frequently requested the morning a job is due to start. We issue same day certificates from all of our fifteen Houston and DFW offices, but a certificate issued quickly is still only a certificate. The endorsement is a policy change and should be arranged before you sign, not on the morning you mobilize.
Who asks for what, by trade
The requirement varies by who you work for and what you do, and the pattern is fairly predictable.
Subcontractors on commercial jobs are usually asked for additional insured status on both forms plus primary and non contributory, which starts with a general liability quote written to the contract
General contractors are usually asked by owners and developers for the same package, and must collect it downstream
Landlords typically require additional insured status on the tenant's policy, which we cover in the commercial property guide
Cleaning and janitorial firms are usually asked by property managers, addressed in our cleaning company general liability guide
Landscapers working for HOAs and commercial properties face the same requirement, covered in the landscaping coverage gaps guide
Anyone using 1099 labor has a separate problem worth understanding, set out in 1099 contractors and general liability in Texas
If you are unsure whether your operation needs general liability at all, start with is general liability insurance required in Texas, then look at what general liability actually covers and the 2026 Houston cost guide. Sole operators should read the sole proprietor risk guide, and smaller firms bundling coverage should compare the business owners policy.
Frequently Asked Questions
Q: What is the difference between a certificate holder and an additional insured?
A certificate holder is the party who received a copy of the certificate of insurance. It grants no rights under the policy. An additional insured has been added to the policy by endorsement and can claim a defense and indemnity from that insurer. The ACORD certificate states in its own text that it confers no rights upon the certificate holder.
Q: Which endorsement forms should my contract require?
Require CG 20 10 for ongoing operations and CG 20 37 for products and completed operations, both by form number. If the parties sit in tiers, CG 20 38 reaches upstream parties where CG 20 33 may not. Always request the endorsement pages and confirm the edition dates.
Q: Does checking the additional insured box on a certificate create coverage?
No. The box is a description prepared by whoever issued the certificate. Only the endorsement attached to the policy creates the status. If the endorsement is absent, the box is simply wrong and the carrier is not bound by it.
Q: How long does additional insured status last?
It is tied to the policy period of the policy it was issued under. When that policy renews, the status has to be re established and new documentation requested. This is why collecting certificates once at the start of a multi year relationship is not sufficient.
Q: Is primary and non contributory included automatically?
No. It is a separate endorsement and a separate request. Without it, the other carrier can seek contribution from your policy, which pulls your coverage and your loss history into a claim that should have belonged entirely to someone else.
Q: What should I do if a subcontractor cannot produce the endorsement?
Treat it as a red flag and stop before the work starts. In most cases the endorsement was never purchased. Call our business line at (281) 833-6755 and we can usually tell within a few minutes whether the coverage being described actually exists.
Q: Can I be an additional insured on a policy that excludes the work I care about?
Yes, and this is a common trap. Additional insured status gives you rights under a policy, including all of that policy's exclusions. If the underlying coverage excludes the exposure, your status does not restore it. Start a free contract and policy review if a contract is relying on this.
Related Articles
What general liability insurance covers for a business, a complete breakdown
Commercial umbrella insurance and contract requirements in Texas
Why AZ Insurance Stands Apart
Anyone can email a certificate. Reading the contract that demanded it, identifying which endorsement forms it actually requires, and confirming those forms exist on the policy is a different job, and it is the one that protects you when a claim lands two years after the job closed. We have been doing it from Houston since 2003, we are independent, and we compare multiple insurance companies rather than defending a single carrier's forms.
Before you sign the next contract, send us the insurance requirements page. Request a free contract and coverage review or call our business line at (281) 833-6755, and we will tell you what you are actually required to carry, and whether what you hold today satisfies it.
Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
A general contractor in Katy requires every sub on the job to name him as additional insured. The certificates come in, each one listing him in the box at the lower left, and he files them. Two years after the job closes, a tenant is injured by a stair rail one of those subs installed. The general contractor is named in the suit, forwards the certificate to the sub's carrier, and receives a letter explaining that he was a certificate holder, not an additional insured, and that no coverage is owed.
He collected the right paperwork for two years and it bought him nothing. This is one of the most expensive misunderstandings in Texas construction, and it is entirely avoidable. If you are reviewing contracts right now, our business insurance team will read the actual endorsement rather than the certificate.
Short answer: A certificate holder is simply the person who received a copy of the certificate. It grants no rights and no coverage. An additional insured has been added to the policy itself by endorsement and can claim a defense and indemnity under someone else's coverage. The ACORD certificate says so in its own text: it is issued as a matter of information only and confers no rights upon the certificate holder.
Key Takeaways
A certificate is evidence, not coverage. The ACORD 25 form states on its face that it confers no rights upon the certificate holder.
Additional insured status comes only from an endorsement attached to the policy, identified by form number.
CG 20 10 covers ongoing operations. CG 20 37 covers products and completed operations. Requiring only the first leaves you exposed after the job is finished.
Completed operations claims are the ones that arrive late, often years after the work, which is exactly when the missing form is discovered.
Primary and non contributory is a separate requirement from additional insured status, and without it the other carrier can chase your policy for contribution.
Additional insured status expires with the policy period, so it has to be re confirmed at every renewal, not collected once and filed.
What a certificate of insurance actually proves
A certificate of insurance is a snapshot. It says that on the day it was issued, a policy existed with certain limits and certain dates. That is the entire scope of what it establishes.
The certificate form itself is unusually candid about this. The standard ACORD 25 carries language stating that it is issued as a matter of information only, that it confers no rights upon the certificate holder, and that it does not amend, extend or alter the coverage afforded by the policies listed.
What a certificate does establish:
That a policy was in force on the issue date
The carrier, the policy number and the policy period
The limits shown for each line of coverage
Whether boxes for additional insured or subrogation waiver have been checked
Who requested the document
What a certificate does not establish:
That you have any rights under the policy
Which exclusions or endorsements apply
That any checked box is backed by an actual endorsement form
That the policy is still in force today
That the policy will not be changed or cancelled tomorrow
That fourth point deserves emphasis. A checked box on a certificate is a description written by whoever prepared it. It is not the endorsement, and it is not binding on the insurer. Our full guide to the Texas certificate of insurance covers how to read one properly and how quickly a real one can be issued.
What additional insured status actually gives you
Additional insured status changes the policy itself. Someone else's insurer now owes you obligations directly, and the most valuable of them is usually the defense.
Concretely, it delivers:
A defense paid by the other party's insurer when you are named in a covered suit
Defense costs treated as supplementary payments, which generally sit outside the policy limits
Indemnity for covered judgments and settlements within the scope of the endorsement
Access to limits that are not your own, preserving your loss history
A direct relationship with that carrier rather than a request routed through the named insured
That second point is the one contractors underestimate. Defense costs on a construction claim routinely reach six figures before fault is ever determined. Having those costs paid from outside your limits, by a carrier that is not yours, is frequently worth more than the indemnity itself. The same structural benefit appears in the commercial umbrella discussion, where contract required limits are the usual driver, and a commercial umbrella quote is often cheaper than raising the underlying limit.
Additional insured status also has boundaries. It generally covers liability arising out of the named insured's work for you. It does not convert the other party's policy into blanket protection for everything your business does, and it does not cover your own independent negligence in most modern forms.
The endorsement forms, by number
This is the part of the conversation that separates contractors who get paid from contractors who get letters. Ask for the forms by number.
Form | What it covers | When it matters |
|---|---|---|
CG 20 10 | Ongoing operations, while the work is in progress | Injuries and damage during construction |
CG 20 37 | Products and completed operations, after the work is finished | Claims that surface months or years later |
CG 20 33 | Blanket version of ongoing operations, triggered by written contract | Automatic status without a scheduled name |
CG 20 38 | Blanket version reaching upstream parties, ongoing and completed | Tiered jobs where you are not in direct contract |
The practical rules that follow from this table:
Require CG 20 10 and CG 20 37 together, by number, in the contract. One without the other leaves half the timeline uncovered.
Understand that blanket forms depend on a written pre loss contract. No signed contract, no status.
Know that CG 20 33 reaches only parties who contract directly with the named insured, which can leave an upper tier general contractor out.
Ask for the endorsement pages themselves, not a certificate describing them.
Check the edition date, because newer editions narrow coverage to liability caused in whole or in part by the named insured.
Watch for proprietary forms. If the number is not a standard ISO form, request the wording and compare it.
Newer editions matter more than most people expect. Courts have restricted additional insured coverage to injury proximately caused by the named insured, which means the causation wording in the edition you receive can matter as much as the form number on the front.
Get a free contract and coverage review or call (281) 833-6755. Hablamos Español.
Primary and non contributory, and waiver of subrogation
These two clauses travel alongside additional insured status in almost every Texas construction contract, and they solve different problems. Neither is automatic.
Primary and non contributory means the other party's policy responds first and does not seek contribution from yours. Without it, both carriers can argue about sharing, your policy is drawn into a claim that was supposed to be someone else's, and your loss history absorbs it.
Waiver of subrogation means the insurer gives up its right to recover from you after paying a claim. Without it, the carrier can pay its insured and then pursue your business for the same money, which defeats the point of the arrangement entirely.
Checklist for both:
Confirm the primary and non contributory language appears in the Description of Operations box, and confirm an endorsement backs it
Confirm a waiver of subrogation endorsement is attached, not merely a checked box
Understand that many waivers require a written contract executed before the loss
Verify the waiver applies to the specific project or party named in your contract
Remember that both are separate endorsements, each with its own cost and each requiring its own request
How to actually verify status before a claim
The process below takes about fifteen minutes per subcontractor and prevents the scenario at the top of this article.
Ask for the certificate and the additional insured endorsement pages
Confirm the form numbers match what your contract requires
Confirm the edition dates and read the causation wording
Confirm your exact legal entity name appears, spelled correctly, on the schedule or covered by blanket wording
Confirm the policy period covers the entire term of your work, not merely the day the certificate was issued
Confirm products and completed operations coverage is included and carries a limit
Confirm the primary and non contributory and waiver of subrogation endorsements are attached
Diary every renewal date and request fresh documents at each one
Store the endorsement pages for the full statutory period, not just the certificate
Escalate immediately if a sub cannot produce an endorsement, because that usually means it does not exist
A note on timing that trips up contractors: certificates are frequently requested the morning a job is due to start. We issue same day certificates from all of our fifteen Houston and DFW offices, but a certificate issued quickly is still only a certificate. The endorsement is a policy change and should be arranged before you sign, not on the morning you mobilize.
Who asks for what, by trade
The requirement varies by who you work for and what you do, and the pattern is fairly predictable.
Subcontractors on commercial jobs are usually asked for additional insured status on both forms plus primary and non contributory, which starts with a general liability quote written to the contract
General contractors are usually asked by owners and developers for the same package, and must collect it downstream
Landlords typically require additional insured status on the tenant's policy, which we cover in the commercial property guide
Cleaning and janitorial firms are usually asked by property managers, addressed in our cleaning company general liability guide
Landscapers working for HOAs and commercial properties face the same requirement, covered in the landscaping coverage gaps guide
Anyone using 1099 labor has a separate problem worth understanding, set out in 1099 contractors and general liability in Texas
If you are unsure whether your operation needs general liability at all, start with is general liability insurance required in Texas, then look at what general liability actually covers and the 2026 Houston cost guide. Sole operators should read the sole proprietor risk guide, and smaller firms bundling coverage should compare the business owners policy.
Frequently Asked Questions
Q: What is the difference between a certificate holder and an additional insured?
A certificate holder is the party who received a copy of the certificate of insurance. It grants no rights under the policy. An additional insured has been added to the policy by endorsement and can claim a defense and indemnity from that insurer. The ACORD certificate states in its own text that it confers no rights upon the certificate holder.
Q: Which endorsement forms should my contract require?
Require CG 20 10 for ongoing operations and CG 20 37 for products and completed operations, both by form number. If the parties sit in tiers, CG 20 38 reaches upstream parties where CG 20 33 may not. Always request the endorsement pages and confirm the edition dates.
Q: Does checking the additional insured box on a certificate create coverage?
No. The box is a description prepared by whoever issued the certificate. Only the endorsement attached to the policy creates the status. If the endorsement is absent, the box is simply wrong and the carrier is not bound by it.
Q: How long does additional insured status last?
It is tied to the policy period of the policy it was issued under. When that policy renews, the status has to be re established and new documentation requested. This is why collecting certificates once at the start of a multi year relationship is not sufficient.
Q: Is primary and non contributory included automatically?
No. It is a separate endorsement and a separate request. Without it, the other carrier can seek contribution from your policy, which pulls your coverage and your loss history into a claim that should have belonged entirely to someone else.
Q: What should I do if a subcontractor cannot produce the endorsement?
Treat it as a red flag and stop before the work starts. In most cases the endorsement was never purchased. Call our business line at (281) 833-6755 and we can usually tell within a few minutes whether the coverage being described actually exists.
Q: Can I be an additional insured on a policy that excludes the work I care about?
Yes, and this is a common trap. Additional insured status gives you rights under a policy, including all of that policy's exclusions. If the underlying coverage excludes the exposure, your status does not restore it. Start a free contract and policy review if a contract is relying on this.
Related Articles
What general liability insurance covers for a business, a complete breakdown
Commercial umbrella insurance and contract requirements in Texas
Why AZ Insurance Stands Apart
Anyone can email a certificate. Reading the contract that demanded it, identifying which endorsement forms it actually requires, and confirming those forms exist on the policy is a different job, and it is the one that protects you when a claim lands two years after the job closed. We have been doing it from Houston since 2003, we are independent, and we compare multiple insurance companies rather than defending a single carrier's forms.
Before you sign the next contract, send us the insurance requirements page. Request a free contract and coverage review or call our business line at (281) 833-6755, and we will tell you what you are actually required to carry, and whether what you hold today satisfies it.
Latest Blogs
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong

Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot

Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open

A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026

A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.

Your Roof Before the Storm: The Four Things to Check on Your Policy While You Still Can
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.