Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Quick Answer: Hazard insurance isn't a separate policy — it's the piece of your homeowner's insurance policy that pays to repair or rebuild your home after a covered peril like fire, wind, or hail. Homeowners insurance is the full package: hazard (dwelling) coverage plus liability, personal property, and loss-of-use protection. When a lender says, "hazard insurance," they're just asking for proof of your homeowner's policy's dwelling coverage.
A lot of Texas homeowners get their first real scare not from a storm, but from a letter. Your mortgage lender demands "proof hazard insurance," and suddenly you're googling whether you need a second policy nobody told you about. You're not. Hazard insurance and homeowners' insurance are not two different products — hazard coverage is a built-in section of your homeowners insurance policy. Here's the thing most people miss: the terms get used interchangeably by lenders and agents alike, which is exactly why so many homeowners end up unsure what they're actually paying for.
What Is Hazard Insurance Exactly?
Hazard insurance is the portion of a homeowner's policy that protects the physical structure of your house — the dwelling itself — against specific, named perils like fire, windstorm, hail, lightning, and explosion. It's not a standalone policy you buy separately in Texas; it's one coverage type, usually called "Coverage A: Dwelling," sitting inside a broader homeowners insurance contract. A 2024 Insurance Information Institute review of standard policy forms confirms hazard coverage almost always refers to this dwelling-protection component, not an independent product. If your roof gets torn off in a hailstorm, hazard coverage pays for the rebuild — and if you're unsure how your roof's age affects that payout, it's worth checking how roof age impacts your Texas home insurance before a claim ever happens.
What Is Homeowners Insurance?
Homeowners insurance is the umbrella contract that bundles hazard (dwelling) coverage with several other protections your finances actually need. Homeowners insurance is a type of property insurance that includes hazard coverage as one of its core components — but it goes further, adding personal property coverage, liability protection, and loss-of-use coverage if you're displaced during repairs. Most Texas homes are insured under an HO-3 policy, the standard form that covers the dwelling on an "open perils" basis while covering belongings on a named-perils basis. If you've seen HO-A, HO-B, and HO-3 thrown around, our guide on HO-A vs. HO-B vs. HO-3 in Texas walks through exactly what separates them. When you're ready to see what a full policy actually costs, start a home insurance quote in a few minutes.
Is Hazard Insurance the Same as Homeowners Insurance?
No. Hazard insurance is a subset of homeowners insurance. Picture it this way: homeowners' insurance is the whole toolbox, and hazard coverage is just the hammer inside it.
Feature | Hazard Insurance | Homeowners Insurance |
What it is | A coverage section within a policy | The full insurance policy |
What it protects | The physical structure (dwelling) | Dwelling, belongings, liability, loss of use |
Sold separately? | No — not as a standalone Texas policy | Yes, purchased as a complete policy |
Covers your furniture or electronics? | No | Yes, under personal property coverage |
Covers a lawsuit if someone is hurt at your home? | No | Yes, under liability coverage |
Covers hotel costs if your home is uninhabitable? | No | Yes, under loss-of-use coverage |
Required by mortgage lenders? | Yes, as part of the homeowner's policy | Yes, typically escrowed with your mortgage |
This matters because homeowners sometimes assume "hazard coverage" and "full coverage" mean the same thing. They don't — a policy that only addressed hazard-level perils would leave you exposed if a guest slipped on your porch, or a burst pipe forced you into a hotel for three weeks.
What Does Hazard Insurance Actually Cover?
Hazard coverage responds to a defined list of perils, not every possible cause of damage:
Fire and smoke damage
Windstorm and hail
Lightning strikes
Explosions
Vandalism and malicious mischief
Damage from vehicles or falling objects
What it typically won't touch is flood damage, which requires separate coverage through the National Flood Insurance Program or a private flood carrier — a distinction that trips up a lot of Gulf Coast homeowners every hurricane season. Along the coast, wind and hail damage may also fall under the Texas Windstorm Insurance Association rather than your standard carrier, so it's worth reading on whether your Houston home needs TWIA windstorm insurance before you assume you're covered.
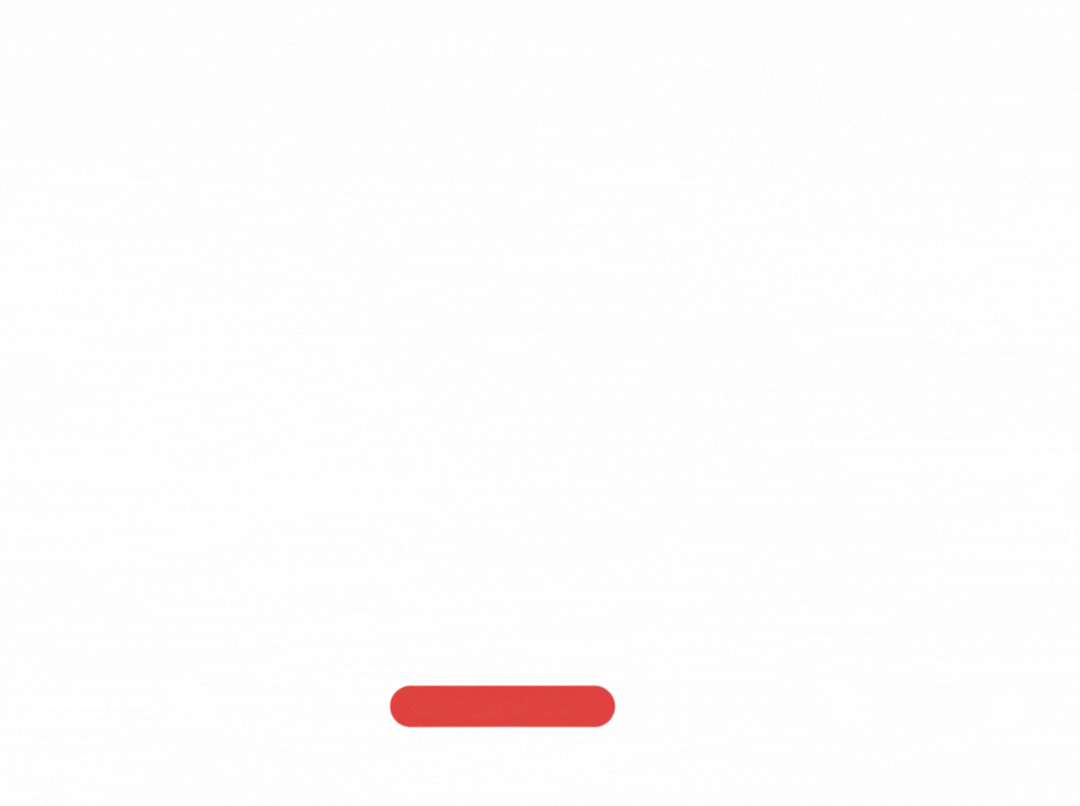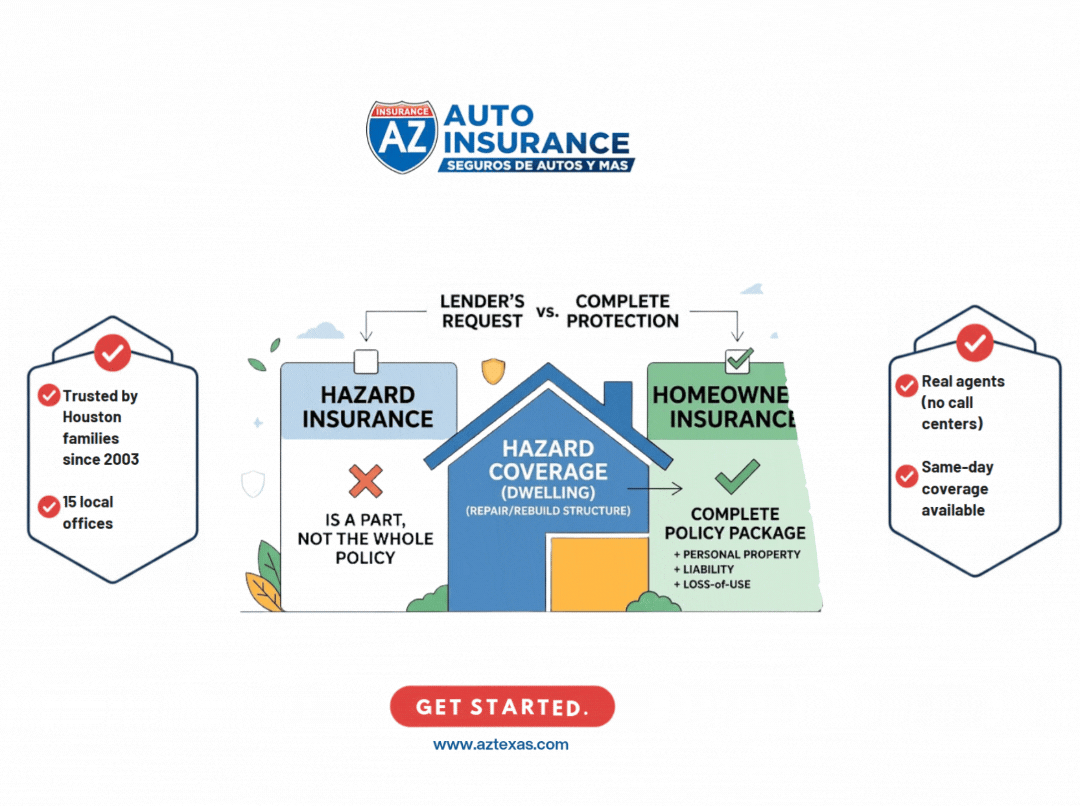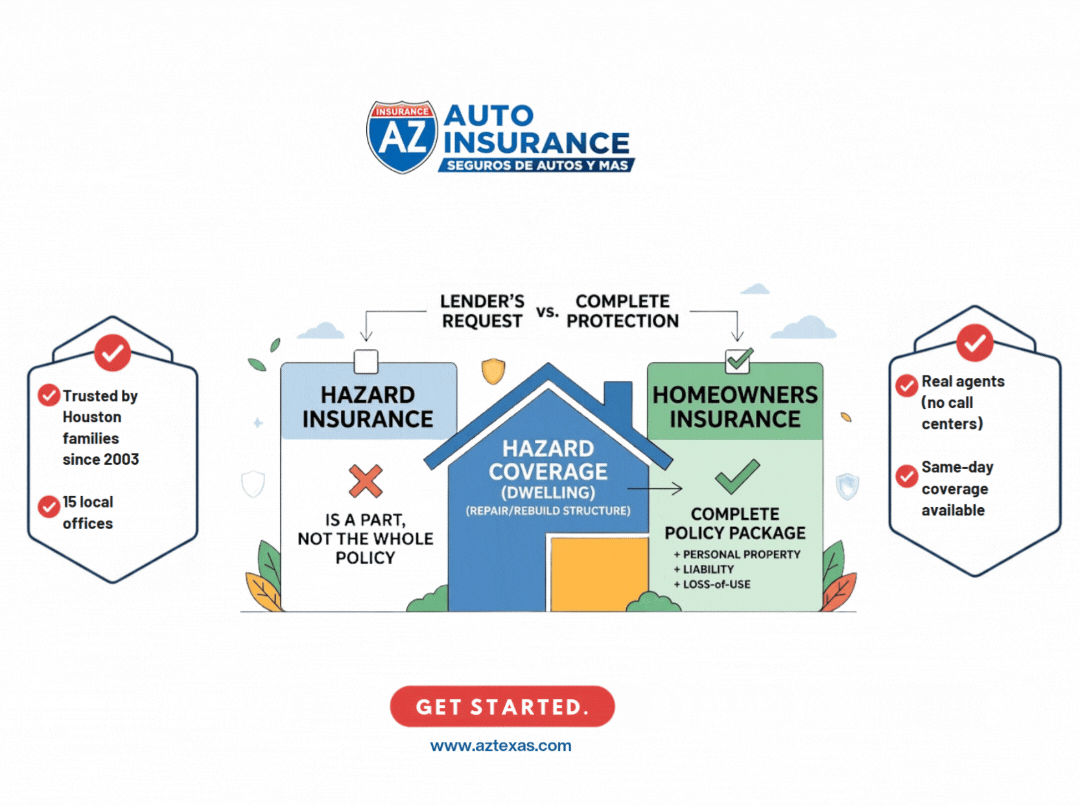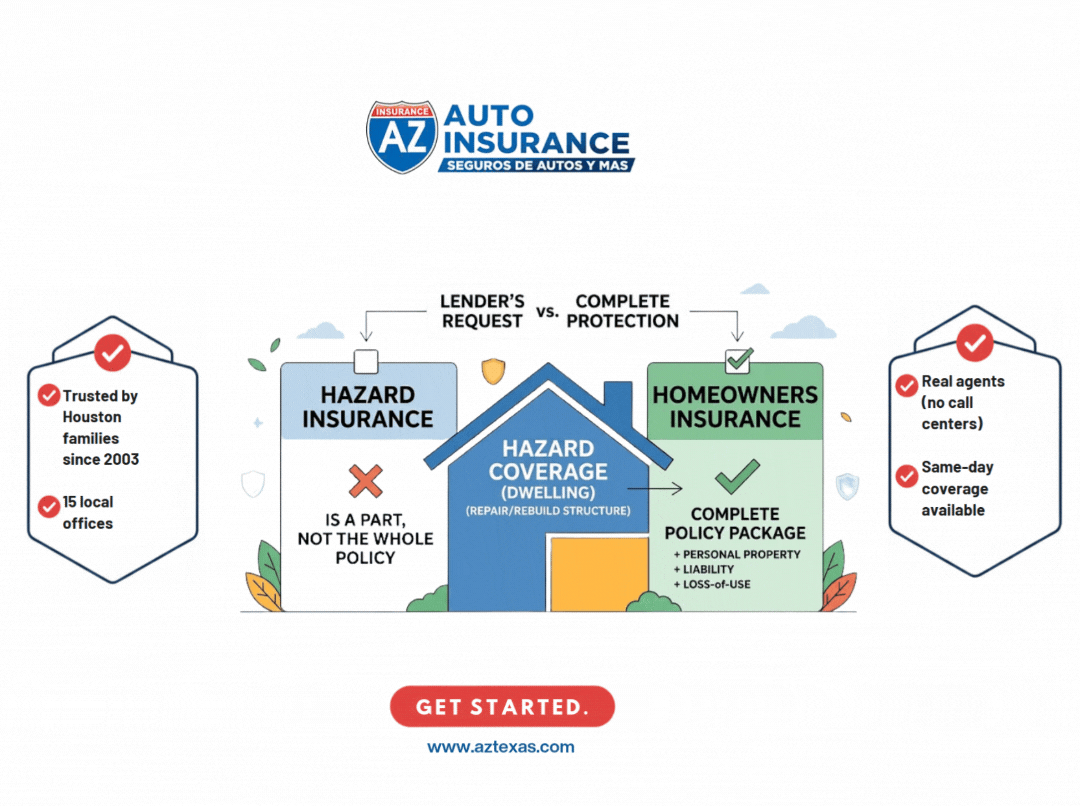
What Do Homeowners Insurance Policies Cover Beyond Hazard Risks?
A standard homeowners policy layers three additional protections on top of hazard coverage:
Personal property coverage — pays to replace furniture, electronics, and belongings damaged or stolen, usually at a percentage of your dwelling coverage limit
Liability coverage — pays legal and medical costs if someone is injured on your property and sues
Loss-of-use coverage — covers temporary housing and extra living expenses if your home becomes unlivable after a covered loss
Whether a claim gets paid at actual cash value or full replacement cost also changes what you walk away with, and that distinction is bigger than most homeowners realize — our breakdown of actual cash value vs. replacement cost in Texas is worth reading before your mid-claim, not during it. If you're renting rather than owning, the liability logic still applies — look at renters insurance to see how personal liability protection carries over without a mortgage in the picture.
Why Do Lenders Ask for "Hazard Insurance" on a Mortgage?
Mortgage paperwork is where this naming mess really started. Lenders use "hazard insurance" as shorthand because, from a bank's perspective, they only care about one thing: whether the structure they lent money against is protected against fire, wind, and similar perils. A mortgage lender requires hazard insurance to protect its financial interest in the property, typically requiring dwelling coverage equal to or greater than the loan balance. Satisfying that usually means simply carrying a standard homeowner's policy — the lender isn't asking you to buy something extra, just to prove your existing homeowners insurance includes adequate dwelling coverage. If you've never worked out how much dwelling coverage your home needs, our guide on how much dwelling coverage a Houston home needs breaks down the math lenders use.
Which One Do Texas Homeowners Actually Need?
You don't choose "just hazard" or "just homeowners" separately — buying homeowners insurance automatically bundles in hazard coverage. The real decision is which homeowners' policy fits your risk profile:
Confirming your dwelling coverage matches your home's actual rebuild cost, not its market value
Adding flood coverage separately if you're anywhere near a Houston bayou, floodplain, or coastal zone
Reviewing your windstorm and hail deductible, since Texas policies often carry a separate percentage-based deductible for storm damage
Bundling in personal property and liability limits that match your household, not a generic default
This works well for most single-family homes but breaks down fast for landlords or anyone running a business out of a residential property — in those cases, a standard homeowner's policy alone won't cut it, and it's worth pairing it with business insurance or general liability insurance to close the gap. An independent agent can walk through your specific address faster than a generic checklist can, so if you want a second set of eyes, our team is a quick contact away.
How Much Does Coverage Cost in Texas?
Pricing depends heavily on where in Texas you live, your roof condition, and your proximity to the coast. Homes near Houston's coastal counties generally pay more for wind and hail coverage than homes further inland, and an aging roof often means a higher premium. Dwelling coverage amount, deductible choice, and claims history tend to be the three biggest levers on your premium. Rather than guessing, the fastest way to see real numbers is a home insurance quote, since national averages rarely reflect Texas storm pricing.
Frequently Asked Questions
Q: What is hazard insurance?
A: The section of a homeowner's policy that pays to repair or rebuild your home structure after a covered peril, like fire, wind, hail, or lightning. It's not sold as a standalone policy in Texas.
Q: How does hazard insurance work with a mortgage?
A: Lenders require proof of hazard coverage before approving or maintaining a loan. This is almost always satisfied by a standard homeowner's policy with dwelling coverage equal to or above the loan amount.
Q: What's the difference between hazard insurance and homeowners' insurance?
A: Hazard insurance covers only the physical structure against named perils. Homeowners insurance is the complete policy — hazard coverage plus personal property, liability, and loss-of-use protection.
Q: Does hazard insurance cover flood damage?
A: No. Flood damage is excluded from standard hazard and homeowners' coverage in Texas and requires a separate flood policy through the NFIP or a private carrier.
Q: Is homeowners insurance required by law in Texas? A: Texas doesn't legally require it, but any mortgage lender will as a loan condition. Owning your home outright makes it optional, though rarely a smart trade-off given Texas storm risk.
Q: Can I buy hazard insurance without a full homeowner's policy?
A: Generally, no. In Texas, hazard coverage comes packaged inside homeowners' insurance rather than sold on its own, so "getting hazard insurance" means getting homeowners' insurance.
The Bottom Line
Stop thinking of hazard insurance and homeowners' insurance as two products competing for your attention — they're stacked on top of each other, not sitting on opposite sides of a decision. Homeowners' insurance is the policy; hazard coverage is one section inside it, protecting your home structure against fire, wind, and hail. The real work isn't picking between them — it's making sure your dwelling coverage reflects what it would actually cost to rebuild today, and your liability limits match the life you're living in that house. If any of that feels like a guess right now, get a straight answer with a home insurance quote or reach out directly through aztexas.com.
Quick Answer: Hazard insurance isn't a separate policy — it's the piece of your homeowner's insurance policy that pays to repair or rebuild your home after a covered peril like fire, wind, or hail. Homeowners insurance is the full package: hazard (dwelling) coverage plus liability, personal property, and loss-of-use protection. When a lender says, "hazard insurance," they're just asking for proof of your homeowner's policy's dwelling coverage.
A lot of Texas homeowners get their first real scare not from a storm, but from a letter. Your mortgage lender demands "proof hazard insurance," and suddenly you're googling whether you need a second policy nobody told you about. You're not. Hazard insurance and homeowners' insurance are not two different products — hazard coverage is a built-in section of your homeowners insurance policy. Here's the thing most people miss: the terms get used interchangeably by lenders and agents alike, which is exactly why so many homeowners end up unsure what they're actually paying for.
What Is Hazard Insurance Exactly?
Hazard insurance is the portion of a homeowner's policy that protects the physical structure of your house — the dwelling itself — against specific, named perils like fire, windstorm, hail, lightning, and explosion. It's not a standalone policy you buy separately in Texas; it's one coverage type, usually called "Coverage A: Dwelling," sitting inside a broader homeowners insurance contract. A 2024 Insurance Information Institute review of standard policy forms confirms hazard coverage almost always refers to this dwelling-protection component, not an independent product. If your roof gets torn off in a hailstorm, hazard coverage pays for the rebuild — and if you're unsure how your roof's age affects that payout, it's worth checking how roof age impacts your Texas home insurance before a claim ever happens.
What Is Homeowners Insurance?
Homeowners insurance is the umbrella contract that bundles hazard (dwelling) coverage with several other protections your finances actually need. Homeowners insurance is a type of property insurance that includes hazard coverage as one of its core components — but it goes further, adding personal property coverage, liability protection, and loss-of-use coverage if you're displaced during repairs. Most Texas homes are insured under an HO-3 policy, the standard form that covers the dwelling on an "open perils" basis while covering belongings on a named-perils basis. If you've seen HO-A, HO-B, and HO-3 thrown around, our guide on HO-A vs. HO-B vs. HO-3 in Texas walks through exactly what separates them. When you're ready to see what a full policy actually costs, start a home insurance quote in a few minutes.
Is Hazard Insurance the Same as Homeowners Insurance?
No. Hazard insurance is a subset of homeowners insurance. Picture it this way: homeowners' insurance is the whole toolbox, and hazard coverage is just the hammer inside it.
Feature | Hazard Insurance | Homeowners Insurance |
What it is | A coverage section within a policy | The full insurance policy |
What it protects | The physical structure (dwelling) | Dwelling, belongings, liability, loss of use |
Sold separately? | No — not as a standalone Texas policy | Yes, purchased as a complete policy |
Covers your furniture or electronics? | No | Yes, under personal property coverage |
Covers a lawsuit if someone is hurt at your home? | No | Yes, under liability coverage |
Covers hotel costs if your home is uninhabitable? | No | Yes, under loss-of-use coverage |
Required by mortgage lenders? | Yes, as part of the homeowner's policy | Yes, typically escrowed with your mortgage |
This matters because homeowners sometimes assume "hazard coverage" and "full coverage" mean the same thing. They don't — a policy that only addressed hazard-level perils would leave you exposed if a guest slipped on your porch, or a burst pipe forced you into a hotel for three weeks.
What Does Hazard Insurance Actually Cover?
Hazard coverage responds to a defined list of perils, not every possible cause of damage:
Fire and smoke damage
Windstorm and hail
Lightning strikes
Explosions
Vandalism and malicious mischief
Damage from vehicles or falling objects
What it typically won't touch is flood damage, which requires separate coverage through the National Flood Insurance Program or a private flood carrier — a distinction that trips up a lot of Gulf Coast homeowners every hurricane season. Along the coast, wind and hail damage may also fall under the Texas Windstorm Insurance Association rather than your standard carrier, so it's worth reading on whether your Houston home needs TWIA windstorm insurance before you assume you're covered.
What Do Homeowners Insurance Policies Cover Beyond Hazard Risks?
A standard homeowners policy layers three additional protections on top of hazard coverage:
Personal property coverage — pays to replace furniture, electronics, and belongings damaged or stolen, usually at a percentage of your dwelling coverage limit
Liability coverage — pays legal and medical costs if someone is injured on your property and sues
Loss-of-use coverage — covers temporary housing and extra living expenses if your home becomes unlivable after a covered loss
Whether a claim gets paid at actual cash value or full replacement cost also changes what you walk away with, and that distinction is bigger than most homeowners realize — our breakdown of actual cash value vs. replacement cost in Texas is worth reading before your mid-claim, not during it. If you're renting rather than owning, the liability logic still applies — look at renters insurance to see how personal liability protection carries over without a mortgage in the picture.
Why Do Lenders Ask for "Hazard Insurance" on a Mortgage?
Mortgage paperwork is where this naming mess really started. Lenders use "hazard insurance" as shorthand because, from a bank's perspective, they only care about one thing: whether the structure they lent money against is protected against fire, wind, and similar perils. A mortgage lender requires hazard insurance to protect its financial interest in the property, typically requiring dwelling coverage equal to or greater than the loan balance. Satisfying that usually means simply carrying a standard homeowner's policy — the lender isn't asking you to buy something extra, just to prove your existing homeowners insurance includes adequate dwelling coverage. If you've never worked out how much dwelling coverage your home needs, our guide on how much dwelling coverage a Houston home needs breaks down the math lenders use.
Which One Do Texas Homeowners Actually Need?
You don't choose "just hazard" or "just homeowners" separately — buying homeowners insurance automatically bundles in hazard coverage. The real decision is which homeowners' policy fits your risk profile:
Confirming your dwelling coverage matches your home's actual rebuild cost, not its market value
Adding flood coverage separately if you're anywhere near a Houston bayou, floodplain, or coastal zone
Reviewing your windstorm and hail deductible, since Texas policies often carry a separate percentage-based deductible for storm damage
Bundling in personal property and liability limits that match your household, not a generic default
This works well for most single-family homes but breaks down fast for landlords or anyone running a business out of a residential property — in those cases, a standard homeowner's policy alone won't cut it, and it's worth pairing it with business insurance or general liability insurance to close the gap. An independent agent can walk through your specific address faster than a generic checklist can, so if you want a second set of eyes, our team is a quick contact away.
How Much Does Coverage Cost in Texas?
Pricing depends heavily on where in Texas you live, your roof condition, and your proximity to the coast. Homes near Houston's coastal counties generally pay more for wind and hail coverage than homes further inland, and an aging roof often means a higher premium. Dwelling coverage amount, deductible choice, and claims history tend to be the three biggest levers on your premium. Rather than guessing, the fastest way to see real numbers is a home insurance quote, since national averages rarely reflect Texas storm pricing.
Frequently Asked Questions
Q: What is hazard insurance?
A: The section of a homeowner's policy that pays to repair or rebuild your home structure after a covered peril, like fire, wind, hail, or lightning. It's not sold as a standalone policy in Texas.
Q: How does hazard insurance work with a mortgage?
A: Lenders require proof of hazard coverage before approving or maintaining a loan. This is almost always satisfied by a standard homeowner's policy with dwelling coverage equal to or above the loan amount.
Q: What's the difference between hazard insurance and homeowners' insurance?
A: Hazard insurance covers only the physical structure against named perils. Homeowners insurance is the complete policy — hazard coverage plus personal property, liability, and loss-of-use protection.
Q: Does hazard insurance cover flood damage?
A: No. Flood damage is excluded from standard hazard and homeowners' coverage in Texas and requires a separate flood policy through the NFIP or a private carrier.
Q: Is homeowners insurance required by law in Texas? A: Texas doesn't legally require it, but any mortgage lender will as a loan condition. Owning your home outright makes it optional, though rarely a smart trade-off given Texas storm risk.
Q: Can I buy hazard insurance without a full homeowner's policy?
A: Generally, no. In Texas, hazard coverage comes packaged inside homeowners' insurance rather than sold on its own, so "getting hazard insurance" means getting homeowners' insurance.
The Bottom Line
Stop thinking of hazard insurance and homeowners' insurance as two products competing for your attention — they're stacked on top of each other, not sitting on opposite sides of a decision. Homeowners' insurance is the policy; hazard coverage is one section inside it, protecting your home structure against fire, wind, and hail. The real work isn't picking between them — it's making sure your dwelling coverage reflects what it would actually cost to rebuild today, and your liability limits match the life you're living in that house. If any of that feels like a guess right now, get a straight answer with a home insurance quote or reach out directly through aztexas.com.
Latest Blogs
Average Hazard Insurance Cost: What Homeowners Can Expect

What Is Home Hazard Insurance and What Does It Cover?

Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong

Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot

Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
One is a name on a form. The other is coverage under someone else's policy. Here is how Texas contractors tell them apart before a claim decides it for them.
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
One is a name on a form. The other is coverage under someone else's policy. Here is how Texas contractors tell them apart before a claim decides it for them.
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
One is a name on a form. The other is coverage under someone else's policy. Here is how Texas contractors tell them apart before a claim decides it for them.
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong
Your policy will not pay to redo the work you got wrong. In Texas it may still pay for the damage that work caused. Here is exactly where the line sits.
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong
Your policy will not pay to redo the work you got wrong. In Texas it may still pay for the damage that work caused. Here is exactly where the line sits.
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong
Your policy will not pay to redo the work you got wrong. In Texas it may still pay for the damage that work caused. Here is exactly where the line sits.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
One is a name on a form. The other is coverage under someone else's policy. Here is how Texas contractors tell them apart before a claim decides it for them.
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong
Your policy will not pay to redo the work you got wrong. In Texas it may still pay for the damage that work caused. Here is exactly where the line sits.