Soporte rápido de profesionales de seguros de confianza Llame +1 713-777-2886 hoy!
¡Llame hoy al +1 713-777-2886 para obtener un soporte profesional rápido!
¡Llame hoy al +1 713-777-2886 para obtener un soporte profesional rápido!
Tabla de Contenido
Título
Deje que AZ Insurance le ayude
a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deja que A-Z Auto Insurance te ayude a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
How to Lower Car Insurance: 10 Practical Ways to Pay Less
How to Lower Car Insurance: 10 Practical Ways to Pay Less
How to Lower Car Insurance: 10 Practical Ways to Pay Less
How to Lower Car Insurance: 10 Practical Ways to Pay Less
How to Lower Car Insurance: 10 Practical Ways to Pay Less

Quick Answer: To lower your car insurance quickly, compare equal quotes from several companies, review every available discount, and test a higher deductible that you could comfortably pay. Bundling policies and paying in full may also help. Over time, safe driving, accurate mileage, better credit, and uninterrupted coverage can produce larger savings. Cut waste first—not protection you may need after a crash.
A renewal increase does not always mean you did something wrong. Repair labor, replacement parts, medical bills, theft, traffic, and storm claims can raise prices across a region. Houston drivers face added risks from floods, hail, hurricanes, and crowded roads.
Even so, your rate is not fixed. The company, vehicle, coverage, deductible, payment plan, and discounts all affect the final price. Start by reviewing the basic choices available with Houston auto insurance, then use the steps below to build a policy that fits your budget.
What Makes Texas Car Insurance Expensive?
Insurers estimate how likely you are to file a claim and how much that claim may cost. Their pricing may consider:
Your ZIP code and where the car stays overnight
Your age, driving history, and past claims
The vehicle's value, repair cost, safety record, and theft risk
Annual mileage and whether you commute or drive for work
Credit-based insurance information allowed under Texas rules
Liability limits, optional coverage, and deductibles
Other drivers who live in your home
Each company weighs these details differently. That is why the same household can receive very different quotes.
10 Smart Ways to Cut Your Car Insurance Premium
1. Compare Prices Before Renewing
Request quotes at least once a year and after a move, marriage, vehicle purchase, or driver change. Make sure the coverage limits, deductibles, drivers, and optional benefits match across all quotes.A lower quote isn't a real saving if it reduces the amount of protection you have.This guide explains how to switch car insurance providers without creating a coverage gap.
2. Test a Higher Deductible
Ask for prices with $500 and $1,000 collision and comprehensive deductibles. Then divide the extra deductible by the yearly saving. If the higher deductible adds $500 of risk but saves only $50 a year, it takes ten claim-free years to break even. Review this simple guide on car insurance deductible before making the change.
3. Price a Home or Renters Bundle
A multi-policy discount can reduce your bill, but compare the total cost of all policies—not just the advertised percentage. Renters coverage is often affordable and protects belongings that auto insurance does not cover. Review the available renters insurance options, then compare the bundled total with separate policies.
4. Request a Complete Discount Check
Ask about safe-driver, multi-car, low-mileage, good-student, anti-theft, paperless, automatic-payment, military, employer, and membership savings. Discounts are not identical across carriers. Families should also review the cost and rules before adding a teen driver in Texas.
5. Ask About Defensive Driving
An approved course may earn a discount, but the amount and eligibility depend on the insurer. Call first and ask which course it accepts, how long the discount lasts, and which parts of the policy receive it. If you have a citation, get court approval before taking a class for dismissal.
6. Improve the Credit Details Insurers Use
Pay bills on time, lower card balances, and correct errors on your credit reports. Results are usually gradual rather than immediate. Texas also provides special consideration when certain events, such as identity theft, divorce, temporary unemployment, or a major illness, directly harm a person's credit. Ask the carrier what proof it requires.
7. Review Coverage on an Older Car
Collision and comprehensive claims are limited by the car's current value, minus the deductible. If the likely payment is small compared with the yearly cost, ask for prices without one or both coverages. Keep them when required by a lender. If you still owe more than the vehicle is worth, first learn how gap insurance works.
8. Compare Payment Plans
Paying a six-month or annual premium at once may unlock a discount and avoid installment fees. Ask for the full cost under each plan. Do not empty your emergency fund or carry high credit card interest merely to save a small amount.
9. Consider a Driving-Tracking Program
Telematics programs may track mileage, braking, acceleration, phone use, speed, or driving time. They tend to suit careful, low-mileage drivers. Before joining, ask whether poor results can raise your rate, what data is stored, and how passenger trips are corrected.
10. Avoid a Break in Coverage
Start a replacement policy before canceling the old one. Some insurers charge more after a lapse, even when it lasted only a short time. If you are storing a vehicle or rarely driving, do not cancel without advice. This article explains when you may still need insurance on a car you do not drive.

Estimated Savings from Each Strategy
These figures are broad planning ranges, not promises. Discounts may apply to only part of a policy.
Strategy | Possible Saving | When It May Start |
Compare equal quotes | Varies; often the biggest opportunity | New policy date |
Raise a $500 deductible to $1,000 | About 10%–25% on collision and comprehensive | Policy change |
Bundle auto with home or renters | Often 5%–25% | Bundle start date |
Defensive driving course | Carrier-specific; sometimes up to 10% | Certificate approval |
Pay the premium in full | Discount and fee savings vary | Payment or renewal |
Telematics program | Often 5%–30% for qualifying drivers | Enrollment or renewal |
Remove collision or comprehensive | Cost of the removed coverage | Policy change |
Improve credit information | Varies by driver and insurer | Future quote or renewal |
Always compare the final dollar amount. Discounts do not simply add together, and the company with the largest advertised discount may not have the lowest total price.
Lowering Rates After a Ticket, Accident, or SR-22
After a Ticket
Ask the court whether the ticket qualifies for dismissal through a driving safety course. Meet every deadline and keep the completion proof. If the violation is already on your record, shop again as it gets older because carriers treat tickets differently. Houston-area drivers can also learn how school-zone tickets may affect insurance.
After an At-Fault Accident
Check whether accident forgiveness was active before the crash; buying it later will not remove an existing loss. Review the claim for errors, ask how long it will affect the price, and compare equal quotes at renewal. The effect often falls over time, but each insurer uses its own rules.
When You Need an SR-22
An SR-22 is a filing that proves you carry the required liability coverage. It is not a separate insurance policy. Texas commonly requires the filing for two years from the qualifying conviction or judgment. Keep it active because a lapse can lead to further action. Prices vary, so compare carriers and review this guide to Texas SR-22 insurance costs.
Life Changes That May Lower Your Rate
Tell your agent when you move, marry, work from home, retire, pay off a vehicle, or remove a driver who no longer uses the cars. A student living away without regular vehicle access may also qualify for a discount.
Homeownership can affect auto pricing with some carriers. If you recently bought a house, compare a bundle after reviewing Texas homeowners insurance. A bundle is worthwhile only when its combined price and coverage beat the separate alternatives.
Costly Mistakes to Avoid
Do not lower liability limits without considering what a serious injury or a totaled new vehicle could cost. Texas minimum liability may satisfy the law but still leave a large unpaid balance. Understanding the main purpose of auto insurance can help you separate useful protection from optional extras.
Also avoid false mileage, an incorrect address, missing household drivers, or a deductible you cannot pay. Do not assume a cheap policy meets every legal or lender rule. New vehicle owners should confirm whether they need insurance before registering a car in Texas.
A Simple Plan for This Week
Find your current declarations page.
Correct the drivers, mileage, address, vehicle use, and lender details.
Choose the lowest limits you are comfortable carrying.
Request every available discount and several deductible options.
Compare at least three quotes with identical coverage.
Activate the replacement before canceling the current policy.
When you are ready, use the online insurance quote form and keep your declarations page nearby for a fair comparison.
Frequently Asked Questions
How can I lower car insurance right away?
Compare equal quotes, check discounts, correct your mileage, and request prices for different deductibles and payment plans. The saving begins when the insurer processes the change or the new policy starts.
Can I lower my rate with a poor driving record?
Yes. Compare standard and nonstandard carriers, avoid new violations, and keep your policy active. Prices may improve as older tickets and claims move outside an insurer's review period.
What can I change without reducing coverage?
Shop other carriers, request discounts, bundle policies, pay in full, and report lower mileage. These steps can cut costs while keeping the same limits and protection.
Will defensive driving lower my Texas premium?
Possibly. Each carrier decides which course qualifies and how much it saves. Confirm the details before enrolling.
Should I remove collision and comprehensive?
Consider it only for a paid-off, low-value car that you could replace yourself. Houston flood, hail, theft, and storm risks can make comprehensive coverage useful even on an older vehicle.
Why did my price rise without a claim?
Regional storm losses, repair costs, medical costs, theft, traffic, vehicle prices, or a company-wide rate change can affect your renewal. Ask for an explanation and compare the market.
Compare Houston Car Insurance Quotes Today
AZ Insurance Agency helps Houston drivers compare coverage from multiple carriers, including options for tickets, coverage gaps, and SR-22 filings. Speak with a bilingual agent online or visit one of the agency's Texas insurance locations to review your choices without cutting protection blindly.
Quick Answer: To lower your car insurance quickly, compare equal quotes from several companies, review every available discount, and test a higher deductible that you could comfortably pay. Bundling policies and paying in full may also help. Over time, safe driving, accurate mileage, better credit, and uninterrupted coverage can produce larger savings. Cut waste first—not protection you may need after a crash.
A renewal increase does not always mean you did something wrong. Repair labor, replacement parts, medical bills, theft, traffic, and storm claims can raise prices across a region. Houston drivers face added risks from floods, hail, hurricanes, and crowded roads.
Even so, your rate is not fixed. The company, vehicle, coverage, deductible, payment plan, and discounts all affect the final price. Start by reviewing the basic choices available with Houston auto insurance, then use the steps below to build a policy that fits your budget.
What Makes Texas Car Insurance Expensive?
Insurers estimate how likely you are to file a claim and how much that claim may cost. Their pricing may consider:
Your ZIP code and where the car stays overnight
Your age, driving history, and past claims
The vehicle's value, repair cost, safety record, and theft risk
Annual mileage and whether you commute or drive for work
Credit-based insurance information allowed under Texas rules
Liability limits, optional coverage, and deductibles
Other drivers who live in your home
Each company weighs these details differently. That is why the same household can receive very different quotes.
10 Smart Ways to Cut Your Car Insurance Premium
1. Compare Prices Before Renewing
Request quotes at least once a year and after a move, marriage, vehicle purchase, or driver change. Make sure the coverage limits, deductibles, drivers, and optional benefits match across all quotes.A lower quote isn't a real saving if it reduces the amount of protection you have.This guide explains how to switch car insurance providers without creating a coverage gap.
2. Test a Higher Deductible
Ask for prices with $500 and $1,000 collision and comprehensive deductibles. Then divide the extra deductible by the yearly saving. If the higher deductible adds $500 of risk but saves only $50 a year, it takes ten claim-free years to break even. Review this simple guide on car insurance deductible before making the change.
3. Price a Home or Renters Bundle
A multi-policy discount can reduce your bill, but compare the total cost of all policies—not just the advertised percentage. Renters coverage is often affordable and protects belongings that auto insurance does not cover. Review the available renters insurance options, then compare the bundled total with separate policies.
4. Request a Complete Discount Check
Ask about safe-driver, multi-car, low-mileage, good-student, anti-theft, paperless, automatic-payment, military, employer, and membership savings. Discounts are not identical across carriers. Families should also review the cost and rules before adding a teen driver in Texas.
5. Ask About Defensive Driving
An approved course may earn a discount, but the amount and eligibility depend on the insurer. Call first and ask which course it accepts, how long the discount lasts, and which parts of the policy receive it. If you have a citation, get court approval before taking a class for dismissal.
6. Improve the Credit Details Insurers Use
Pay bills on time, lower card balances, and correct errors on your credit reports. Results are usually gradual rather than immediate. Texas also provides special consideration when certain events, such as identity theft, divorce, temporary unemployment, or a major illness, directly harm a person's credit. Ask the carrier what proof it requires.
7. Review Coverage on an Older Car
Collision and comprehensive claims are limited by the car's current value, minus the deductible. If the likely payment is small compared with the yearly cost, ask for prices without one or both coverages. Keep them when required by a lender. If you still owe more than the vehicle is worth, first learn how gap insurance works.
8. Compare Payment Plans
Paying a six-month or annual premium at once may unlock a discount and avoid installment fees. Ask for the full cost under each plan. Do not empty your emergency fund or carry high credit card interest merely to save a small amount.
9. Consider a Driving-Tracking Program
Telematics programs may track mileage, braking, acceleration, phone use, speed, or driving time. They tend to suit careful, low-mileage drivers. Before joining, ask whether poor results can raise your rate, what data is stored, and how passenger trips are corrected.
10. Avoid a Break in Coverage
Start a replacement policy before canceling the old one. Some insurers charge more after a lapse, even when it lasted only a short time. If you are storing a vehicle or rarely driving, do not cancel without advice. This article explains when you may still need insurance on a car you do not drive.
Estimated Savings from Each Strategy
These figures are broad planning ranges, not promises. Discounts may apply to only part of a policy.
Strategy | Possible Saving | When It May Start |
Compare equal quotes | Varies; often the biggest opportunity | New policy date |
Raise a $500 deductible to $1,000 | About 10%–25% on collision and comprehensive | Policy change |
Bundle auto with home or renters | Often 5%–25% | Bundle start date |
Defensive driving course | Carrier-specific; sometimes up to 10% | Certificate approval |
Pay the premium in full | Discount and fee savings vary | Payment or renewal |
Telematics program | Often 5%–30% for qualifying drivers | Enrollment or renewal |
Remove collision or comprehensive | Cost of the removed coverage | Policy change |
Improve credit information | Varies by driver and insurer | Future quote or renewal |
Always compare the final dollar amount. Discounts do not simply add together, and the company with the largest advertised discount may not have the lowest total price.
Lowering Rates After a Ticket, Accident, or SR-22
After a Ticket
Ask the court whether the ticket qualifies for dismissal through a driving safety course. Meet every deadline and keep the completion proof. If the violation is already on your record, shop again as it gets older because carriers treat tickets differently. Houston-area drivers can also learn how school-zone tickets may affect insurance.
After an At-Fault Accident
Check whether accident forgiveness was active before the crash; buying it later will not remove an existing loss. Review the claim for errors, ask how long it will affect the price, and compare equal quotes at renewal. The effect often falls over time, but each insurer uses its own rules.
When You Need an SR-22
An SR-22 is a filing that proves you carry the required liability coverage. It is not a separate insurance policy. Texas commonly requires the filing for two years from the qualifying conviction or judgment. Keep it active because a lapse can lead to further action. Prices vary, so compare carriers and review this guide to Texas SR-22 insurance costs.
Life Changes That May Lower Your Rate
Tell your agent when you move, marry, work from home, retire, pay off a vehicle, or remove a driver who no longer uses the cars. A student living away without regular vehicle access may also qualify for a discount.
Homeownership can affect auto pricing with some carriers. If you recently bought a house, compare a bundle after reviewing Texas homeowners insurance. A bundle is worthwhile only when its combined price and coverage beat the separate alternatives.
Costly Mistakes to Avoid
Do not lower liability limits without considering what a serious injury or a totaled new vehicle could cost. Texas minimum liability may satisfy the law but still leave a large unpaid balance. Understanding the main purpose of auto insurance can help you separate useful protection from optional extras.
Also avoid false mileage, an incorrect address, missing household drivers, or a deductible you cannot pay. Do not assume a cheap policy meets every legal or lender rule. New vehicle owners should confirm whether they need insurance before registering a car in Texas.
A Simple Plan for This Week
Find your current declarations page.
Correct the drivers, mileage, address, vehicle use, and lender details.
Choose the lowest limits you are comfortable carrying.
Request every available discount and several deductible options.
Compare at least three quotes with identical coverage.
Activate the replacement before canceling the current policy.
When you are ready, use the online insurance quote form and keep your declarations page nearby for a fair comparison.
Frequently Asked Questions
How can I lower car insurance right away?
Compare equal quotes, check discounts, correct your mileage, and request prices for different deductibles and payment plans. The saving begins when the insurer processes the change or the new policy starts.
Can I lower my rate with a poor driving record?
Yes. Compare standard and nonstandard carriers, avoid new violations, and keep your policy active. Prices may improve as older tickets and claims move outside an insurer's review period.
What can I change without reducing coverage?
Shop other carriers, request discounts, bundle policies, pay in full, and report lower mileage. These steps can cut costs while keeping the same limits and protection.
Will defensive driving lower my Texas premium?
Possibly. Each carrier decides which course qualifies and how much it saves. Confirm the details before enrolling.
Should I remove collision and comprehensive?
Consider it only for a paid-off, low-value car that you could replace yourself. Houston flood, hail, theft, and storm risks can make comprehensive coverage useful even on an older vehicle.
Why did my price rise without a claim?
Regional storm losses, repair costs, medical costs, theft, traffic, vehicle prices, or a company-wide rate change can affect your renewal. Ask for an explanation and compare the market.
Compare Houston Car Insurance Quotes Today
AZ Insurance Agency helps Houston drivers compare coverage from multiple carriers, including options for tickets, coverage gaps, and SR-22 filings. Speak with a bilingual agent online or visit one of the agency's Texas insurance locations to review your choices without cutting protection blindly.
Últimos Blogs

What Is Gap Insurance and What Does It Cover? Do You Need It?

What Is a Deductible in Car Insurance? A Simple Guide

Renovación de tu seguro de casa en Texas: 4 derechos que tienes en 2026 y qué solicitar
¿Le canceló su aseguradora de hogar en Texas? Lo que debe indicarle una notificación de no renovación y qué hacer en los próximos 60 días
La responsabilidad civil general no pagará por un error. Qué cubre la responsabilidad profesional en Texas
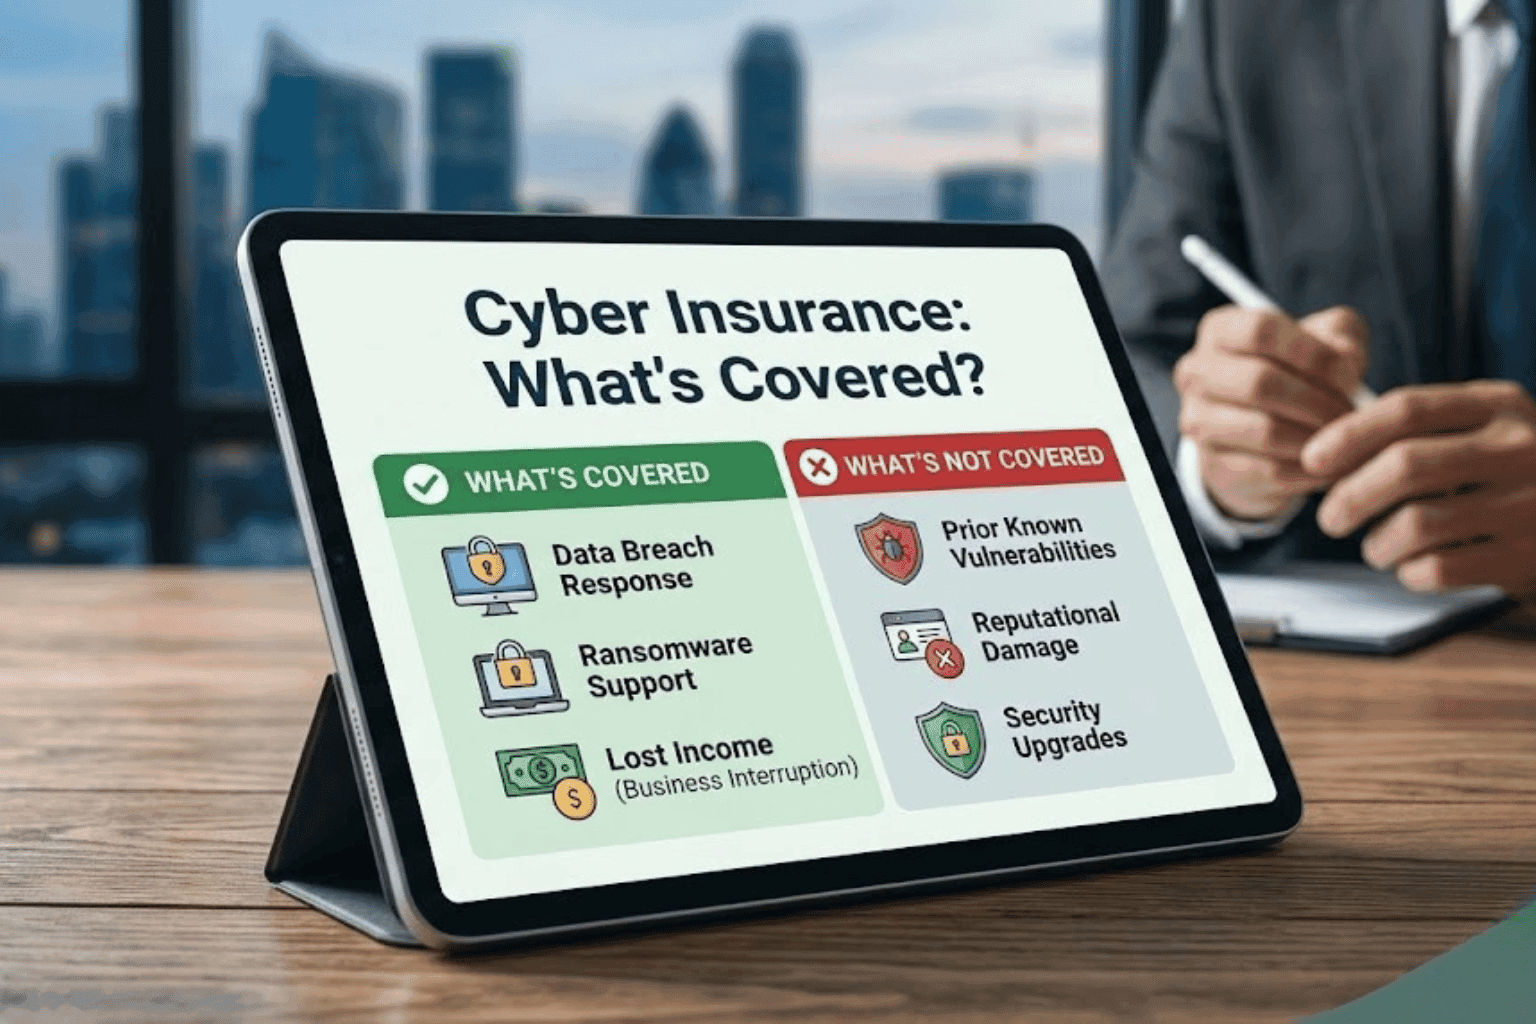
What Does Cyber Insurance Cover (and Not Cover)? Full Guide
Deja que A-Z Auto Insurance te ayude a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deje que A-Z Auto Insurance le ayude
A encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deja que A-Z Auto
Seguros te
ayude a encontrar cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deje que A-Z Auto Insurance le ayude
A encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Últimas noticias y blogs
Últimas noticias y blogs
Publicaciones de blog relacionadas
Publicaciones de blog relacionadas
Renovación de tu seguro de casa en Texas: 4 derechos que tienes en 2026 y qué solicitar
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
Renovación de tu seguro de casa en Texas: 4 derechos que tienes en 2026 y qué solicitar
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
Renovación de tu seguro de casa en Texas: 4 derechos que tienes en 2026 y qué solicitar
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
¿Le canceló su aseguradora de hogar en Texas? Lo que debe indicarle una notificación de no renovación y qué hacer en los próximos 60 días
Got a nonrenewal letter on your Texas home? The 60 day rule, the 2026 written reason law, the claims that cannot count against you, and your next moves.
¿Le canceló su aseguradora de hogar en Texas? Lo que debe indicarle una notificación de no renovación y qué hacer en los próximos 60 días
Got a nonrenewal letter on your Texas home? The 60 day rule, the 2026 written reason law, the claims that cannot count against you, and your next moves.
¿Le canceló su aseguradora de hogar en Texas? Lo que debe indicarle una notificación de no renovación y qué hacer en los próximos 60 días
Got a nonrenewal letter on your Texas home? The 60 day rule, the 2026 written reason law, the claims that cannot count against you, and your next moves.
La responsabilidad civil general no pagará por un error. Qué cubre la responsabilidad profesional en Texas
Tus respuestas de responsabilidad civil general para una escalera caída, no para un mal consejo o un plano incorrecto. Aquí es donde se define el límite en Texas, y la regla que hace que demandar a un diseñador sea más difícil aquí.
Renovación de tu seguro de casa en Texas: 4 derechos que tienes en 2026 y qué solicitar
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
¿Le canceló su aseguradora de hogar en Texas? Lo que debe indicarle una notificación de no renovación y qué hacer en los próximos 60 días
Got a nonrenewal letter on your Texas home? The 60 day rule, the 2026 written reason law, the claims that cannot count against you, and your next moves.