Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For

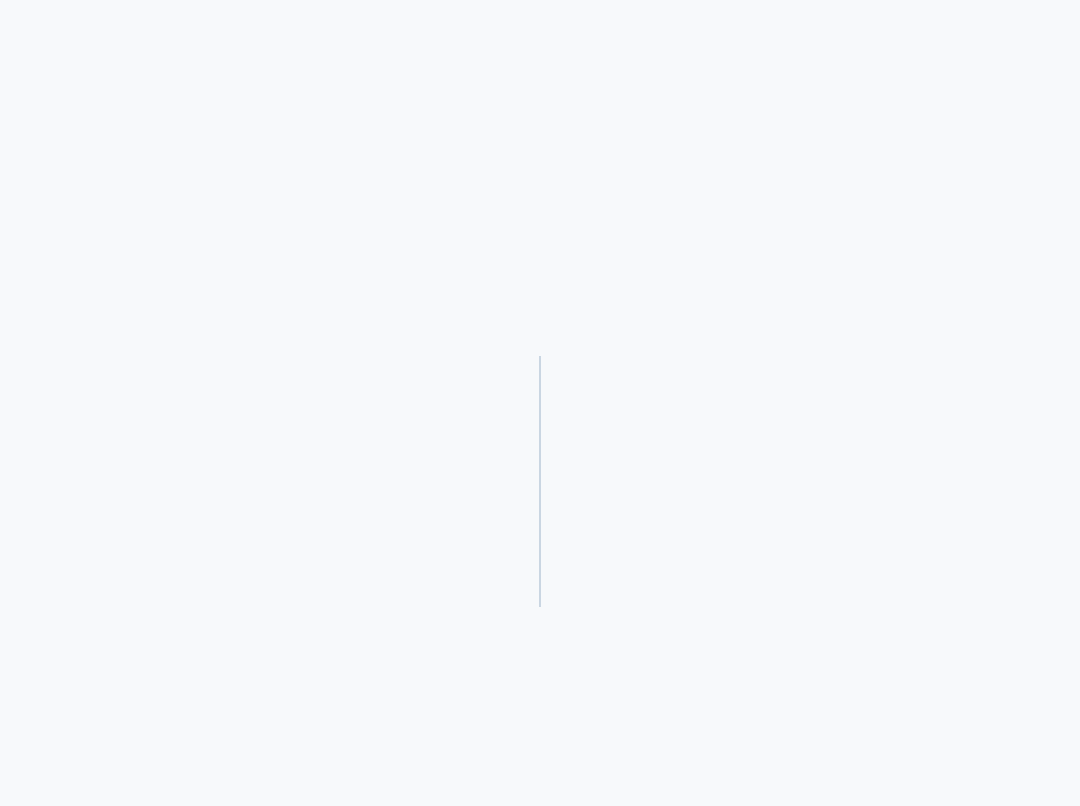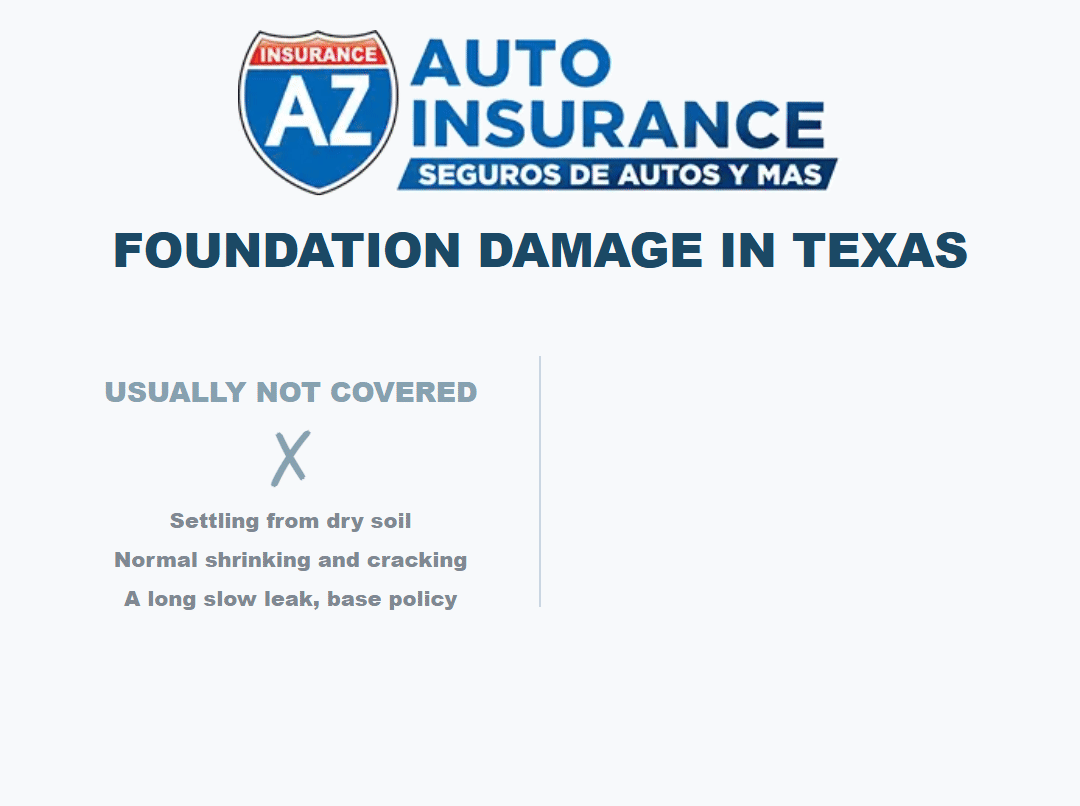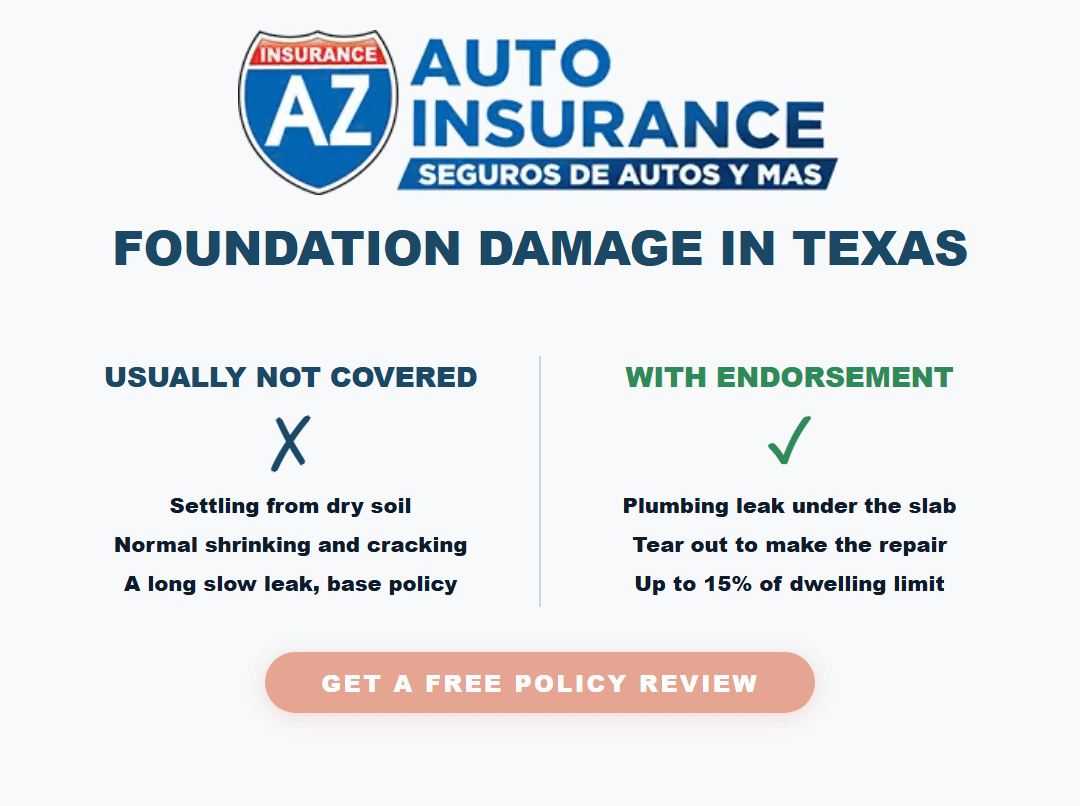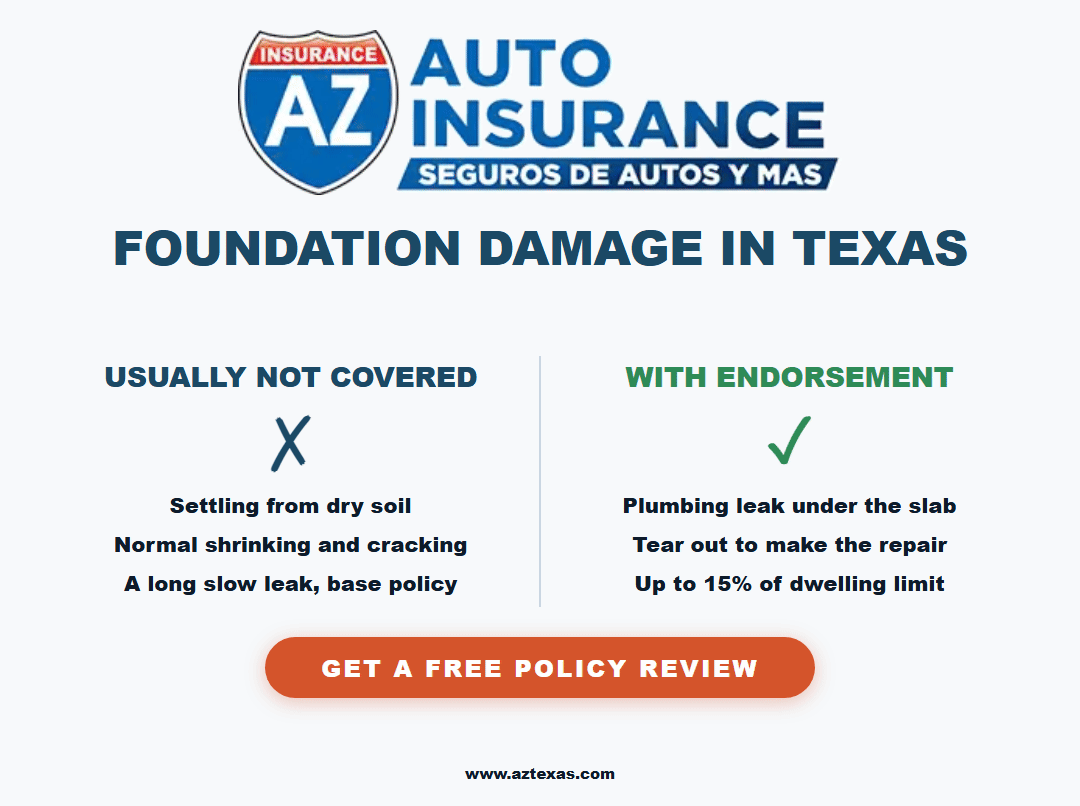
Quick Answer: A standard Texas homeowners policy usually does not cover foundation damage from settling, shrinking or soil movement. Damage caused by a plumbing leak under the slab can be covered, but on most national policy forms only with a foundation endorsement, which TDI approved with a limit of 15 percent of your dwelling coverage. Check your endorsement list.
Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
What this article covers
Why foundations are a Texas question
What a standard policy excludes
When foundation damage can be covered
The foundation endorsement, and its 15 percent limit
Older Texas HO-B policies
What to do if you see cracks
Frequently asked questions
A door that suddenly sticks. A crack running diagonally across the brick. A gap where the baseboard used to meet the floor. Every Texas homeowner knows the sinking feeling, and the first question is always the same: will my insurance pay for this?
The honest answer is "it depends on why it happened, and on one line in your policy." This guide explains both, so you can check your own coverage before you ever need it. If you would rather have someone read it with you, our team does that every day in a free home insurance policy review.
Key Takeaways
Settling, shrinking and soil movement are excluded on most policies. Normal foundation movement is treated as wear and maintenance, not a sudden accident.
A plumbing leak under the slab is the main way foundation damage gets covered, because the leak, not the soil, is the cause.
On most national forms that coverage needs a foundation endorsement. TDI approved the Texas version with a limit of 15 percent of your dwelling coverage.
The endorsement also pays to tear out and replace the parts of the house needed to make the repair, which is often the biggest cost.
Older Texas HO-B policies handled this differently, and TDI has said they cover foundation damage caused by an accidental plumbing leak.
The time to check is before you see a crack. Endorsements are added at purchase or renewal, not after the damage.
Why foundations are a Texas question
Many homes in the Houston area sit on a concrete slab poured directly on the ground, and much of Texas has clay soil that shrinks when it dries out and swells when it gets wet. A long dry summer followed by heavy rain can move a slab, especially at the edges. Because insurance treats that kind of movement as maintenance rather than an accident, the everyday habits in how to stay out of the home insurance doghouse matter here too.
That is why "does insurance cover my foundation" is one of the questions we hear most at our offices. It is also why this one coverage line matters more here than in most of the country.
What a standard policy excludes
Start with the base policy. When TDI approved the national ISO homeowners forms for use in Texas, its order noted that the HO 00 03 form "does not cover settling, shrinking, bulging or expansion, including resultant cracking" of foundations, walls, floors and similar parts of the house. Most company forms built on it carry a similar exclusion.
TDI's own home insurance guide makes a related point about water: most policies cover damage from a "sudden and accidental release of water," but most do not cover damage from "a continuous water leak." It lists damage to foundations or slabs among the coverages you add with an endorsement.
Cause of the foundation damage | Usually covered by the base policy? | Why |
|---|---|---|
Soil shrinking in a drought | No | Settling and shrinking are excluded |
Soil swelling after heavy rain | No | Expansion is excluded, and surface water is a flood issue |
Normal settling as the house ages | No | Treated as wear, not a sudden loss |
Tree roots pulling moisture from under the slab | No | Still soil movement |
A plumbing leak under the slab | Often only with an endorsement | The leak caused it, which is the covered angle |
Poor original construction | No | Faulty workmanship is generally excluded |
If water came from outside the house, such as rising water from a storm, that is a flood question, and a homeowners policy does not cover flood. We explain the difference in water damage vs flood and does homeowners insurance cover flood in Texas. If you have never priced a separate flood policy, our guide to NFIP vs private flood options in 2026 is a good place to start.
When foundation damage can be covered
The path to coverage almost always runs through plumbing. A supply line or drain line breaks or leaks under the slab, water saturates the soil, the soil moves, and the foundation cracks. In that chain, the cause is the leak.
Here is how the main scenarios usually play out.
A sudden pipe burst inside the house that damages floors and walls is commonly covered as a sudden and accidental release of water.
A slow leak under the slab that runs for months is the classic gap. The base policy excludes continuous leaks, and the resulting foundation movement is excluded as settling.
The same slow leak with a foundation endorsement can be covered, because the endorsement was written for exactly that situation.
Foundation cracks with no leak at all are generally not covered, endorsement or not, because the cause is the soil.
Plumbing claims have their own rules about the pipe itself, the water damage and the cost to reach the pipe, which we cover in does homeowners insurance cover plumbing. For the bigger picture of what a policy pays, see what homeowners insurance covers and does not cover.
Get a free home insurance policy review or call (281) 833-5060. Hablamos Español.
The foundation endorsement, and its 15 percent limit
When TDI approved the ISO forms in 2002, it also approved a Texas foundation endorsement and described it in the same order:
It "provides coverage for settling, cracking, shrinking, bulging, or expansion of foundations," floor slabs or footings that support the dwelling, when the cause is seepage or leakage of water or steam from within a plumbing, heating, air conditioning or automatic fire sprinkler system.
It "limits coverage to 15% of the amount of insurance for Coverage A-Dwelling on the date of loss."
It "includes the cost of tearing out and replacing any part of the building necessary to repair" the system the water escaped from.
As a condition of using those forms, TDI required companies to offer the foundation endorsement, a water damage endorsement and a limited fungi or microbes endorsement when each new policy is written, subject to the company's underwriting guidelines.
The 15 percent limit is easy to translate into dollars once you know your dwelling limit.
Your dwelling limit | Foundation endorsement limit at 15 percent |
|---|---|
$200,000 | $30,000 |
$300,000 | $45,000 |
$400,000 | $60,000 |
$500,000 | $75,000 |
Simple arithmetic for illustration. Your company's endorsement and its limit are what count, so check your own policy.
That tear out language matters. Getting to a leak under a slab can mean breaking up flooring, tunneling or opening the slab, and then putting the house back together. On many claims, that work costs more than the plumbing repair itself.
Two practical points. First, company forms vary, and not every company uses the same endorsement or the same limit, so read the actual name and limit on your endorsement list. Second, an endorsement is something you add when you buy or renew the policy, not after you find a crack. Your declarations page lists your endorsements, and our guide to reading your Texas home insurance declarations page shows where to find them.
Older Texas HO-B policies
Some long time Texas homeowners still have an HO-B, the older Texas standard form, or a company form modeled on it. These handled foundations differently.
In Commissioner's Bulletin B-0032-97, dated August 22, 1997, TDI stated its position that there is "coverage in the HO-B policy for damage to foundations resulting from accidental discharge," and that if accidental discharge causes a foundation to settle or crack, "the damage to the foundation is a covered loss." TDI said plainly that it did not agree with a federal court decision that had read the policy the other way.
If you are not sure which form you have, the form number is on your declarations page, and our comparison of HO-A vs HO-B vs HO-3 in Texas explains the differences. Before you switch from an older form to a newer one to save money, ask what happens to your foundation coverage in the move.
Policy type | Foundation damage from a plumbing leak | What to check |
|---|---|---|
Older Texas HO-B | TDI's position is that it is covered | That you still have the HO-B and not a newer form |
National HO-3 or similar company form | Usually only with a foundation endorsement | The endorsement name and its percentage limit |
HO-A or other named perils form | Very limited | Whether it is the right form for your home at all |
What to do if you see cracks
Not every crack means a claim, and not every claim is a foundation claim. Work through it in this order.
Check for a leak first. A water bill that jumped, a meter that spins with every tap closed, a warm spot on the floor or a damp patch are all signs of a slab leak. A licensed plumber can run a leak test.
Photograph everything with dates. Cracks in brick, gaps at doors and windows, uneven floors. Photos taken over a few weeks show whether the movement is growing.
Read your endorsement list. Look for a foundation endorsement, a water damage endorsement and the limit on each.
Call your agent before a repair company. A foundation company's inspection is useful, but your policy decides what is paid, and the order of events can matter.
Report a covered loss promptly. If a leak is the cause, report it to your insurer as soon as you know. Our guide to the storm claim timeline and what your insurer must do explains the deadlines Texas puts on the company once you file.
If the damage is to the house itself after a covered loss, the claim is paid under your dwelling coverage, and whether you get today's repair cost or a depreciated amount depends on your policy. See actual cash value vs replacement cost in Texas and how much dwelling coverage your Houston home needs, since a 15 percent endorsement limit is calculated from that dwelling number.
A quick checklist for your next renewal
Find the form number on your declarations page.
Look for a foundation endorsement and write down its limit.
Look for a water damage endorsement as well.
Confirm your dwelling limit still matches today's rebuild cost.
If you have neither endorsement, ask for a price on both.
If you are switching companies, ask what happens to foundation coverage in the switch.
If you are shopping, your new company will ask for the same basic information about the house, which we list in information needed for a homeowners insurance quote. And if your renewal brought other changes at the same time, our guide to your Texas home insurance renewal rights in 2026 covers what your insurer has to tell you.
Frequently asked questions
Q: Does homeowners insurance cover foundation damage in Texas?
Usually not when the cause is settling, shrinking or soil movement, which most policies exclude. Damage caused by a plumbing leak under the slab can be covered, and on most national policy forms that coverage comes from a foundation endorsement.
Q: What is a foundation endorsement?
An add on to your homeowners policy that covers settling, cracking, shrinking, bulging or expansion of the foundation when the cause is water or steam leaking from a plumbing, heating, air conditioning or sprinkler system. The Texas version TDI approved in 2002 is limited to 15 percent of your dwelling coverage and includes the cost of tearing out and replacing parts of the house to make the repair.
Q: Does insurance cover foundation damage from drought or clay soil?
Generally no. Soil shrinking and swelling is treated as settling or expansion, which is excluded, even with a foundation endorsement, because the endorsement covers damage caused by a leak, not by the soil itself.
Q: Is a slab leak covered by homeowners insurance?
A sudden release of water is commonly covered, but most policies exclude a continuous leak, and the foundation movement it causes is excluded as settling. A foundation endorsement and a water damage endorsement are what usually close that gap. Check your own endorsement list.
Q: Can I add foundation coverage after I find a crack?
Coverage applies to losses that happen while the endorsement is on your policy, so adding it after the damage does not cover existing damage. Add it at purchase or renewal, before you need it.
Q: I have an older HO-B policy. Is my foundation covered?
TDI's 1997 bulletin states its position that the HO-B covers foundation damage resulting from an accidental discharge of water, such as a plumbing leak. Confirm with your agent that you still have the HO-B form before you rely on it.
Related Articles
Why AZ Insurance Stands Apart
Foundation coverage is decided long before the crack shows up: by the form you bought, the endorsements on it, and the dwelling limit the percentage is based on. That is exactly the kind of detail we look for when we review a policy. AZ Insurance has served Texas homeowners since 2003 from 15 offices across Houston and Dallas, we compare multiple insurance companies rather than defending one, and our agents explain it in English or Spanish.
Bring us your policy and we will tell you, in plain language, what your foundation coverage looks like today. Request a free home insurance policy review or call our homeowners line at (281) 833-5060.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. We are happy to read it with you.
Quick Answer: A standard Texas homeowners policy usually does not cover foundation damage from settling, shrinking or soil movement. Damage caused by a plumbing leak under the slab can be covered, but on most national policy forms only with a foundation endorsement, which TDI approved with a limit of 15 percent of your dwelling coverage. Check your endorsement list.
Reviewed by AZ Insurance Agency, licensed in Texas, serving Houston since 2003.
What this article covers
Why foundations are a Texas question
What a standard policy excludes
When foundation damage can be covered
The foundation endorsement, and its 15 percent limit
Older Texas HO-B policies
What to do if you see cracks
Frequently asked questions
A door that suddenly sticks. A crack running diagonally across the brick. A gap where the baseboard used to meet the floor. Every Texas homeowner knows the sinking feeling, and the first question is always the same: will my insurance pay for this?
The honest answer is "it depends on why it happened, and on one line in your policy." This guide explains both, so you can check your own coverage before you ever need it. If you would rather have someone read it with you, our team does that every day in a free home insurance policy review.
Key Takeaways
Settling, shrinking and soil movement are excluded on most policies. Normal foundation movement is treated as wear and maintenance, not a sudden accident.
A plumbing leak under the slab is the main way foundation damage gets covered, because the leak, not the soil, is the cause.
On most national forms that coverage needs a foundation endorsement. TDI approved the Texas version with a limit of 15 percent of your dwelling coverage.
The endorsement also pays to tear out and replace the parts of the house needed to make the repair, which is often the biggest cost.
Older Texas HO-B policies handled this differently, and TDI has said they cover foundation damage caused by an accidental plumbing leak.
The time to check is before you see a crack. Endorsements are added at purchase or renewal, not after the damage.
Why foundations are a Texas question
Many homes in the Houston area sit on a concrete slab poured directly on the ground, and much of Texas has clay soil that shrinks when it dries out and swells when it gets wet. A long dry summer followed by heavy rain can move a slab, especially at the edges. Because insurance treats that kind of movement as maintenance rather than an accident, the everyday habits in how to stay out of the home insurance doghouse matter here too.
That is why "does insurance cover my foundation" is one of the questions we hear most at our offices. It is also why this one coverage line matters more here than in most of the country.
What a standard policy excludes
Start with the base policy. When TDI approved the national ISO homeowners forms for use in Texas, its order noted that the HO 00 03 form "does not cover settling, shrinking, bulging or expansion, including resultant cracking" of foundations, walls, floors and similar parts of the house. Most company forms built on it carry a similar exclusion.
TDI's own home insurance guide makes a related point about water: most policies cover damage from a "sudden and accidental release of water," but most do not cover damage from "a continuous water leak." It lists damage to foundations or slabs among the coverages you add with an endorsement.
Cause of the foundation damage | Usually covered by the base policy? | Why |
|---|---|---|
Soil shrinking in a drought | No | Settling and shrinking are excluded |
Soil swelling after heavy rain | No | Expansion is excluded, and surface water is a flood issue |
Normal settling as the house ages | No | Treated as wear, not a sudden loss |
Tree roots pulling moisture from under the slab | No | Still soil movement |
A plumbing leak under the slab | Often only with an endorsement | The leak caused it, which is the covered angle |
Poor original construction | No | Faulty workmanship is generally excluded |
If water came from outside the house, such as rising water from a storm, that is a flood question, and a homeowners policy does not cover flood. We explain the difference in water damage vs flood and does homeowners insurance cover flood in Texas. If you have never priced a separate flood policy, our guide to NFIP vs private flood options in 2026 is a good place to start.
When foundation damage can be covered
The path to coverage almost always runs through plumbing. A supply line or drain line breaks or leaks under the slab, water saturates the soil, the soil moves, and the foundation cracks. In that chain, the cause is the leak.
Here is how the main scenarios usually play out.
A sudden pipe burst inside the house that damages floors and walls is commonly covered as a sudden and accidental release of water.
A slow leak under the slab that runs for months is the classic gap. The base policy excludes continuous leaks, and the resulting foundation movement is excluded as settling.
The same slow leak with a foundation endorsement can be covered, because the endorsement was written for exactly that situation.
Foundation cracks with no leak at all are generally not covered, endorsement or not, because the cause is the soil.
Plumbing claims have their own rules about the pipe itself, the water damage and the cost to reach the pipe, which we cover in does homeowners insurance cover plumbing. For the bigger picture of what a policy pays, see what homeowners insurance covers and does not cover.
Get a free home insurance policy review or call (281) 833-5060. Hablamos Español.
The foundation endorsement, and its 15 percent limit
When TDI approved the ISO forms in 2002, it also approved a Texas foundation endorsement and described it in the same order:
It "provides coverage for settling, cracking, shrinking, bulging, or expansion of foundations," floor slabs or footings that support the dwelling, when the cause is seepage or leakage of water or steam from within a plumbing, heating, air conditioning or automatic fire sprinkler system.
It "limits coverage to 15% of the amount of insurance for Coverage A-Dwelling on the date of loss."
It "includes the cost of tearing out and replacing any part of the building necessary to repair" the system the water escaped from.
As a condition of using those forms, TDI required companies to offer the foundation endorsement, a water damage endorsement and a limited fungi or microbes endorsement when each new policy is written, subject to the company's underwriting guidelines.
The 15 percent limit is easy to translate into dollars once you know your dwelling limit.
Your dwelling limit | Foundation endorsement limit at 15 percent |
|---|---|
$200,000 | $30,000 |
$300,000 | $45,000 |
$400,000 | $60,000 |
$500,000 | $75,000 |
Simple arithmetic for illustration. Your company's endorsement and its limit are what count, so check your own policy.
That tear out language matters. Getting to a leak under a slab can mean breaking up flooring, tunneling or opening the slab, and then putting the house back together. On many claims, that work costs more than the plumbing repair itself.
Two practical points. First, company forms vary, and not every company uses the same endorsement or the same limit, so read the actual name and limit on your endorsement list. Second, an endorsement is something you add when you buy or renew the policy, not after you find a crack. Your declarations page lists your endorsements, and our guide to reading your Texas home insurance declarations page shows where to find them.
Older Texas HO-B policies
Some long time Texas homeowners still have an HO-B, the older Texas standard form, or a company form modeled on it. These handled foundations differently.
In Commissioner's Bulletin B-0032-97, dated August 22, 1997, TDI stated its position that there is "coverage in the HO-B policy for damage to foundations resulting from accidental discharge," and that if accidental discharge causes a foundation to settle or crack, "the damage to the foundation is a covered loss." TDI said plainly that it did not agree with a federal court decision that had read the policy the other way.
If you are not sure which form you have, the form number is on your declarations page, and our comparison of HO-A vs HO-B vs HO-3 in Texas explains the differences. Before you switch from an older form to a newer one to save money, ask what happens to your foundation coverage in the move.
Policy type | Foundation damage from a plumbing leak | What to check |
|---|---|---|
Older Texas HO-B | TDI's position is that it is covered | That you still have the HO-B and not a newer form |
National HO-3 or similar company form | Usually only with a foundation endorsement | The endorsement name and its percentage limit |
HO-A or other named perils form | Very limited | Whether it is the right form for your home at all |
What to do if you see cracks
Not every crack means a claim, and not every claim is a foundation claim. Work through it in this order.
Check for a leak first. A water bill that jumped, a meter that spins with every tap closed, a warm spot on the floor or a damp patch are all signs of a slab leak. A licensed plumber can run a leak test.
Photograph everything with dates. Cracks in brick, gaps at doors and windows, uneven floors. Photos taken over a few weeks show whether the movement is growing.
Read your endorsement list. Look for a foundation endorsement, a water damage endorsement and the limit on each.
Call your agent before a repair company. A foundation company's inspection is useful, but your policy decides what is paid, and the order of events can matter.
Report a covered loss promptly. If a leak is the cause, report it to your insurer as soon as you know. Our guide to the storm claim timeline and what your insurer must do explains the deadlines Texas puts on the company once you file.
If the damage is to the house itself after a covered loss, the claim is paid under your dwelling coverage, and whether you get today's repair cost or a depreciated amount depends on your policy. See actual cash value vs replacement cost in Texas and how much dwelling coverage your Houston home needs, since a 15 percent endorsement limit is calculated from that dwelling number.
A quick checklist for your next renewal
Find the form number on your declarations page.
Look for a foundation endorsement and write down its limit.
Look for a water damage endorsement as well.
Confirm your dwelling limit still matches today's rebuild cost.
If you have neither endorsement, ask for a price on both.
If you are switching companies, ask what happens to foundation coverage in the switch.
If you are shopping, your new company will ask for the same basic information about the house, which we list in information needed for a homeowners insurance quote. And if your renewal brought other changes at the same time, our guide to your Texas home insurance renewal rights in 2026 covers what your insurer has to tell you.
Frequently asked questions
Q: Does homeowners insurance cover foundation damage in Texas?
Usually not when the cause is settling, shrinking or soil movement, which most policies exclude. Damage caused by a plumbing leak under the slab can be covered, and on most national policy forms that coverage comes from a foundation endorsement.
Q: What is a foundation endorsement?
An add on to your homeowners policy that covers settling, cracking, shrinking, bulging or expansion of the foundation when the cause is water or steam leaking from a plumbing, heating, air conditioning or sprinkler system. The Texas version TDI approved in 2002 is limited to 15 percent of your dwelling coverage and includes the cost of tearing out and replacing parts of the house to make the repair.
Q: Does insurance cover foundation damage from drought or clay soil?
Generally no. Soil shrinking and swelling is treated as settling or expansion, which is excluded, even with a foundation endorsement, because the endorsement covers damage caused by a leak, not by the soil itself.
Q: Is a slab leak covered by homeowners insurance?
A sudden release of water is commonly covered, but most policies exclude a continuous leak, and the foundation movement it causes is excluded as settling. A foundation endorsement and a water damage endorsement are what usually close that gap. Check your own endorsement list.
Q: Can I add foundation coverage after I find a crack?
Coverage applies to losses that happen while the endorsement is on your policy, so adding it after the damage does not cover existing damage. Add it at purchase or renewal, before you need it.
Q: I have an older HO-B policy. Is my foundation covered?
TDI's 1997 bulletin states its position that the HO-B covers foundation damage resulting from an accidental discharge of water, such as a plumbing leak. Confirm with your agent that you still have the HO-B form before you rely on it.
Related Articles
Why AZ Insurance Stands Apart
Foundation coverage is decided long before the crack shows up: by the form you bought, the endorsements on it, and the dwelling limit the percentage is based on. That is exactly the kind of detail we look for when we review a policy. AZ Insurance has served Texas homeowners since 2003 from 15 offices across Houston and Dallas, we compare multiple insurance companies rather than defending one, and our agents explain it in English or Spanish.
Bring us your policy and we will tell you, in plain language, what your foundation coverage looks like today. Request a free home insurance policy review or call our homeowners line at (281) 833-5060.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. We are happy to read it with you.
Latest Blogs

How to Read Your Texas Home Insurance Declarations Page, Line by Line

How to Lower Car Insurance: 10 Practical Ways to Pay Less

What Is Gap Insurance and What Does It Cover? Do You Need It?

What Is a Deductible in Car Insurance? A Simple Guide

Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
Dropped by Your Texas Home Insurer? What a Nonrenewal Notice Must Tell You and What to Do in the Next 60 Days
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
What Is Gap Insurance and What Does It Cover? Do You Need It?
What is gap insurance and what does it cover? Learn how gap coverage pays off your car loan after a total loss, what it costs, and if you need it.
What Is Gap Insurance and What Does It Cover? Do You Need It?
What is gap insurance and what does it cover? Learn how gap coverage pays off your car loan after a total loss, what it costs, and if you need it.
What Is Gap Insurance and What Does It Cover? Do You Need It?
What is gap insurance and what does it cover? Learn how gap coverage pays off your car loan after a total loss, what it costs, and if you need it.
What Is a Deductible in Car Insurance? A Simple Guide
What is a deductible in car insurance? Learn how deductibles work, which coverages have one, and how to pick the right amount for your budget in Texas.
What Is a Deductible in Car Insurance? A Simple Guide
What is a deductible in car insurance? Learn how deductibles work, which coverages have one, and how to pick the right amount for your budget in Texas.
What Is a Deductible in Car Insurance? A Simple Guide
What is a deductible in car insurance? Learn how deductibles work, which coverages have one, and how to pick the right amount for your budget in Texas.
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
Your Texas Home Insurance Renewal: 4 Rights You Have in 2026 and What to Ask For
At renewal you can ask for a credit recheck, say no to a forced bundle, and cannot be charged more for being widowed. What changed on Sept 16, and what did not.
What Is Gap Insurance and What Does It Cover? Do You Need It?
What is gap insurance and what does it cover? Learn how gap coverage pays off your car loan after a total loss, what it costs, and if you need it.
What Is a Deductible in Car Insurance? A Simple Guide
What is a deductible in car insurance? Learn how deductibles work, which coverages have one, and how to pick the right amount for your budget in Texas.