Soporte rápido de profesionales de seguros de confianza Llame +1 713-777-2886 hoy!
¡Llame hoy al +1 713-777-2886 para obtener un soporte profesional rápido!
¡Llame hoy al +1 713-777-2886 para obtener un soporte profesional rápido!
Tabla de Contenido
Título
Deje que AZ Insurance le ayude
a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deja que A-Z Auto Insurance te ayude a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)
What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)
What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)
What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)
What Does an Umbrella Insurance Policy Cover? (And What It Doesn't)

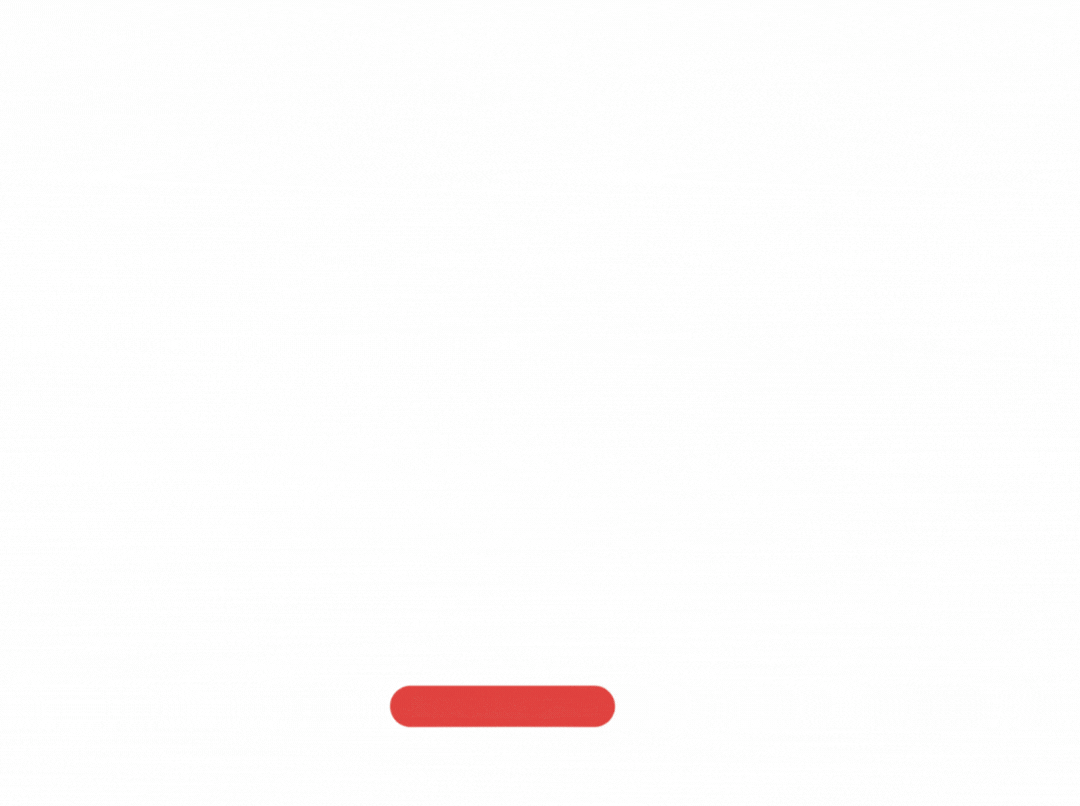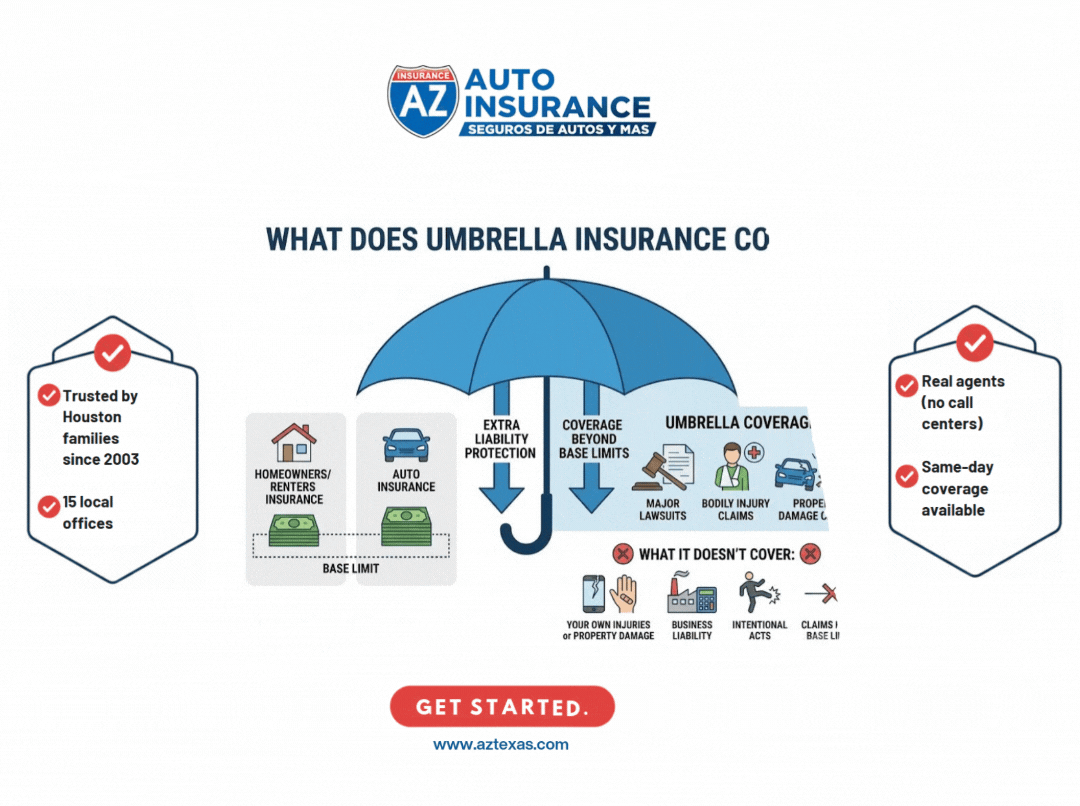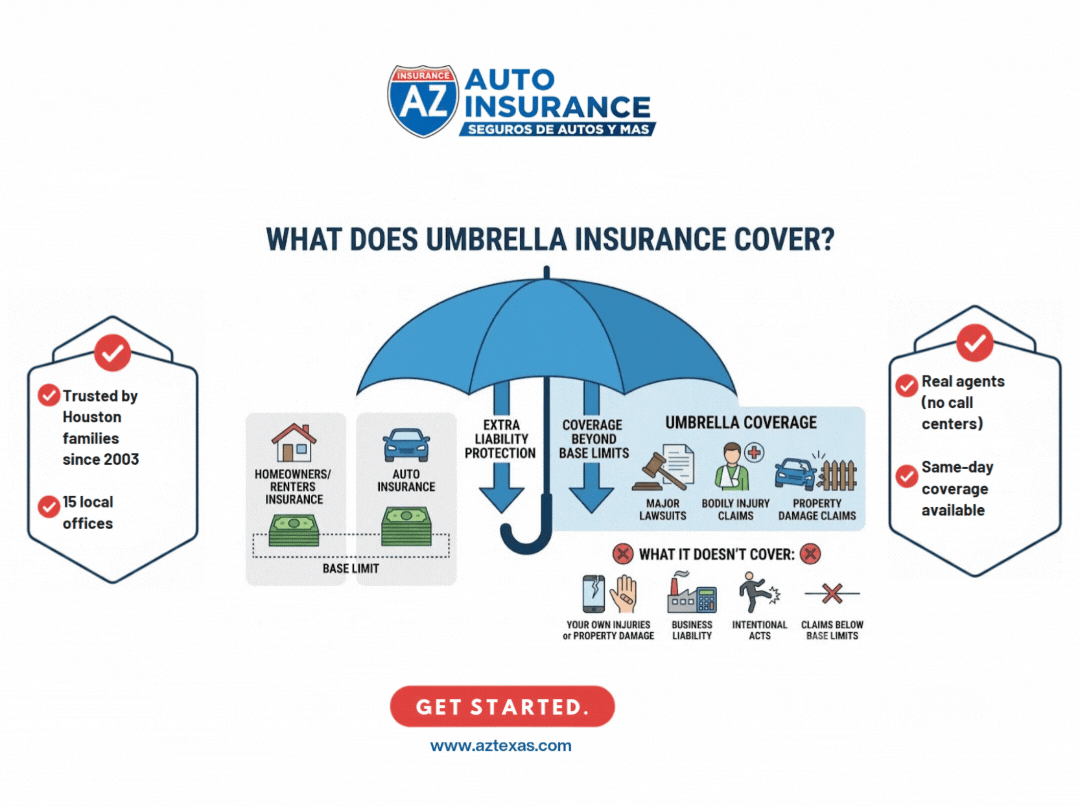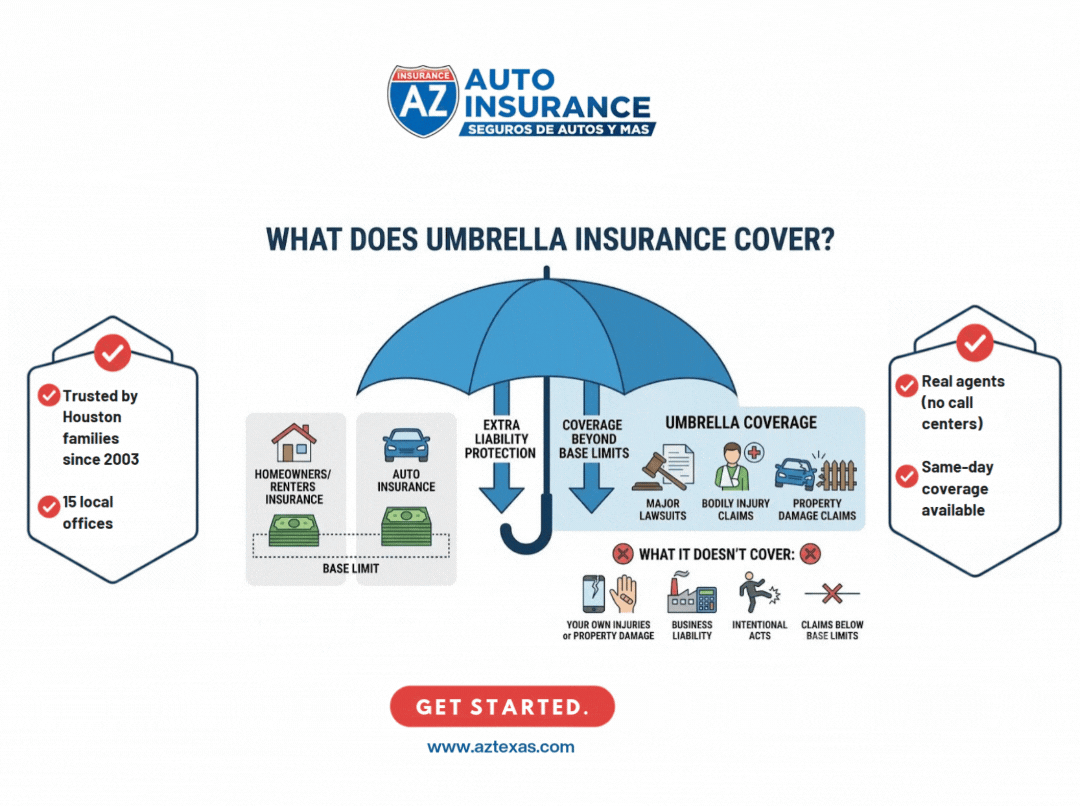
Quick Answer: An umbrella insurance policy provides extra liability coverage beyond the limits of your home, auto, or renters insurance, protecting you from major lawsuits, injury claims, and property damage claims that exceed those base policies. It does not cover your own property damage, business liabilities, or intentional acts — it only extends liability protection once your underlying policy limits are used up.
A single serious car accident or a lawsuit after an injury on your property can easily exceed the liability limits on your auto or homeowners' policy. That's where umbrella insurance comes in — an extra layer of protection that sits on top of your existing coverage.
If you've been asking what does an umbrella insurance policy cover, this guide breaks down exactly what's included, real-world examples of what does umbrella liability insurance covers, and where the coverage stops.
What Does an Umbrella Insurance Policy Cover?
Coverage | Details |
Bodily injury liability | Extra protection if you're sued for injuries you caused to someone else |
Property damage liability | Covers damage to others' property beyond your auto or home policy limits |
Personal liability | Covers claims like libel, slander, or false arrest |
Legal defense costs | Covers attorney fees even if a claim against you is later dismissed |
Extra protection for owners of rental property. |
What Does Umbrella Liability Insurance Cover in Everyday Situations?
A serious car accident: If you're at fault in a crash that causes injuries exceeding your auto policy liability limit, umbrella coverage picks up the remaining costs.
A dog bite lawsuit: If a visitor is bitten by your dog and sues damage beyond your homeowner's liability limit, umbrella coverage extends protection.
A guest injured at your home: A serious fall or injury during a gathering that leads to a large claim is exactly the scenario umbrella insurance is built for.
A teen driver at-fault accident: Young, less experienced drivers statistically increase liability risk, making umbrella coverage especially valuable for families with teen drivers.
What Does Umbrella Insurance NOT Cover?
Exclusion | Why It's Excluded |
Your own injuries or property | Umbrella policies cover liability to others, not first-party losses |
Business risks generally require a separate commercial policy | |
Intentional acts | Deliberate harm caused by the policyholder isn't covered |
Contractual liability | Obligations you take on in a contract aren't automatically included |
Claims below your underlying limits | Umbrella coverage only applies after your home or auto policy limit is exhausted |
Do You Need Umbrella Insurance in Texas?
Texas is a high-litigation state, and Houston's dense traffic, active social scenes, and popularity of backyard pools all add to everyday liability exposure. Families with teen drivers, rental property owners, pool owners, and anyone with meaningful savings or home equity to protect are especially good candidates for an umbrella policy.
Because umbrella coverage is priced against your underlying auto and home policies rather than as a standalone risk, it's often one of the most affordable ways to add substantial liability protection.
Frequently Asked Questions
What does an umbrella insurance policy cover?
It covers liability claims that exceed your home, auto, or renters insurance limits, including bodily injury, property damage, and certain personal liability claims like libel or slander.
What does umbrella liability insurance cover that my auto policy doesn't?
It covers the gap between your auto policy's liability limit and the full cost of a serious claim, such as a major injury lawsuit after an at-fault accident.
What does umbrella insurance not cover?
It does not cover your own injuries or property damage, business liability, intentional acts, or any claim amount below your underlying policy limit.
How much umbrella insurance coverage do I need?
Most advisors recommend coverage that at least matches your total net worth, with $1 million as a common starting point for many households.
Is umbrella insurance expensive?
No — because it sits on top of existing auto and home coverage; umbrella policies are often surprisingly affordable, frequently a few hundred dollars per year for $1 million in coverage.
Do I need both auto and homeowners' insurance to get umbrella coverage?
Most insurers require you to carry underlying auto and homeowners (or renters) policies with minimum liability limits before adding an umbrella policy on top.
Get a Quote in Houston Today
AZ Insurance Agency helps Texas families and business owners find the right coverage at the right price, with bilingual support at 15 Houston-area locations plus Plano and Lewisville.
Quick Answer: An umbrella insurance policy provides extra liability coverage beyond the limits of your home, auto, or renters insurance, protecting you from major lawsuits, injury claims, and property damage claims that exceed those base policies. It does not cover your own property damage, business liabilities, or intentional acts — it only extends liability protection once your underlying policy limits are used up.
A single serious car accident or a lawsuit after an injury on your property can easily exceed the liability limits on your auto or homeowners' policy. That's where umbrella insurance comes in — an extra layer of protection that sits on top of your existing coverage.
If you've been asking what does an umbrella insurance policy cover, this guide breaks down exactly what's included, real-world examples of what does umbrella liability insurance covers, and where the coverage stops.
What Does an Umbrella Insurance Policy Cover?
Coverage | Details |
Bodily injury liability | Extra protection if you're sued for injuries you caused to someone else |
Property damage liability | Covers damage to others' property beyond your auto or home policy limits |
Personal liability | Covers claims like libel, slander, or false arrest |
Legal defense costs | Covers attorney fees even if a claim against you is later dismissed |
Extra protection for owners of rental property. |
What Does Umbrella Liability Insurance Cover in Everyday Situations?
A serious car accident: If you're at fault in a crash that causes injuries exceeding your auto policy liability limit, umbrella coverage picks up the remaining costs.
A dog bite lawsuit: If a visitor is bitten by your dog and sues damage beyond your homeowner's liability limit, umbrella coverage extends protection.
A guest injured at your home: A serious fall or injury during a gathering that leads to a large claim is exactly the scenario umbrella insurance is built for.
A teen driver at-fault accident: Young, less experienced drivers statistically increase liability risk, making umbrella coverage especially valuable for families with teen drivers.
What Does Umbrella Insurance NOT Cover?
Exclusion | Why It's Excluded |
Your own injuries or property | Umbrella policies cover liability to others, not first-party losses |
Business risks generally require a separate commercial policy | |
Intentional acts | Deliberate harm caused by the policyholder isn't covered |
Contractual liability | Obligations you take on in a contract aren't automatically included |
Claims below your underlying limits | Umbrella coverage only applies after your home or auto policy limit is exhausted |
Do You Need Umbrella Insurance in Texas?
Texas is a high-litigation state, and Houston's dense traffic, active social scenes, and popularity of backyard pools all add to everyday liability exposure. Families with teen drivers, rental property owners, pool owners, and anyone with meaningful savings or home equity to protect are especially good candidates for an umbrella policy.
Because umbrella coverage is priced against your underlying auto and home policies rather than as a standalone risk, it's often one of the most affordable ways to add substantial liability protection.
Frequently Asked Questions
What does an umbrella insurance policy cover?
It covers liability claims that exceed your home, auto, or renters insurance limits, including bodily injury, property damage, and certain personal liability claims like libel or slander.
What does umbrella liability insurance cover that my auto policy doesn't?
It covers the gap between your auto policy's liability limit and the full cost of a serious claim, such as a major injury lawsuit after an at-fault accident.
What does umbrella insurance not cover?
It does not cover your own injuries or property damage, business liability, intentional acts, or any claim amount below your underlying policy limit.
How much umbrella insurance coverage do I need?
Most advisors recommend coverage that at least matches your total net worth, with $1 million as a common starting point for many households.
Is umbrella insurance expensive?
No — because it sits on top of existing auto and home coverage; umbrella policies are often surprisingly affordable, frequently a few hundred dollars per year for $1 million in coverage.
Do I need both auto and homeowners' insurance to get umbrella coverage?
Most insurers require you to carry underlying auto and homeowners (or renters) policies with minimum liability limits before adding an umbrella policy on top.
Get a Quote in Houston Today
AZ Insurance Agency helps Texas families and business owners find the right coverage at the right price, with bilingual support at 15 Houston-area locations plus Plano and Lewisville.
Últimos Blogs
How Much Does Flood Insurance Cost in Texas? (2026 Pricing Guide)
¿BOP o Responsabilidad Civil General? ¿Y necesitas alguno de los dos si no tienes empleados?

How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)

Qué puede realmente cancelar o anular tu póliza de responsabilidad civil general en Texas
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Average Hazard Insurance Cost: What Homeowners Can Expect
Deja que A-Z Auto Insurance te ayude a encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deje que A-Z Auto Insurance le ayude
A encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deja que A-Z Auto
Seguros te
ayude a encontrar cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Deje que A-Z Auto Insurance le ayude
A encontrar una cobertura asequible
Conéctate con nuestro equipo experimentado hoy y obtén un seguro confiable y asequible diseñado a tu medida.
¡Contáctanos!
Últimas noticias y blogs
Últimas noticias y blogs
Publicaciones de blog relacionadas
Publicaciones de blog relacionadas
How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)
Wondering how much a surety bond costs in Texas? See average premiums, what affects your rate, and how credit score impacts pricing.
How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)
Wondering how much a surety bond costs in Texas? See average premiums, what affects your rate, and how credit score impacts pricing.
How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)
Wondering how much a surety bond costs in Texas? See average premiums, what affects your rate, and how credit score impacts pricing.
Qué puede realmente cancelar o anular tu póliza de responsabilidad civil general en Texas
After 60 days a Texas insurer can only cancel your general liability for five reasons. Unless you are on surplus lines, where none of those protections apply.
Qué puede realmente cancelar o anular tu póliza de responsabilidad civil general en Texas
After 60 days a Texas insurer can only cancel your general liability for five reasons. Unless you are on surplus lines, where none of those protections apply.
Qué puede realmente cancelar o anular tu póliza de responsabilidad civil general en Texas
After 60 days a Texas insurer can only cancel your general liability for five reasons. Unless you are on surplus lines, where none of those protections apply.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
Hazard Insurance vs. Homeowners Insurance: What's the Difference?
Confused about hazard insurance vs homeowners' insurance? Learn the real difference, what each cover, & which one your Texas mortgage requires.
How Much Does a Surety Bond Cost in Texas? (Rates & Pricing Guide)
Wondering how much a surety bond costs in Texas? See average premiums, what affects your rate, and how credit score impacts pricing.
Qué puede realmente cancelar o anular tu póliza de responsabilidad civil general en Texas
After 60 days a Texas insurer can only cancel your general liability for five reasons. Unless you are on surplus lines, where none of those protections apply.