Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing

Quick Answer: About 1 in 8 Texas drivers is uninsured, per the TxDMV estimate of 11.87 percent. If one hits you, uninsured and underinsured motorist coverage pays your car repairs, medical bills and pain and suffering, with a $250 deductible. Texas puts UM/UIM and PIP on every policy unless someone rejected them in writing.
What this article covers
The number behind the fear
What UM/UIM actually pays
Uninsured, underinsured and hit and run
The box you may have rejected years ago
PIP, the other coverage Texas includes unless you say no
Can I switch before my renewal date?
Frequently asked questions
A driver in Baytown is stopped at a light on Garth Road when a pickup rear ends her. Nobody is hurt badly, but her back is sore for weeks and the trunk will not close. The other driver is apologetic, and he has no insurance.
The police report says he was at fault. That part is easy. The hard part is that "at fault" only helps if there is a policy on the other side to pay. When there is not, a judgment against the other driver is only worth what that driver can actually pay.
What decides her next month is not his policy. It is one line on hers.
Key Takeaways
An estimated 11.87 percent of Texas drivers are uninsured, according to the Texas Department of Motor Vehicles, as of September 2025. That is about 1 in 8.
Uninsured and underinsured motorist coverage, UM/UIM, pays you when the at fault driver cannot, including your medical bills, car repairs, a rental and pain and suffering.
The UM/UIM deductible is $250, per the Texas Department of Insurance. A collision deductible is usually much higher.
Texas insurers must include UM/UIM and PIP. They come off your policy only if someone named on it rejected them in writing.
A rejection signed years ago usually follows the policy through every renewal until someone asks, in writing, to put the coverage back.
You can change auto insurance before your renewal date. Start the new policy first, then cancel the old one.
The number behind the fear
The Texas Department of Motor Vehicles runs TexasSure, the state's insurance verification database. On its TexasSure page it says: "Currently, an estimated 11.87 percent of Texas drivers are uninsured (as of September 2025)."
You will see other numbers quoted online. We use the state's figure because it comes from the state's own verification database. At that number, roughly one car in eight around you on I-10 or US 59 has nobody behind it to pay if it hits you.
That is also why Texas checks insurance at registration, which we covered in do you need insurance before registering a car in Texas. Checking does not mean every driver keeps the policy afterward.
It also helps to separate the two questions people mix up. Your own liability insurance exists to pay for damage you cause to others, the basics of which we laid out in what is the main purpose of having auto insurance. This article is about the opposite situation: damage somebody else causes to you, when their liability insurance is missing or too small.
What UM/UIM actually pays
The Texas Department of Insurance lists it plainly on its uninsured motorist page. UM/UIM pays for:
Car repairs and replacing the property in your car
A rental car if you need it
Your and your passengers' medical bills
Pain and suffering
Diminished value if your car is worth less after the accident
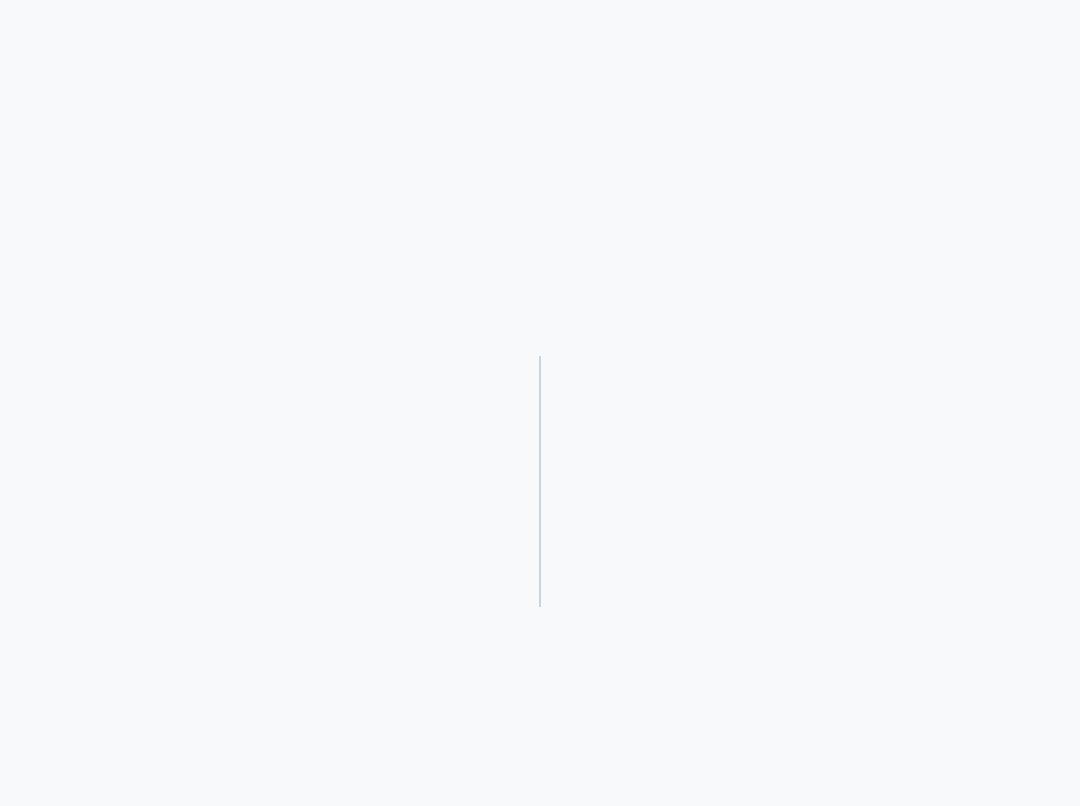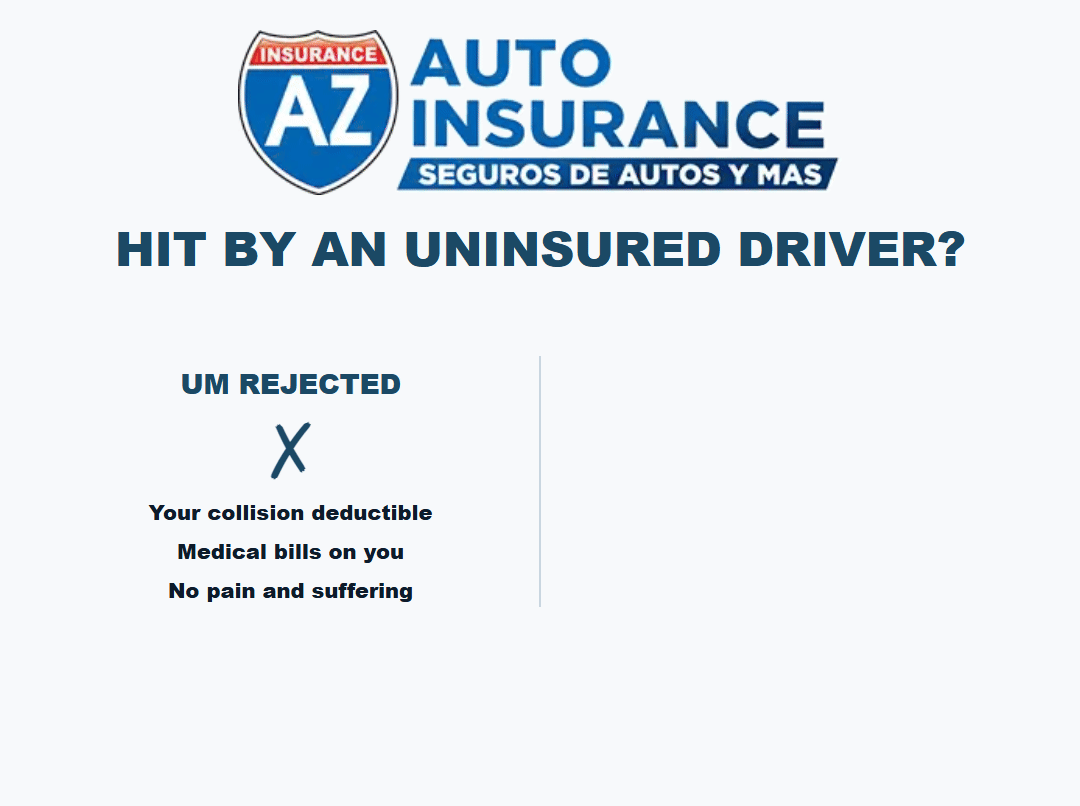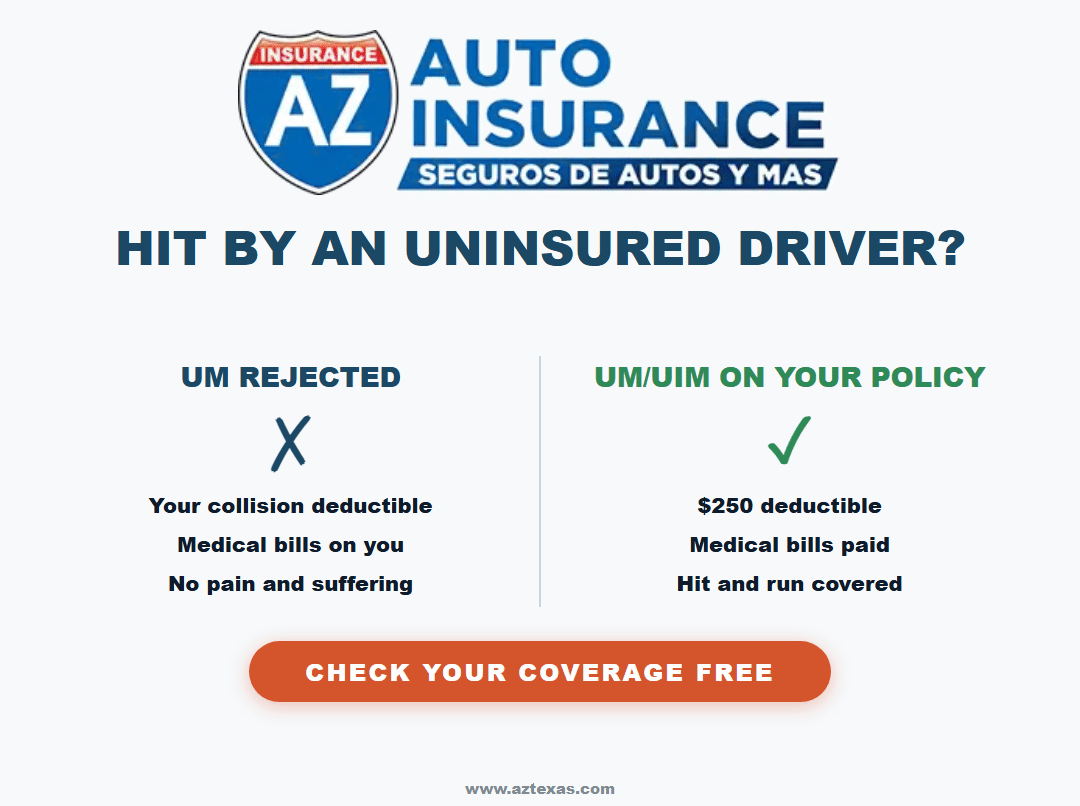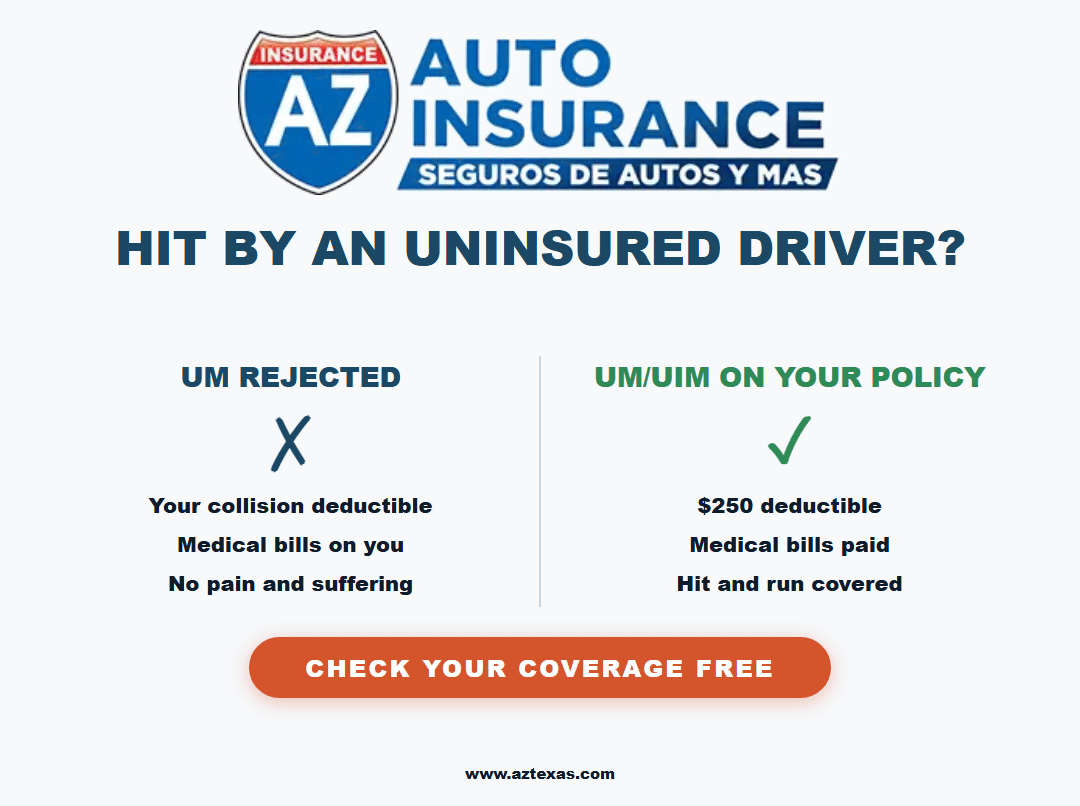
TDI adds two details that matter in real life. The coverage also pays after a hit and run when the other driver can't be found to pay for damages, and "the deductible for uninsured/underinsured coverage is $250. The deductible if you use your collision is likely much higher."
Scenario | Without UM/UIM | With UM/UIM |
|---|---|---|
An uninsured driver rear ends you at a light | Collision pays the car, minus your collision deductible, if you carry collision at all | UM/UIM pays the car with a $250 deductible |
You and your passengers need treatment | Your health insurance, your PIP, or your own pocket | UM/UIM pays medical bills |
You miss weeks of feeling normal | Nothing on your policy pays pain and suffering | Pain and suffering is covered |
The other driver drives off and is never found | You are in the same place as an uninsured crash | Hit and run is covered |
Your car is worth less after the repair | You absorb the lost value | Diminished value is covered |
Notice the first row. If you carry only liability, as many older or paid off cars do, there may be no collision coverage to fall back on at all. If you still owe money on the car, the lender usually decides that question for you, and what gap insurance covers and whether you need it covers the other half of that conversation.
Get a free auto coverage check or call (281) 833-8585. Hablamos Español.
Uninsured, underinsured and hit and run
The coverage has two halves, and the second one is the one people forget.
Texas requires every driver to carry at least 30/60/25 liability: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage, per the TDI auto insurance guide. Those limits were set a long time ago and a serious injury can pass them quickly. TDI describes UM/UIM as paying "if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills." That second part is the underinsured half.
What happened | Which part responds | What to know |
|---|---|---|
The other driver had no insurance at all | Uninsured motorist | Pays up to your UM limit, $250 deductible |
The other driver had only the state minimum and your bills are higher | Underinsured motorist | Responds when their insurance is not enough, up to your own UM/UIM limit |
The other driver fled and is never identified | Uninsured motorist | TDI says it covers hit and run when the driver cannot be found |
You caused the crash | Neither | Your liability pays the other driver, your collision pays your car |
The limit you choose matters as much as having the coverage. By statute the UM/UIM minimums track the same state minimum limits as liability, so a policy can carry UM/UIM at the bare minimum. If a crash puts someone in your family in the hospital, that ceiling arrives fast. Ask your agent to show you your UM/UIM limits next to your liability limits, and if you carry an umbrella, whether it extends over uninsured drivers at all, which we touch on in what an umbrella insurance policy covers.
The box you may have rejected years ago
This is the part most drivers never see coming.
Texas law requires the coverage to be there. Section 1952.101 of the Insurance Code says an insurer cannot issue an auto liability policy in Texas without UM/UIM coverage, and that the coverage "does not apply if any insured named in the insurance policy rejects the coverage in writing." TDI puts it in consumer terms: "Insurance companies must offer you this coverage. If you don't want it, you must tell the company in writing."
That signature usually happens once, often quietly, on the day the policy is bought, when someone is trying to hit a monthly number. Then it stays. Under the same section, if the named insured rejected the coverage, the insurer is not required to put it back on a renewal or reinstated policy unless the named insured requests it in writing. TDI's updated auto Consumer Bill of Rights, which takes effect January 1, 2027, says the same thing and adds that you may request the coverages at any time.
So a rejection signed at a dealership five years ago may still be on your policy today, renewed automatically term after term.
Where to look | What you are looking for | What it means |
|---|---|---|
Declarations page, coverage list | A line for Uninsured/Underinsured Motorist with a limit | You have it. Check the limit |
Declarations page, coverage list | No UM/UIM line, or "rejected" | Someone declined it |
The signed application or a rejection form | A written UM/UIM or PIP rejection | That is why it is missing, and it carries forward |
Every driver on the policy | Who is named, and who signed | Any named insured's written rejection counts |
The fix is simple and it is in writing. Ask to add UM/UIM back, and ask what limit makes sense next to your liability limits. It is one of the few coverage changes that protects you from someone else's decision.
This matters most for households with the most exposure to other drivers: a new teen behind the wheel, covered in adding a teen driver in Texas, a family that logs long summer driving in Texas, or a rider, because a motorcycle crash with an uninsured driver is rarely a small one. Our guide on whether you have to have insurance on a motorcycle in Texas covers the bike side.
PIP, the other coverage Texas includes unless you say no
Personal injury protection works the same way. TDI's auto guide says: "All auto policies in Texas include PIP coverage. If you don't want it, you must tell the company in writing." PIP pays your and your passengers' medical bills, and TDI notes it "also pays for things like lost wages and other nonmedical costs."
Coverage | Who it pays | Included by default in Texas? |
|---|---|---|
Liability | The other people you hurt and their property | Required by law, 30/60/25 minimum |
UM/UIM | You and your passengers, when the at fault driver has no or too little insurance | Yes, unless rejected in writing |
PIP | You and your passengers' medical bills and certain lost wages | Yes, unless rejected in writing |
Collision | Your car, after your deductible | No, it is optional unless a lender requires it |
If you find one of them missing, check the other, because both come off a policy the same way: in writing.
Can I switch before my renewal date?
Yes. You do not have to wait for your renewal to change auto insurance, and a missing UM/UIM line is a good reason to look.
TDI's auto guide says that "if either you or the company cancels your policy, the company must refund any unearned premium to you within 15 days after the date of the cancellation." The practical order matters:
Get the new policy bound first, with an effective date and time.
Confirm it exists. TDI's July 27, 2026 fraud warning is blunt: "After you buy a policy, call the insurance company directly to confirm that there is a policy in your name."
Then cancel the old one in writing, effective the same day the new one starts, so there is no gap.
Watch for the refund of unearned premium from the old company.
We walk through the full switch, including timing and what to ask for, in how to switch car insurance easily in 2026. If the car is not titled in your name, read how to insure a car that is not in your name in Texas before you move anything, because it changes who can be the named insured.
Two things tend to push people to shop mid term: a rate change after a violation, which we covered for school zone tickets and for how a DUI affects your auto insurance rates, or a filing requirement such as an SR-22, where what SR-22 insurance costs per month in Texas is the place to start. If you are buying a car at the same time, insurance before you drive off the lot in Houston covers the day of purchase. And if the vehicle is also used for work, check the difference between personal and commercial insurance first.
Frequently asked questions
Q: How many drivers in Texas are uninsured?
The Texas Department of Motor Vehicles estimates 11.87 percent of Texas drivers are uninsured, as of September 2025. That is about 1 in 8.
Q: What does uninsured motorist coverage pay for in Texas?
Per the Texas Department of Insurance, UM/UIM pays for car repairs and the property in your car, a rental car if you need it, your and your passengers' medical bills, pain and suffering, and diminished value. It also pays in a hit and run when the other driver cannot be found.
Q: What is the deductible for uninsured motorist coverage in Texas?
TDI says the deductible for uninsured/underinsured coverage is $250, and that a collision deductible is likely much higher.
Q: Is uninsured motorist coverage required in Texas?
Insurers are required to include it on every auto liability policy. You can remove it only by rejecting it in writing. So it is on your policy by default, unless someone named on the policy signed it away.
Q: If I rejected UM/UIM before, is it still rejected on my renewal?
Usually yes. Under Insurance Code Section 1952.101, once the named insured rejects the coverage, the insurer does not have to add it back on a renewal unless the named insured asks for it in writing. You can ask to add it back.
Q: What is the difference between uninsured and underinsured motorist coverage?
Uninsured pays when the at fault driver has no insurance or cannot be found. Underinsured pays when the at fault driver has insurance but not enough to cover your medical and car repair bills, such as a driver carrying only the 30/60/25 state minimum.
Q: Can I change car insurance before my renewal date in Texas?
Yes. Start the new policy first, confirm it with the insurance company, then cancel the old one in writing effective the same day. TDI says the old company must refund any unearned premium within 15 days after the cancellation.
Q: Does PIP come with every Texas auto policy?
Yes, unless you reject it in writing. TDI says all auto policies in Texas include PIP, which pays your and your passengers' medical bills and things like lost wages.
Related Articles
Why AZ Insurance Stands Apart
Most drivers learn what UM/UIM is on the worst day of the year, on the shoulder of a road, when the other driver says he does not have insurance. We would rather you learn it now, from your own declarations page. AZ Insurance has served Texas drivers since 2003 from 15 offices across Houston and Dallas, we compare 20+ insurance companies rather than defending one, and we will show you exactly which coverages are on your policy, which were rejected, and what it takes to put them back.
Bring us your current declarations page, from any company. Request a free auto coverage check or call our auto line at (281) 833-8585, and we will tell you in plain English or Spanish whether you are covered when the other driver is not.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. If you have been in a crash with an uninsured driver and have questions about a claim, the TDI Help Line is 800-252-3439.
Quick Answer: About 1 in 8 Texas drivers is uninsured, per the TxDMV estimate of 11.87 percent. If one hits you, uninsured and underinsured motorist coverage pays your car repairs, medical bills and pain and suffering, with a $250 deductible. Texas puts UM/UIM and PIP on every policy unless someone rejected them in writing.
What this article covers
The number behind the fear
What UM/UIM actually pays
Uninsured, underinsured and hit and run
The box you may have rejected years ago
PIP, the other coverage Texas includes unless you say no
Can I switch before my renewal date?
Frequently asked questions
A driver in Baytown is stopped at a light on Garth Road when a pickup rear ends her. Nobody is hurt badly, but her back is sore for weeks and the trunk will not close. The other driver is apologetic, and he has no insurance.
The police report says he was at fault. That part is easy. The hard part is that "at fault" only helps if there is a policy on the other side to pay. When there is not, a judgment against the other driver is only worth what that driver can actually pay.
What decides her next month is not his policy. It is one line on hers.
Key Takeaways
An estimated 11.87 percent of Texas drivers are uninsured, according to the Texas Department of Motor Vehicles, as of September 2025. That is about 1 in 8.
Uninsured and underinsured motorist coverage, UM/UIM, pays you when the at fault driver cannot, including your medical bills, car repairs, a rental and pain and suffering.
The UM/UIM deductible is $250, per the Texas Department of Insurance. A collision deductible is usually much higher.
Texas insurers must include UM/UIM and PIP. They come off your policy only if someone named on it rejected them in writing.
A rejection signed years ago usually follows the policy through every renewal until someone asks, in writing, to put the coverage back.
You can change auto insurance before your renewal date. Start the new policy first, then cancel the old one.
The number behind the fear
The Texas Department of Motor Vehicles runs TexasSure, the state's insurance verification database. On its TexasSure page it says: "Currently, an estimated 11.87 percent of Texas drivers are uninsured (as of September 2025)."
You will see other numbers quoted online. We use the state's figure because it comes from the state's own verification database. At that number, roughly one car in eight around you on I-10 or US 59 has nobody behind it to pay if it hits you.
That is also why Texas checks insurance at registration, which we covered in do you need insurance before registering a car in Texas. Checking does not mean every driver keeps the policy afterward.
It also helps to separate the two questions people mix up. Your own liability insurance exists to pay for damage you cause to others, the basics of which we laid out in what is the main purpose of having auto insurance. This article is about the opposite situation: damage somebody else causes to you, when their liability insurance is missing or too small.
What UM/UIM actually pays
The Texas Department of Insurance lists it plainly on its uninsured motorist page. UM/UIM pays for:
Car repairs and replacing the property in your car
A rental car if you need it
Your and your passengers' medical bills
Pain and suffering
Diminished value if your car is worth less after the accident
TDI adds two details that matter in real life. The coverage also pays after a hit and run when the other driver can't be found to pay for damages, and "the deductible for uninsured/underinsured coverage is $250. The deductible if you use your collision is likely much higher."
Scenario | Without UM/UIM | With UM/UIM |
|---|---|---|
An uninsured driver rear ends you at a light | Collision pays the car, minus your collision deductible, if you carry collision at all | UM/UIM pays the car with a $250 deductible |
You and your passengers need treatment | Your health insurance, your PIP, or your own pocket | UM/UIM pays medical bills |
You miss weeks of feeling normal | Nothing on your policy pays pain and suffering | Pain and suffering is covered |
The other driver drives off and is never found | You are in the same place as an uninsured crash | Hit and run is covered |
Your car is worth less after the repair | You absorb the lost value | Diminished value is covered |
Notice the first row. If you carry only liability, as many older or paid off cars do, there may be no collision coverage to fall back on at all. If you still owe money on the car, the lender usually decides that question for you, and what gap insurance covers and whether you need it covers the other half of that conversation.
Get a free auto coverage check or call (281) 833-8585. Hablamos Español.
Uninsured, underinsured and hit and run
The coverage has two halves, and the second one is the one people forget.
Texas requires every driver to carry at least 30/60/25 liability: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage, per the TDI auto insurance guide. Those limits were set a long time ago and a serious injury can pass them quickly. TDI describes UM/UIM as paying "if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills." That second part is the underinsured half.
What happened | Which part responds | What to know |
|---|---|---|
The other driver had no insurance at all | Uninsured motorist | Pays up to your UM limit, $250 deductible |
The other driver had only the state minimum and your bills are higher | Underinsured motorist | Responds when their insurance is not enough, up to your own UM/UIM limit |
The other driver fled and is never identified | Uninsured motorist | TDI says it covers hit and run when the driver cannot be found |
You caused the crash | Neither | Your liability pays the other driver, your collision pays your car |
The limit you choose matters as much as having the coverage. By statute the UM/UIM minimums track the same state minimum limits as liability, so a policy can carry UM/UIM at the bare minimum. If a crash puts someone in your family in the hospital, that ceiling arrives fast. Ask your agent to show you your UM/UIM limits next to your liability limits, and if you carry an umbrella, whether it extends over uninsured drivers at all, which we touch on in what an umbrella insurance policy covers.
The box you may have rejected years ago
This is the part most drivers never see coming.
Texas law requires the coverage to be there. Section 1952.101 of the Insurance Code says an insurer cannot issue an auto liability policy in Texas without UM/UIM coverage, and that the coverage "does not apply if any insured named in the insurance policy rejects the coverage in writing." TDI puts it in consumer terms: "Insurance companies must offer you this coverage. If you don't want it, you must tell the company in writing."
That signature usually happens once, often quietly, on the day the policy is bought, when someone is trying to hit a monthly number. Then it stays. Under the same section, if the named insured rejected the coverage, the insurer is not required to put it back on a renewal or reinstated policy unless the named insured requests it in writing. TDI's updated auto Consumer Bill of Rights, which takes effect January 1, 2027, says the same thing and adds that you may request the coverages at any time.
So a rejection signed at a dealership five years ago may still be on your policy today, renewed automatically term after term.
Where to look | What you are looking for | What it means |
|---|---|---|
Declarations page, coverage list | A line for Uninsured/Underinsured Motorist with a limit | You have it. Check the limit |
Declarations page, coverage list | No UM/UIM line, or "rejected" | Someone declined it |
The signed application or a rejection form | A written UM/UIM or PIP rejection | That is why it is missing, and it carries forward |
Every driver on the policy | Who is named, and who signed | Any named insured's written rejection counts |
The fix is simple and it is in writing. Ask to add UM/UIM back, and ask what limit makes sense next to your liability limits. It is one of the few coverage changes that protects you from someone else's decision.
This matters most for households with the most exposure to other drivers: a new teen behind the wheel, covered in adding a teen driver in Texas, a family that logs long summer driving in Texas, or a rider, because a motorcycle crash with an uninsured driver is rarely a small one. Our guide on whether you have to have insurance on a motorcycle in Texas covers the bike side.
PIP, the other coverage Texas includes unless you say no
Personal injury protection works the same way. TDI's auto guide says: "All auto policies in Texas include PIP coverage. If you don't want it, you must tell the company in writing." PIP pays your and your passengers' medical bills, and TDI notes it "also pays for things like lost wages and other nonmedical costs."
Coverage | Who it pays | Included by default in Texas? |
|---|---|---|
Liability | The other people you hurt and their property | Required by law, 30/60/25 minimum |
UM/UIM | You and your passengers, when the at fault driver has no or too little insurance | Yes, unless rejected in writing |
PIP | You and your passengers' medical bills and certain lost wages | Yes, unless rejected in writing |
Collision | Your car, after your deductible | No, it is optional unless a lender requires it |
If you find one of them missing, check the other, because both come off a policy the same way: in writing.
Can I switch before my renewal date?
Yes. You do not have to wait for your renewal to change auto insurance, and a missing UM/UIM line is a good reason to look.
TDI's auto guide says that "if either you or the company cancels your policy, the company must refund any unearned premium to you within 15 days after the date of the cancellation." The practical order matters:
Get the new policy bound first, with an effective date and time.
Confirm it exists. TDI's July 27, 2026 fraud warning is blunt: "After you buy a policy, call the insurance company directly to confirm that there is a policy in your name."
Then cancel the old one in writing, effective the same day the new one starts, so there is no gap.
Watch for the refund of unearned premium from the old company.
We walk through the full switch, including timing and what to ask for, in how to switch car insurance easily in 2026. If the car is not titled in your name, read how to insure a car that is not in your name in Texas before you move anything, because it changes who can be the named insured.
Two things tend to push people to shop mid term: a rate change after a violation, which we covered for school zone tickets and for how a DUI affects your auto insurance rates, or a filing requirement such as an SR-22, where what SR-22 insurance costs per month in Texas is the place to start. If you are buying a car at the same time, insurance before you drive off the lot in Houston covers the day of purchase. And if the vehicle is also used for work, check the difference between personal and commercial insurance first.
Frequently asked questions
Q: How many drivers in Texas are uninsured?
The Texas Department of Motor Vehicles estimates 11.87 percent of Texas drivers are uninsured, as of September 2025. That is about 1 in 8.
Q: What does uninsured motorist coverage pay for in Texas?
Per the Texas Department of Insurance, UM/UIM pays for car repairs and the property in your car, a rental car if you need it, your and your passengers' medical bills, pain and suffering, and diminished value. It also pays in a hit and run when the other driver cannot be found.
Q: What is the deductible for uninsured motorist coverage in Texas?
TDI says the deductible for uninsured/underinsured coverage is $250, and that a collision deductible is likely much higher.
Q: Is uninsured motorist coverage required in Texas?
Insurers are required to include it on every auto liability policy. You can remove it only by rejecting it in writing. So it is on your policy by default, unless someone named on the policy signed it away.
Q: If I rejected UM/UIM before, is it still rejected on my renewal?
Usually yes. Under Insurance Code Section 1952.101, once the named insured rejects the coverage, the insurer does not have to add it back on a renewal unless the named insured asks for it in writing. You can ask to add it back.
Q: What is the difference between uninsured and underinsured motorist coverage?
Uninsured pays when the at fault driver has no insurance or cannot be found. Underinsured pays when the at fault driver has insurance but not enough to cover your medical and car repair bills, such as a driver carrying only the 30/60/25 state minimum.
Q: Can I change car insurance before my renewal date in Texas?
Yes. Start the new policy first, confirm it with the insurance company, then cancel the old one in writing effective the same day. TDI says the old company must refund any unearned premium within 15 days after the cancellation.
Q: Does PIP come with every Texas auto policy?
Yes, unless you reject it in writing. TDI says all auto policies in Texas include PIP, which pays your and your passengers' medical bills and things like lost wages.
Related Articles
Why AZ Insurance Stands Apart
Most drivers learn what UM/UIM is on the worst day of the year, on the shoulder of a road, when the other driver says he does not have insurance. We would rather you learn it now, from your own declarations page. AZ Insurance has served Texas drivers since 2003 from 15 offices across Houston and Dallas, we compare 20+ insurance companies rather than defending one, and we will show you exactly which coverages are on your policy, which were rejected, and what it takes to put them back.
Bring us your current declarations page, from any company. Request a free auto coverage check or call our auto line at (281) 833-8585, and we will tell you in plain English or Spanish whether you are covered when the other driver is not.
This article is general information, not legal advice or a promise of coverage. What your policy covers is governed by that policy. If you have been in a crash with an uninsured driver and have questions about a claim, the TDI Help Line is 800-252-3439.
Latest Blogs

Texas SR-22 After a DWI: How to Reinstate Your License

How Much Does Umbrella Insurance Cost in Texas?

Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For

How to Read Your Texas Home Insurance Declarations Page, Line by Line

How to Lower Car Insurance: 10 Practical Ways to Pay Less

What Is Gap Insurance and What Does It Cover? Do You Need It?
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How to Lower Car Insurance: 10 Practical Ways to Pay Less
Learn how to lower car insurance in Texas with 10 proven ways to cut your premium, from discounts and deductibles to shopping smarter at every renewal.
How to Lower Car Insurance: 10 Practical Ways to Pay Less
Learn how to lower car insurance in Texas with 10 proven ways to cut your premium, from discounts and deductibles to shopping smarter at every renewal.
How to Lower Car Insurance: 10 Practical Ways to Pay Less
Learn how to lower car insurance in Texas with 10 proven ways to cut your premium, from discounts and deductibles to shopping smarter at every renewal.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.