Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash
Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash
Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash
Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash
Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash

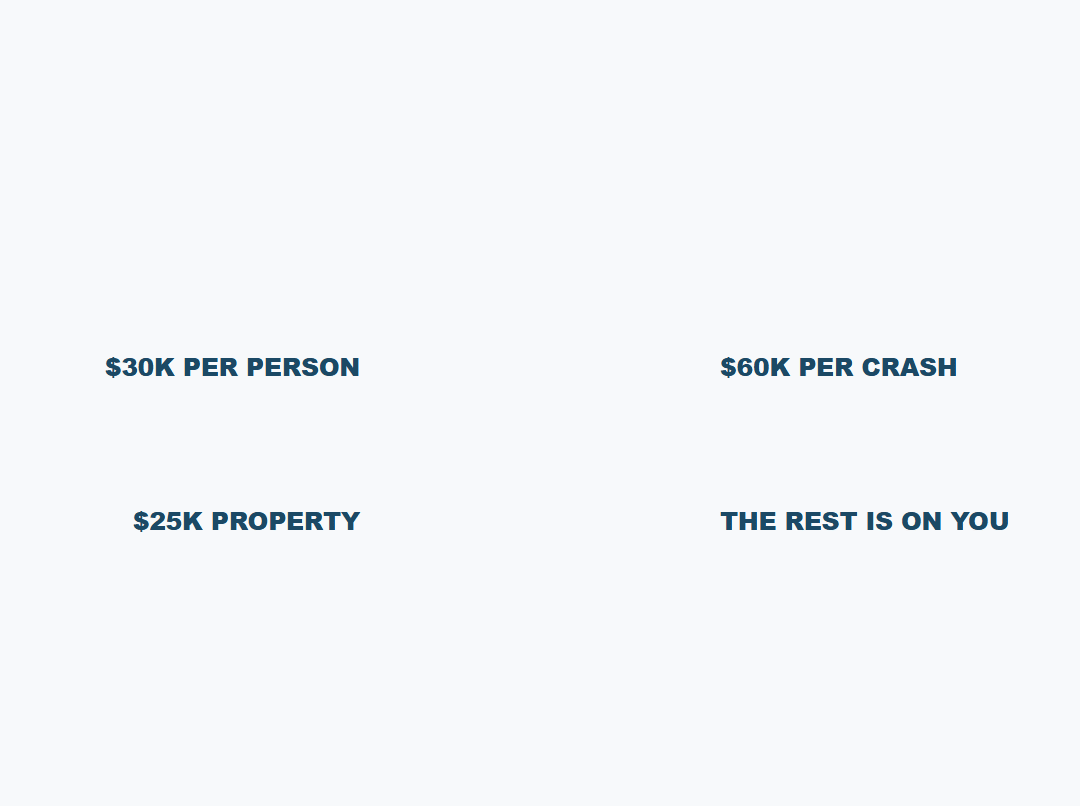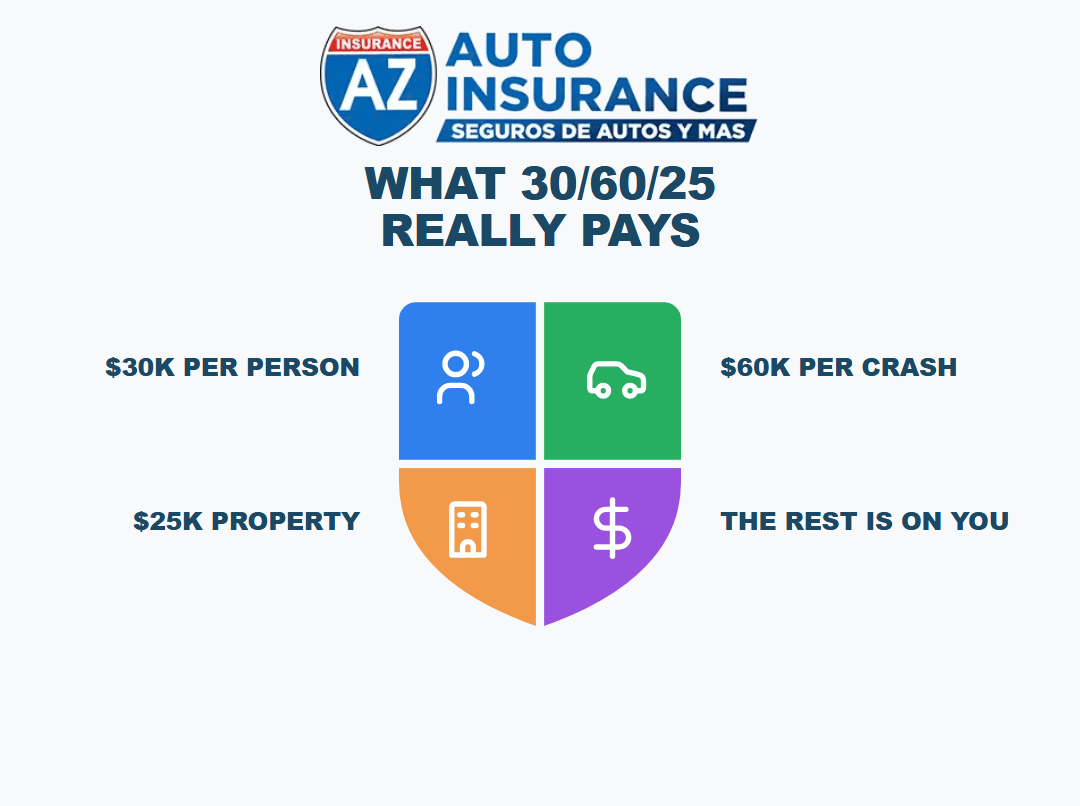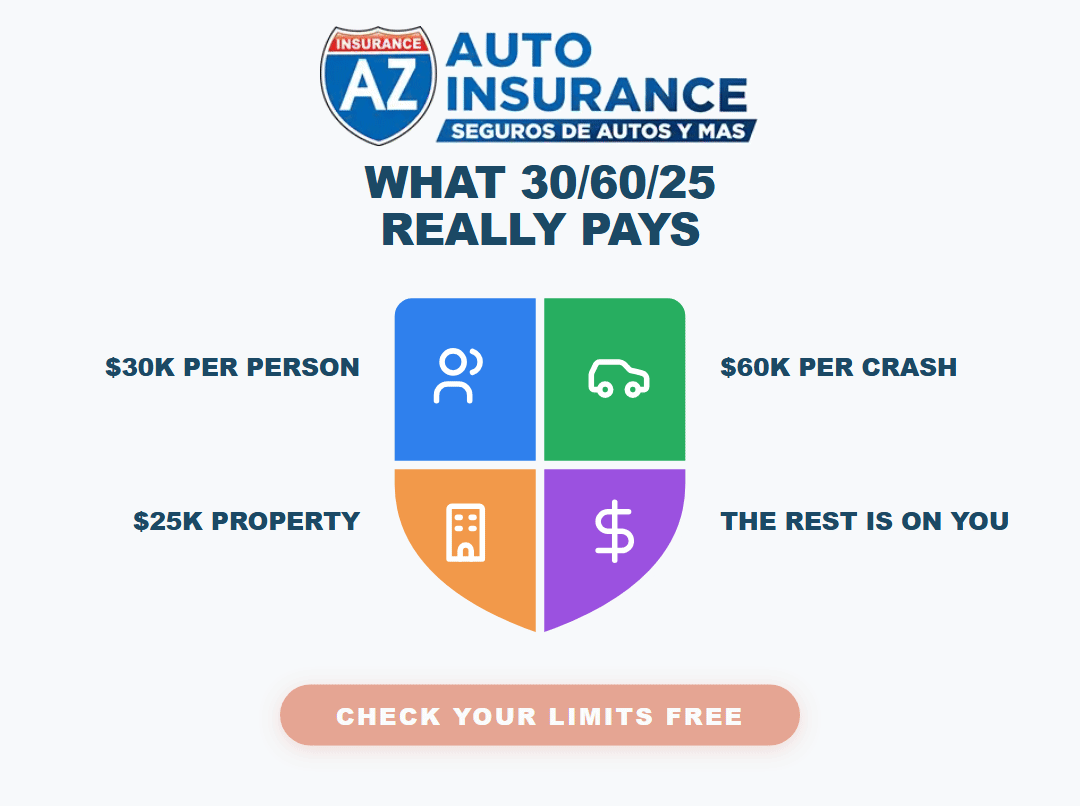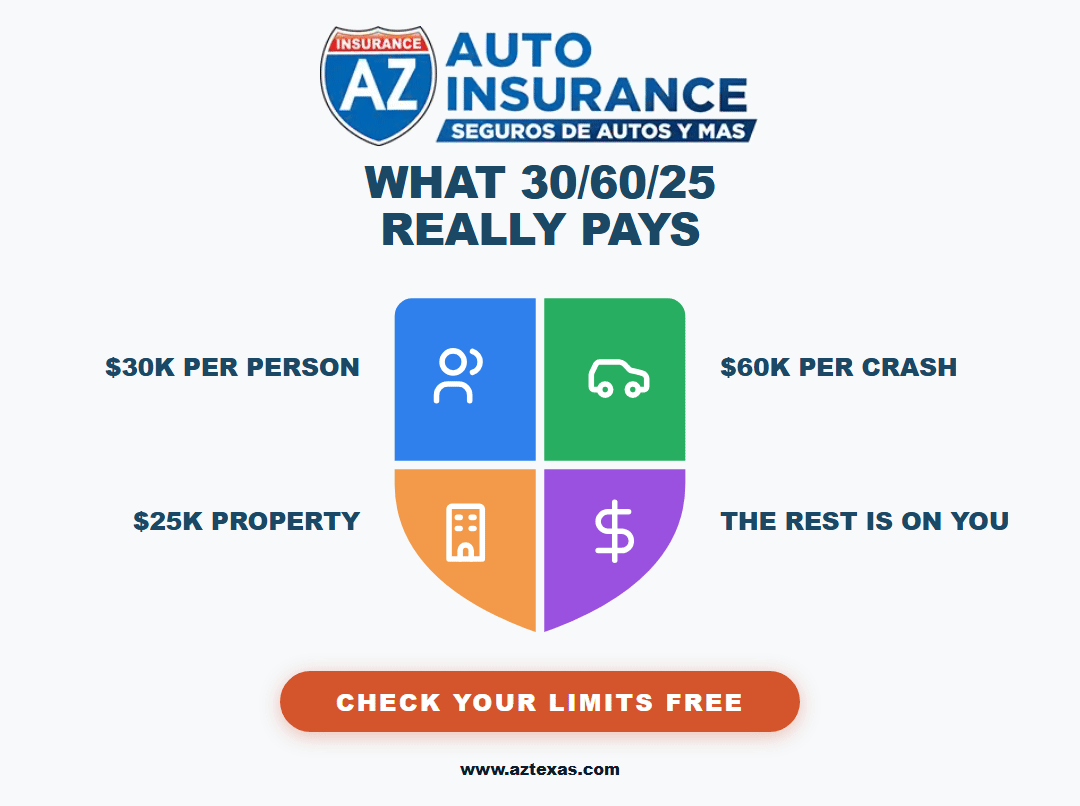
Quick Answer: Texas minimum car insurance is 30/60/25 liability: $30,000 for one person's injuries, $60,000 for everyone hurt in one crash, and $25,000 for property damage. It pays other people when you cause a wreck, never your own car or your own injuries. If the damage you cause is bigger, TDI says you might have to pay the rest yourself.
What this article covers
What 30/60/25 means, in plain English
What the minimum never pays for
Three crashes where the minimum runs out
The other side: when the driver who hits you has the minimum
How much liability is enough for you?
How to check your limits in five minutes
Frequently asked questions
A driver in Pasadena is heading home on Spencer Highway when traffic stops faster than he does. He rear ends a newer pickup hard enough to push it into the car in front of it. Nobody dies, but two people go to the emergency room, the pickup is totaled, and the car at the front of the chain needs a new back end.
He did everything the state asked of him. He carried insurance, the card was in the glove box, and TexasSure showed him as covered. What he carried was the state minimum, and in about four seconds he caused more damage than the minimum was built to pay.
That gap is what this article is about. The minimum keeps you legal. Whether it keeps you whole is a different question.
Key Takeaways
Texas minimum liability is 30/60/25, set by Transportation Code Section 601.072 and unchanged since January 1, 2011.
Liability pays the other people, their injuries and their property, when you cause the crash. It never pays for your own car or your own injuries.
TDI warns the minimum might be too low if you cause a crash with several vehicles or total someone's car, and says you "might have to pay the rest out of your own pocket."
The $25,000 property limit covers every car and object you damage in one crash combined, not each one.
When the other driver carries only the minimum, your own underinsured motorist coverage is what fills the gap for your injuries and your car.
Higher limits are easy to price side by side. Ask for your current limits and a higher set on the same quote so you are comparing one thing.
What 30/60/25 means, in plain English
Texas law requires every driver to show they can pay for the accidents they cause, and most people do that by buying liability insurance. The TDI auto insurance guide spells out the floor: "Texas law requires you to have at least $30,000 of coverage for injuries per person, up to a total of $60,000 per accident, and $25,000 of coverage for property damage. This is called 30/60/25 coverage."
The same three numbers are in Transportation Code Section 601.072, which has set them at these amounts since January 1, 2011. Cars, trucks and hospital bills have changed a great deal since then. The minimum has not.
The number | What it is | What it pays | The catch |
|---|---|---|---|
30 | $30,000 bodily injury, per person | One injured person's medical bills and related costs when you are at fault | It is the most any one person can get, however badly they are hurt |
60 | $60,000 bodily injury, per accident | Everyone injured in one crash, combined | Two people at the full $30,000 each uses all of it |
25 | $25,000 property damage, per accident | Other people's cars, fences, poles and buildings you damage | One limit for every car and object in the crash, combined |
If you want the bigger picture of why liability exists at all, we laid out the basics in what is the main purpose of having auto insurance. The short version: liability protects the people you hit, and it protects you from having to pay them yourself.
What the minimum never pays for
This is the part people are most surprised by. A 30/60/25 policy does not pay one dollar toward your own car or your own medical bills. TDI describes liability this way: it "pays to repair the other driver's car if you caused the accident. It also pays the other driver's and his or her passenger's medical bills and some other expenses."
Everything on your side of the crash comes from other coverages, if you have them.
What got damaged or hurt | Liability (30/60/25) | What actually pays for it |
|---|---|---|
The other driver's car | Yes, up to $25,000 total property | Your liability |
The other driver's and passengers' injuries | Yes, up to $30,000 each and $60,000 total | Your liability |
Your car | No | Collision, after your deductible, if you carry it |
Your car, from hail, theft or hitting a deer | No | Comprehensive, if you carry it |
You and your passengers' medical bills | No | PIP or medical payments, if not rejected |
Your injuries when the other driver is at fault and uninsured | No | Uninsured motorist coverage, if not rejected |
Collision and comprehensive are optional in Texas unless you owe money on the car. TDI is direct about that: "If you still owe money on your car, your lender will require you to have collision and comprehensive coverage." We explain how the deductible on those coverages works in what is a deductible in car insurance.
Three crashes where the minimum runs out
TDI says it plainly: "Think about buying more liability coverage." It warns that the minimum limits might be too low if you cause a crash involving several vehicles or the other driver's car is totaled, and that "if you don't have enough liability coverage to pay for the damages and injuries you cause, you might have to pay the rest out of your own pocket. The other driver could sue you."
Here is what that looks like with round numbers. These are examples, not quotes or averages, but each one is an ordinary kind of crash.
The crash | The damage you caused | What 30/60/25 pays | What is left |
|---|---|---|---|
You total a newer pickup at a light | A truck worth $45,000 | $25,000 property limit | $20,000 |
Two people in the other car need surgery | $40,000 of bills for each person | $30,000 each, $60,000 total | $20,000 |
A three car chain on the freeway | $14,000 + $12,000 + $9,000 in repairs | $25,000 property limit, shared by all three | $10,000 |
Notice the third row. The $25,000 property limit is for the whole crash, so three damaged cars split one limit between them. That is exactly the situation TDI flags.
What is left does not disappear. The people you hurt can come to you for it, and that is when a liability limit stops being a line on a card and starts being a question about your savings, your home equity and your paycheck.
Get a free auto coverage check or call (281) 833-8585. Hablamos Español.
The other side: when the driver who hits you has the minimum
Run the same math in reverse. If someone carrying 30/60/25 causes a crash that puts you in the hospital, their policy pays you at most $30,000, however large your bills are.
That is the job of underinsured motorist coverage, the UIM half of UM/UIM. TDI says uninsured/underinsured motorist coverage "pays if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills." It is on every Texas policy unless someone rejected it in writing, and we walk through how to find out whether yours was rejected in uninsured motorist coverage in Texas.
Two details from TDI's uninsured motorist page help you set it:
"You can usually add more uninsured/underinsured coverage in $5,000 increments."
"A rule of thumb is to add at least enough property damage coverage to replace your vehicle."
The at fault driver carried | Your injuries | Their liability pays | Your UIM can cover |
|---|---|---|---|
30/60/25 | $55,000 in medical bills and lost wages | $30,000 | The rest, up to your UIM limit |
No insurance at all | $55,000 | Nothing | Up to your UM limit |
30/60/25, and you rejected UM/UIM | $55,000 | $30,000 | Nothing. You pursue the driver directly |
This is why your liability limits and your UM/UIM limits belong in the same conversation. One protects the people you might hurt. The other protects you from the people who might hurt you with too little insurance.
How much liability is enough for you?
There is no single right number, and anyone who gives you one without asking questions is guessing. These are the questions we actually ask.
Question | Why it matters |
|---|---|
What would you lose in a lawsuit? Home equity, savings, future wages | The more you have to protect, the more a gap above your limit puts at risk |
Who drives your cars? | A new driver in the house changes the odds, see adding a teen driver in Texas |
How much do you drive, and where? | Long freeway commutes mean more cars around you at higher speed |
Do you have, or want, an umbrella policy? | Most umbrella policies require higher auto limits underneath them |
Is your car paid off? | That changes collision and comprehensive, not how much liability you need |
Higher split limits, such as 50/100/50 or 100/300/100, are widely available. The only honest way to know what they cost you is to price them side by side, your current limits and a higher set on the same quote, from the same company, on the same day.
If you have real assets to protect, an umbrella policy sits on top of your auto and home liability. We cover what it does in what an umbrella insurance policy covers and what it tends to cost in how much umbrella insurance costs in Texas.
One honest exception. If your car is old and paid off, dropping collision can be a reasonable way to save, because collision protects your car. Lowering liability is a different decision, because liability protects everyone else, and their cars and hospital bills did not get any cheaper when yours got older.
How to check your limits in five minutes
Your limits are printed on your declarations page, the summary page of your policy. TDI's guide to reading your declarations page walks through where each item sits.
Find the liability line. It may read 30/60/25, or list bodily injury as 30,000/60,000 and property damage as 25,000.
Find the UM/UIM line. Check that it is there, and what limit it carries.
Look for PIP. It is included in Texas unless someone rejected it in writing.
Check collision and comprehensive. If you owe money on the car, your lender requires both.
Write down anything missing or at the minimum, and ask for a side by side quote with higher limits.
If you are about to change companies, our guide on how to switch car insurance easily in 2026 covers the order to do it in so you never have a gap. If you are buying a car, start with do you need insurance before registering a car in Texas, and if the car is financed, what gap insurance covers and whether you need it is worth a read too.
Frequently asked questions
Q: What is the minimum car insurance required in Texas?
Texas requires 30/60/25 liability: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage, per the Texas Department of Insurance and Transportation Code Section 601.072.
Q: Does minimum liability insurance cover my own car in Texas?
No. Liability pays for damage and injuries you cause to other people. Your own car is covered only by collision and comprehensive, which are optional unless a lender requires them.
Q: What happens if the damage I cause is more than my limits?
TDI says that if you don't have enough liability coverage to pay for the damages and injuries you cause, you might have to pay the rest out of your own pocket, and the other driver could sue you.
Q: Is the $25,000 property damage limit per car?
No. It is per accident. If you damage three cars in one crash, all three share the same $25,000.
Q: When did Texas last raise the minimum car insurance limits?
Transportation Code Section 601.072 sets the current 30/60/25 minimums effective January 1, 2011.
Q: What protects me if the driver who hits me has only the minimum?
Your own underinsured motorist coverage. TDI says UM/UIM pays if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills. It is on every Texas policy unless it was rejected in writing.
Q: How do I know what limits I have?
Look at your declarations page. The liability line shows your bodily injury and property damage limits, and the coverage list shows whether you carry UM/UIM, PIP, collision and comprehensive.
Related Articles
Why AZ Insurance Stands Apart
The minimum is easy to sell, because it is the cheapest line on any quote. We would rather show you what it leaves uncovered before you need it. AZ Insurance has served Texas drivers since 2003 from 15 offices across Houston and Dallas, and we compare 20+ insurance companies, so we can put your current limits and a higher set side by side and let you decide with real numbers in front of you.
Bring your declarations page from any company. Request a free auto coverage check or call our auto line at (281) 833-8585, and we will walk you through it in plain English or Spanish.
This article is general information, not legal advice or a promise of coverage. The examples use round numbers for illustration and are not quotes or averages. What your policy covers is governed by that policy. For questions about auto insurance in Texas, the TDI Help Line is 800-252-3439.
Quick Answer: Texas minimum car insurance is 30/60/25 liability: $30,000 for one person's injuries, $60,000 for everyone hurt in one crash, and $25,000 for property damage. It pays other people when you cause a wreck, never your own car or your own injuries. If the damage you cause is bigger, TDI says you might have to pay the rest yourself.
What this article covers
What 30/60/25 means, in plain English
What the minimum never pays for
Three crashes where the minimum runs out
The other side: when the driver who hits you has the minimum
How much liability is enough for you?
How to check your limits in five minutes
Frequently asked questions
A driver in Pasadena is heading home on Spencer Highway when traffic stops faster than he does. He rear ends a newer pickup hard enough to push it into the car in front of it. Nobody dies, but two people go to the emergency room, the pickup is totaled, and the car at the front of the chain needs a new back end.
He did everything the state asked of him. He carried insurance, the card was in the glove box, and TexasSure showed him as covered. What he carried was the state minimum, and in about four seconds he caused more damage than the minimum was built to pay.
That gap is what this article is about. The minimum keeps you legal. Whether it keeps you whole is a different question.
Key Takeaways
Texas minimum liability is 30/60/25, set by Transportation Code Section 601.072 and unchanged since January 1, 2011.
Liability pays the other people, their injuries and their property, when you cause the crash. It never pays for your own car or your own injuries.
TDI warns the minimum might be too low if you cause a crash with several vehicles or total someone's car, and says you "might have to pay the rest out of your own pocket."
The $25,000 property limit covers every car and object you damage in one crash combined, not each one.
When the other driver carries only the minimum, your own underinsured motorist coverage is what fills the gap for your injuries and your car.
Higher limits are easy to price side by side. Ask for your current limits and a higher set on the same quote so you are comparing one thing.
What 30/60/25 means, in plain English
Texas law requires every driver to show they can pay for the accidents they cause, and most people do that by buying liability insurance. The TDI auto insurance guide spells out the floor: "Texas law requires you to have at least $30,000 of coverage for injuries per person, up to a total of $60,000 per accident, and $25,000 of coverage for property damage. This is called 30/60/25 coverage."
The same three numbers are in Transportation Code Section 601.072, which has set them at these amounts since January 1, 2011. Cars, trucks and hospital bills have changed a great deal since then. The minimum has not.
The number | What it is | What it pays | The catch |
|---|---|---|---|
30 | $30,000 bodily injury, per person | One injured person's medical bills and related costs when you are at fault | It is the most any one person can get, however badly they are hurt |
60 | $60,000 bodily injury, per accident | Everyone injured in one crash, combined | Two people at the full $30,000 each uses all of it |
25 | $25,000 property damage, per accident | Other people's cars, fences, poles and buildings you damage | One limit for every car and object in the crash, combined |
If you want the bigger picture of why liability exists at all, we laid out the basics in what is the main purpose of having auto insurance. The short version: liability protects the people you hit, and it protects you from having to pay them yourself.
What the minimum never pays for
This is the part people are most surprised by. A 30/60/25 policy does not pay one dollar toward your own car or your own medical bills. TDI describes liability this way: it "pays to repair the other driver's car if you caused the accident. It also pays the other driver's and his or her passenger's medical bills and some other expenses."
Everything on your side of the crash comes from other coverages, if you have them.
What got damaged or hurt | Liability (30/60/25) | What actually pays for it |
|---|---|---|
The other driver's car | Yes, up to $25,000 total property | Your liability |
The other driver's and passengers' injuries | Yes, up to $30,000 each and $60,000 total | Your liability |
Your car | No | Collision, after your deductible, if you carry it |
Your car, from hail, theft or hitting a deer | No | Comprehensive, if you carry it |
You and your passengers' medical bills | No | PIP or medical payments, if not rejected |
Your injuries when the other driver is at fault and uninsured | No | Uninsured motorist coverage, if not rejected |
Collision and comprehensive are optional in Texas unless you owe money on the car. TDI is direct about that: "If you still owe money on your car, your lender will require you to have collision and comprehensive coverage." We explain how the deductible on those coverages works in what is a deductible in car insurance.
Three crashes where the minimum runs out
TDI says it plainly: "Think about buying more liability coverage." It warns that the minimum limits might be too low if you cause a crash involving several vehicles or the other driver's car is totaled, and that "if you don't have enough liability coverage to pay for the damages and injuries you cause, you might have to pay the rest out of your own pocket. The other driver could sue you."
Here is what that looks like with round numbers. These are examples, not quotes or averages, but each one is an ordinary kind of crash.
The crash | The damage you caused | What 30/60/25 pays | What is left |
|---|---|---|---|
You total a newer pickup at a light | A truck worth $45,000 | $25,000 property limit | $20,000 |
Two people in the other car need surgery | $40,000 of bills for each person | $30,000 each, $60,000 total | $20,000 |
A three car chain on the freeway | $14,000 + $12,000 + $9,000 in repairs | $25,000 property limit, shared by all three | $10,000 |
Notice the third row. The $25,000 property limit is for the whole crash, so three damaged cars split one limit between them. That is exactly the situation TDI flags.
What is left does not disappear. The people you hurt can come to you for it, and that is when a liability limit stops being a line on a card and starts being a question about your savings, your home equity and your paycheck.
Get a free auto coverage check or call (281) 833-8585. Hablamos Español.
The other side: when the driver who hits you has the minimum
Run the same math in reverse. If someone carrying 30/60/25 causes a crash that puts you in the hospital, their policy pays you at most $30,000, however large your bills are.
That is the job of underinsured motorist coverage, the UIM half of UM/UIM. TDI says uninsured/underinsured motorist coverage "pays if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills." It is on every Texas policy unless someone rejected it in writing, and we walk through how to find out whether yours was rejected in uninsured motorist coverage in Texas.
Two details from TDI's uninsured motorist page help you set it:
"You can usually add more uninsured/underinsured coverage in $5,000 increments."
"A rule of thumb is to add at least enough property damage coverage to replace your vehicle."
The at fault driver carried | Your injuries | Their liability pays | Your UIM can cover |
|---|---|---|---|
30/60/25 | $55,000 in medical bills and lost wages | $30,000 | The rest, up to your UIM limit |
No insurance at all | $55,000 | Nothing | Up to your UM limit |
30/60/25, and you rejected UM/UIM | $55,000 | $30,000 | Nothing. You pursue the driver directly |
This is why your liability limits and your UM/UIM limits belong in the same conversation. One protects the people you might hurt. The other protects you from the people who might hurt you with too little insurance.
How much liability is enough for you?
There is no single right number, and anyone who gives you one without asking questions is guessing. These are the questions we actually ask.
Question | Why it matters |
|---|---|
What would you lose in a lawsuit? Home equity, savings, future wages | The more you have to protect, the more a gap above your limit puts at risk |
Who drives your cars? | A new driver in the house changes the odds, see adding a teen driver in Texas |
How much do you drive, and where? | Long freeway commutes mean more cars around you at higher speed |
Do you have, or want, an umbrella policy? | Most umbrella policies require higher auto limits underneath them |
Is your car paid off? | That changes collision and comprehensive, not how much liability you need |
Higher split limits, such as 50/100/50 or 100/300/100, are widely available. The only honest way to know what they cost you is to price them side by side, your current limits and a higher set on the same quote, from the same company, on the same day.
If you have real assets to protect, an umbrella policy sits on top of your auto and home liability. We cover what it does in what an umbrella insurance policy covers and what it tends to cost in how much umbrella insurance costs in Texas.
One honest exception. If your car is old and paid off, dropping collision can be a reasonable way to save, because collision protects your car. Lowering liability is a different decision, because liability protects everyone else, and their cars and hospital bills did not get any cheaper when yours got older.
How to check your limits in five minutes
Your limits are printed on your declarations page, the summary page of your policy. TDI's guide to reading your declarations page walks through where each item sits.
Find the liability line. It may read 30/60/25, or list bodily injury as 30,000/60,000 and property damage as 25,000.
Find the UM/UIM line. Check that it is there, and what limit it carries.
Look for PIP. It is included in Texas unless someone rejected it in writing.
Check collision and comprehensive. If you owe money on the car, your lender requires both.
Write down anything missing or at the minimum, and ask for a side by side quote with higher limits.
If you are about to change companies, our guide on how to switch car insurance easily in 2026 covers the order to do it in so you never have a gap. If you are buying a car, start with do you need insurance before registering a car in Texas, and if the car is financed, what gap insurance covers and whether you need it is worth a read too.
Frequently asked questions
Q: What is the minimum car insurance required in Texas?
Texas requires 30/60/25 liability: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage, per the Texas Department of Insurance and Transportation Code Section 601.072.
Q: Does minimum liability insurance cover my own car in Texas?
No. Liability pays for damage and injuries you cause to other people. Your own car is covered only by collision and comprehensive, which are optional unless a lender requires them.
Q: What happens if the damage I cause is more than my limits?
TDI says that if you don't have enough liability coverage to pay for the damages and injuries you cause, you might have to pay the rest out of your own pocket, and the other driver could sue you.
Q: Is the $25,000 property damage limit per car?
No. It is per accident. If you damage three cars in one crash, all three share the same $25,000.
Q: When did Texas last raise the minimum car insurance limits?
Transportation Code Section 601.072 sets the current 30/60/25 minimums effective January 1, 2011.
Q: What protects me if the driver who hits me has only the minimum?
Your own underinsured motorist coverage. TDI says UM/UIM pays if you're hit by someone who didn't have insurance or didn't have enough to pay your medical and car repair bills. It is on every Texas policy unless it was rejected in writing.
Q: How do I know what limits I have?
Look at your declarations page. The liability line shows your bodily injury and property damage limits, and the coverage list shows whether you carry UM/UIM, PIP, collision and comprehensive.
Related Articles
Why AZ Insurance Stands Apart
The minimum is easy to sell, because it is the cheapest line on any quote. We would rather show you what it leaves uncovered before you need it. AZ Insurance has served Texas drivers since 2003 from 15 offices across Houston and Dallas, and we compare 20+ insurance companies, so we can put your current limits and a higher set side by side and let you decide with real numbers in front of you.
Bring your declarations page from any company. Request a free auto coverage check or call our auto line at (281) 833-8585, and we will walk you through it in plain English or Spanish.
This article is general information, not legal advice or a promise of coverage. The examples use round numbers for illustration and are not quotes or averages. What your policy covers is governed by that policy. For questions about auto insurance in Texas, the TDI Help Line is 800-252-3439.
Latest Blogs

Texas SR-22 After a DWI: How to Reinstate Your License

Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing

How Much Does Umbrella Insurance Cost in Texas?

Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For

How to Read Your Texas Home Insurance Declarations Page, Line by Line

How to Lower Car Insurance: 10 Practical Ways to Pay Less
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How to Read Your Texas Home Insurance Declarations Page, Line by Line
Your declarations page decides what a claim pays. What every line means in Texas, why Coverage C means two things, and what to check at renewal.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Settling from dry clay soil is usually excluded. A plumbing leak under the slab can be covered, often only with a foundation endorsement. Here is how to check.