Quick support from trusted insurance professionals Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
How Much Does General Liability Insurance Cost in Houston in 2026?
How Much Does General Liability Insurance Cost in Houston in 2026?
How Much Does General Liability Insurance Cost in Houston in 2026?
How Much Does General Liability Insurance Cost in Houston in 2026?
How Much Does General Liability Insurance Cost in Houston in 2026?

Reviewed by A-Z Insurance Agency, licensed in Texas, serving Houston since 2003.
You run a small business in Houston, a client or a landlord just asked for proof of insurance, and the first thing you want to know is simple: what is this going to cost me? Since 2003, A-Z Insurance Agency has quoted general liability coverage for thousands of Houston businesses, from solo handymen to storefronts to food trucks, so here is the honest, Houston specific answer for 2026.
Quick Answer: Most Houston small businesses pay roughly $42 to $150 per month for general liability insurance in 2026, with a statewide average near $122 per month. Contractors pay more, often $200 to $420 per month for standard coverage, because their work carries higher risk. Your exact rate depends on your trade, revenue, payroll, and claims history.
Key Takeaways
Houston small businesses generally pay about $42 to $150 per month for general liability, and the Texas statewide average is roughly $122 per month, or about $1,462 a year, per MoneyGeek rate data.
Contractors sit at the higher end. A solo general contractor can start near $83 per month, while a small roofing or demolition crew can pass $665 per month.
Your trade is the single biggest price factor. Roofing and structural work cost more than office or finish work.
Houston and downtown Dallas businesses pay roughly 10 to 15 percent more than suburban ones because of density and litigation risk.
Bundling liability and property into a business owner policy can cut total cost by 15 to 25 percent.
The same business can get very different quotes from different carriers, which is why we compare eight on every quote.
In This Guide
What general liability insurance costs in Houston
General liability cost by business type
What actually drives your rate
How to lower your general liability cost
Why one business gets eight different prices
Frequently asked questions
What General Liability Insurance Costs in Houston
General liability insurance is the base layer of business protection. The Insurance Information Institute describes it as coverage for third party claims of bodily injury, property damage, and advertising injury that come out of your operations. In plain terms, if your work injures someone or damages their property, this is the policy that pays the claim and your legal defense instead of you.
For most Houston small businesses in 2026, that protection runs about $42 to $150 per month. MoneyGeek rate data puts the Texas statewide average near $122 per month, which works out to roughly $1,462 per year. Where you land inside that range comes down to what you do, how much you earn, and how many people you employ.
Coverage detail | Typical Houston figure (2026) |
|---|---|
Low end, low risk business | About $42 per month |
Texas statewide average | About $122 per month |
High end, higher risk | $150 per month and up |
Standard policy limits | $1 million per occurrence, $2 million aggregate |
Estimates only and not a guarantee of your actual rate. Figures reflect MoneyGeek 2026 Texas rate data and typical market ranges.
General Liability Cost by Business Type
Two businesses on the same street can pay very different premiums. A bookkeeper working from a laptop is low risk. A roofer on a ladder with a crew is not. Here is how the ranges break down by the kind of work you do.
Business type | Typical general liability cost |
|---|---|
Office or professional (bookkeeper, consultant) | $42 to $70 per month |
Retail shop or salon | $60 to $110 per month |
Cleaning or landscaping company | $70 to $130 per month |
Solo general contractor | About $83 per month to start |
Small contractor crew (1 to 4 employees) | $200 to $420 per month |
Roofing, demolition, or excavation | Up to $665 per month and higher |
Estimates only and not a guarantee of your actual rate. Contractor figures assume standard $1 million per occurrence and $2 million aggregate limits.
If you run a truck or a crew, general liability is usually only part of the picture. Many Houston businesses pair it with commercial auto insurance and workers compensation insurance so one incident does not take down the whole operation.
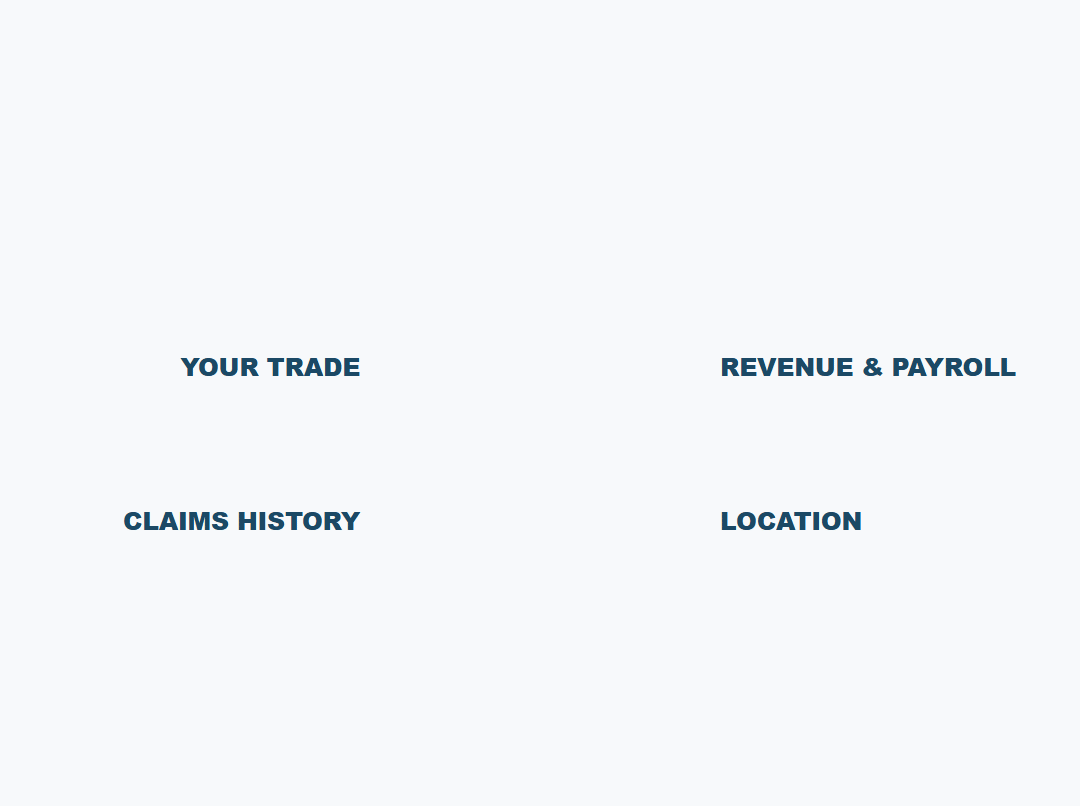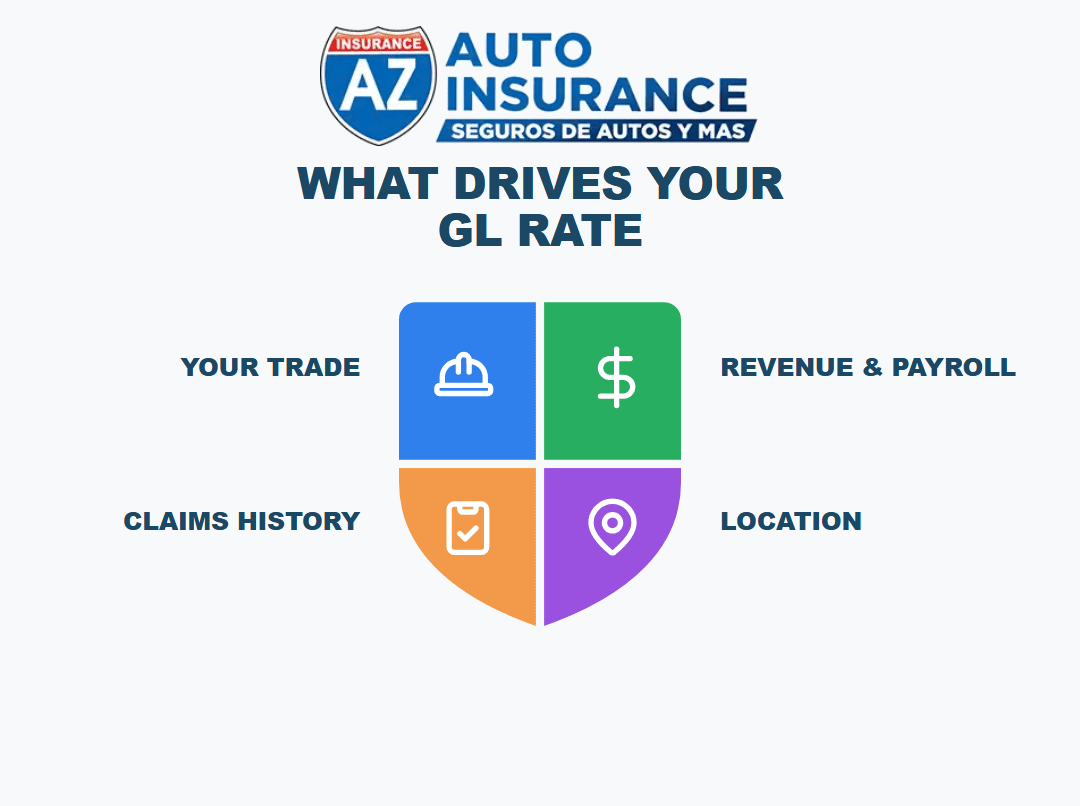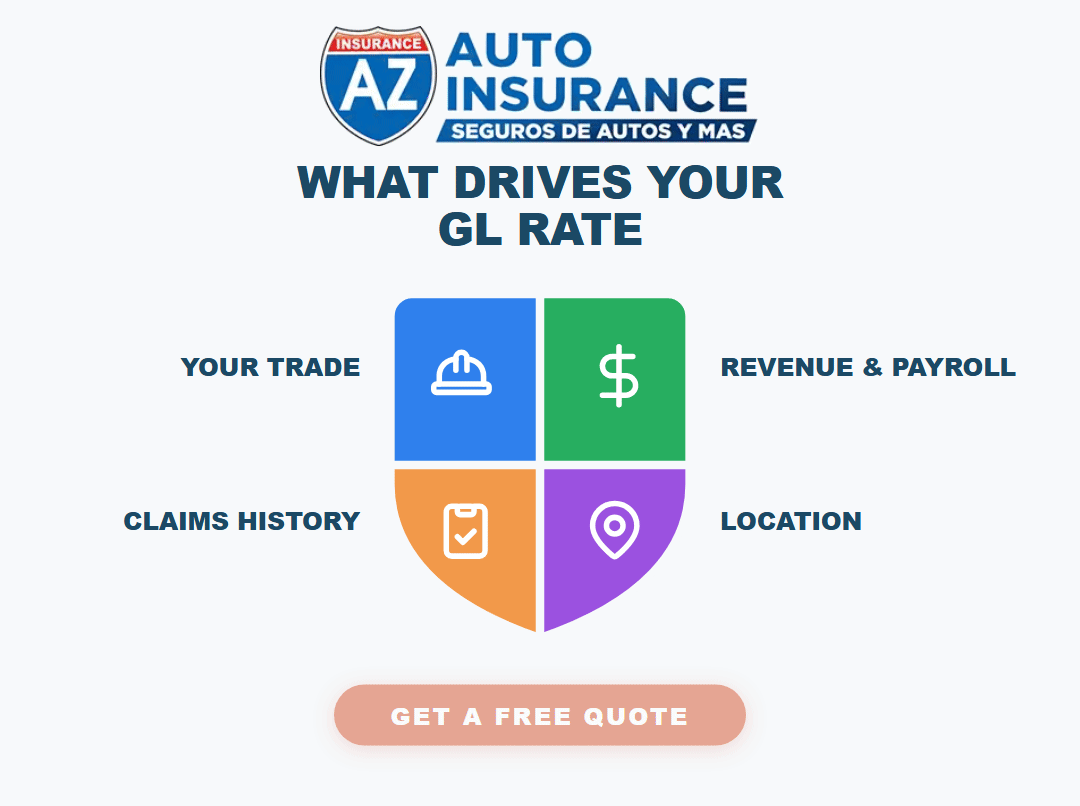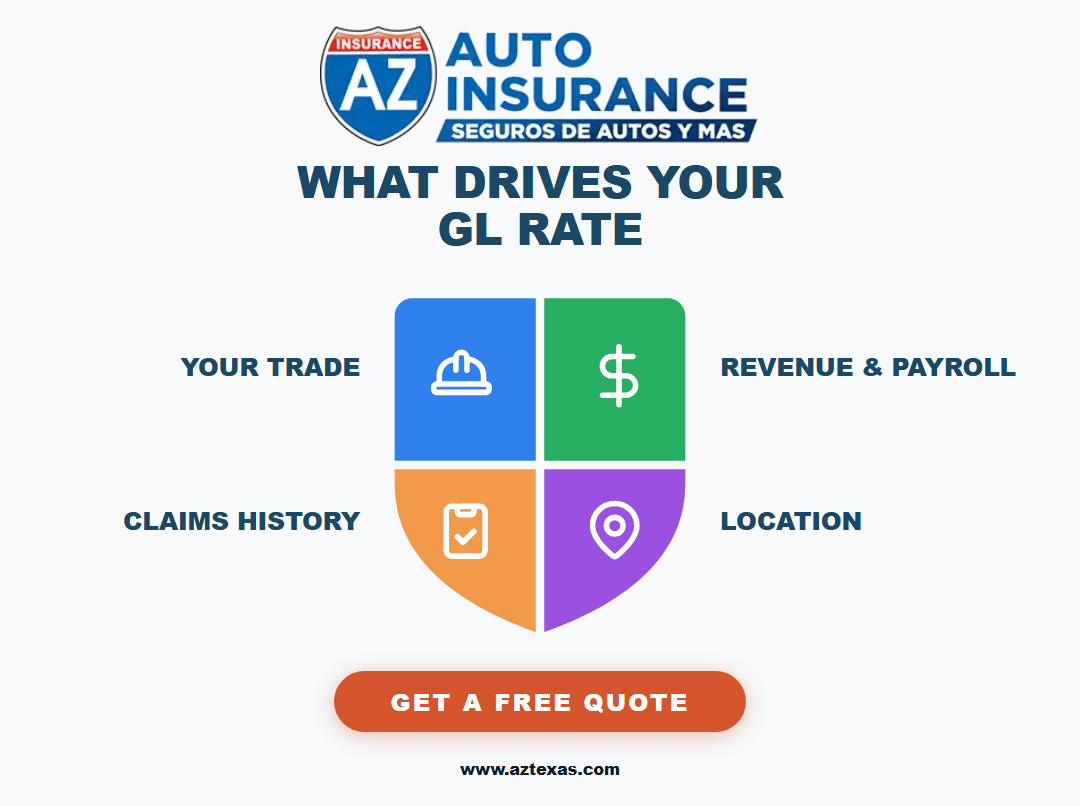
What Actually Drives Your Rate
Carriers price general liability on risk, and a handful of factors move your number more than anything else.
Your trade. The type of work matters most. Roofing and structural trades sit at the high end, while finish trades and desk based services land lower.
Revenue and payroll. More sales and a bigger crew mean more exposure, so premiums rise with both.
Claims history. A clean record earns lower rates. Past claims signal risk and push the price up.
Coverage limits. A $1 million per occurrence and $2 million aggregate policy is the market standard. Higher limits cost more, and many contracts require them.
Location. Density and litigation drive geography. Houston and downtown Dallas businesses pay roughly 10 to 15 percent more than suburban ones, and the Gulf Coast carries added catastrophe exposure.
The Texas Department of Insurance sets the standards commercial general liability policies follow, but it does not set your price. Carriers do, and each one weighs these factors differently. That difference is exactly why shopping matters, which we cover below.
How to Lower Your General Liability Cost
You have more control over your premium than most owners realize. A few practical moves:
Bundle into a business owner policy. Combining general liability with commercial property into a business owner policy can cut total cost by 15 to 25 percent versus buying each separately.
Keep your limits right, not just high. Match your limits to what your contracts actually require. Carrying far more than you need wastes money, carrying too little loses you the job.
Protect your claims history. Safety training, documented job procedures, and honest incident handling keep your record clean and your rate down.
Pay annually when you can. Many carriers discount annual payment over monthly installments.
Compare carriers every renewal. Loyalty rarely gets rewarded. Re shopping at renewal often finds a better rate for the same coverage.
Why One Business Gets Eight Different Prices
Here is the part most agencies do not tell you. General liability pricing varies dramatically between carriers because each insurer uses its own claims data and risk model to judge the same business. The spread between the highest and lowest quote for identical coverage on the same operation can be $30 to $50 per month, sometimes more.
Most agencies quote one carrier, maybe two. They have a preferred company, they earn a commission, and you get whatever that carrier decides. We quote eight and hand you the honest comparison, so you pay for coverage instead of someone else's convenience. If a general contractor or landlord needs proof before you start, we can also issue your certificate of insurance the same day.
For a full walk through of what the policy protects and where the gaps are, our guide on what general liability insurance covers for a business breaks it down line by line, and if you are still deciding whether you need a policy at all, start with the difference between personal and commercial insurance.
Frequently Asked Questions
Q: How much is general liability insurance per month in Houston?
Most Houston small businesses pay about $42 to $150 per month in 2026, with a Texas statewide average near $122 per month. Contractors typically pay more, often $200 to $420 per month for standard $1 million per occurrence and $2 million aggregate limits. Estimates only and not a guarantee of your actual rate.
Q: Why is my general liability quote higher than my neighbor's?
Because your trade, revenue, payroll, claims history, and coverage limits are different, and because carriers price the same business differently. A roofer pays more than an accountant on the same block, and two carriers can quote the same roofer $30 to $50 a month apart.
Q: Is general liability insurance required in Texas?
Texas has no blanket law requiring most businesses to carry general liability, but contracts, leases, general contractors, and some licensed trades make it effectively mandatory. Our guide on whether general liability is required in Texas covers exactly when you will be asked for it.
Q: Can I lower my general liability premium?
Yes. Bundle it with property into a business owner policy for 15 to 25 percent savings, match your limits to your real contract requirements, keep a clean claims record, pay annually, and compare carriers at every renewal.
Q: Does general liability cover my tools or my own faulty work?
No. General liability covers third party bodily injury and property damage you cause, plus your legal defense. It does not cover your own tools, your own vehicle, or your own faulty workmanship, which is why many businesses add commercial property and other coverage alongside it.
Q: How fast can I get covered and get a certificate of insurance?
Often the same day. A short call gets you quoted across eight carriers and, once you bind coverage, we can issue your certificate of insurance the same day so a waiting job does not stall.
Related Articles
Reviewed by A-Z Insurance Agency, licensed in Texas, serving Houston since 2003.
You run a small business in Houston, a client or a landlord just asked for proof of insurance, and the first thing you want to know is simple: what is this going to cost me? Since 2003, A-Z Insurance Agency has quoted general liability coverage for thousands of Houston businesses, from solo handymen to storefronts to food trucks, so here is the honest, Houston specific answer for 2026.
Quick Answer: Most Houston small businesses pay roughly $42 to $150 per month for general liability insurance in 2026, with a statewide average near $122 per month. Contractors pay more, often $200 to $420 per month for standard coverage, because their work carries higher risk. Your exact rate depends on your trade, revenue, payroll, and claims history.
Key Takeaways
Houston small businesses generally pay about $42 to $150 per month for general liability, and the Texas statewide average is roughly $122 per month, or about $1,462 a year, per MoneyGeek rate data.
Contractors sit at the higher end. A solo general contractor can start near $83 per month, while a small roofing or demolition crew can pass $665 per month.
Your trade is the single biggest price factor. Roofing and structural work cost more than office or finish work.
Houston and downtown Dallas businesses pay roughly 10 to 15 percent more than suburban ones because of density and litigation risk.
Bundling liability and property into a business owner policy can cut total cost by 15 to 25 percent.
The same business can get very different quotes from different carriers, which is why we compare eight on every quote.
In This Guide
What general liability insurance costs in Houston
General liability cost by business type
What actually drives your rate
How to lower your general liability cost
Why one business gets eight different prices
Frequently asked questions
What General Liability Insurance Costs in Houston
General liability insurance is the base layer of business protection. The Insurance Information Institute describes it as coverage for third party claims of bodily injury, property damage, and advertising injury that come out of your operations. In plain terms, if your work injures someone or damages their property, this is the policy that pays the claim and your legal defense instead of you.
For most Houston small businesses in 2026, that protection runs about $42 to $150 per month. MoneyGeek rate data puts the Texas statewide average near $122 per month, which works out to roughly $1,462 per year. Where you land inside that range comes down to what you do, how much you earn, and how many people you employ.
Coverage detail | Typical Houston figure (2026) |
|---|---|
Low end, low risk business | About $42 per month |
Texas statewide average | About $122 per month |
High end, higher risk | $150 per month and up |
Standard policy limits | $1 million per occurrence, $2 million aggregate |
Estimates only and not a guarantee of your actual rate. Figures reflect MoneyGeek 2026 Texas rate data and typical market ranges.
General Liability Cost by Business Type
Two businesses on the same street can pay very different premiums. A bookkeeper working from a laptop is low risk. A roofer on a ladder with a crew is not. Here is how the ranges break down by the kind of work you do.
Business type | Typical general liability cost |
|---|---|
Office or professional (bookkeeper, consultant) | $42 to $70 per month |
Retail shop or salon | $60 to $110 per month |
Cleaning or landscaping company | $70 to $130 per month |
Solo general contractor | About $83 per month to start |
Small contractor crew (1 to 4 employees) | $200 to $420 per month |
Roofing, demolition, or excavation | Up to $665 per month and higher |
Estimates only and not a guarantee of your actual rate. Contractor figures assume standard $1 million per occurrence and $2 million aggregate limits.
If you run a truck or a crew, general liability is usually only part of the picture. Many Houston businesses pair it with commercial auto insurance and workers compensation insurance so one incident does not take down the whole operation.
What Actually Drives Your Rate
Carriers price general liability on risk, and a handful of factors move your number more than anything else.
Your trade. The type of work matters most. Roofing and structural trades sit at the high end, while finish trades and desk based services land lower.
Revenue and payroll. More sales and a bigger crew mean more exposure, so premiums rise with both.
Claims history. A clean record earns lower rates. Past claims signal risk and push the price up.
Coverage limits. A $1 million per occurrence and $2 million aggregate policy is the market standard. Higher limits cost more, and many contracts require them.
Location. Density and litigation drive geography. Houston and downtown Dallas businesses pay roughly 10 to 15 percent more than suburban ones, and the Gulf Coast carries added catastrophe exposure.
The Texas Department of Insurance sets the standards commercial general liability policies follow, but it does not set your price. Carriers do, and each one weighs these factors differently. That difference is exactly why shopping matters, which we cover below.
How to Lower Your General Liability Cost
You have more control over your premium than most owners realize. A few practical moves:
Bundle into a business owner policy. Combining general liability with commercial property into a business owner policy can cut total cost by 15 to 25 percent versus buying each separately.
Keep your limits right, not just high. Match your limits to what your contracts actually require. Carrying far more than you need wastes money, carrying too little loses you the job.
Protect your claims history. Safety training, documented job procedures, and honest incident handling keep your record clean and your rate down.
Pay annually when you can. Many carriers discount annual payment over monthly installments.
Compare carriers every renewal. Loyalty rarely gets rewarded. Re shopping at renewal often finds a better rate for the same coverage.
Why One Business Gets Eight Different Prices
Here is the part most agencies do not tell you. General liability pricing varies dramatically between carriers because each insurer uses its own claims data and risk model to judge the same business. The spread between the highest and lowest quote for identical coverage on the same operation can be $30 to $50 per month, sometimes more.
Most agencies quote one carrier, maybe two. They have a preferred company, they earn a commission, and you get whatever that carrier decides. We quote eight and hand you the honest comparison, so you pay for coverage instead of someone else's convenience. If a general contractor or landlord needs proof before you start, we can also issue your certificate of insurance the same day.
For a full walk through of what the policy protects and where the gaps are, our guide on what general liability insurance covers for a business breaks it down line by line, and if you are still deciding whether you need a policy at all, start with the difference between personal and commercial insurance.
Frequently Asked Questions
Q: How much is general liability insurance per month in Houston?
Most Houston small businesses pay about $42 to $150 per month in 2026, with a Texas statewide average near $122 per month. Contractors typically pay more, often $200 to $420 per month for standard $1 million per occurrence and $2 million aggregate limits. Estimates only and not a guarantee of your actual rate.
Q: Why is my general liability quote higher than my neighbor's?
Because your trade, revenue, payroll, claims history, and coverage limits are different, and because carriers price the same business differently. A roofer pays more than an accountant on the same block, and two carriers can quote the same roofer $30 to $50 a month apart.
Q: Is general liability insurance required in Texas?
Texas has no blanket law requiring most businesses to carry general liability, but contracts, leases, general contractors, and some licensed trades make it effectively mandatory. Our guide on whether general liability is required in Texas covers exactly when you will be asked for it.
Q: Can I lower my general liability premium?
Yes. Bundle it with property into a business owner policy for 15 to 25 percent savings, match your limits to your real contract requirements, keep a clean claims record, pay annually, and compare carriers at every renewal.
Q: Does general liability cover my tools or my own faulty work?
No. General liability covers third party bodily injury and property damage you cause, plus your legal defense. It does not cover your own tools, your own vehicle, or your own faulty workmanship, which is why many businesses add commercial property and other coverage alongside it.
Q: How fast can I get covered and get a certificate of insurance?
Often the same day. A short call gets you quoted across eight carriers and, once you bind coverage, we can issue your certificate of insurance the same day so a waiting job does not stall.
Related Articles
Latest Blogs

Certificate Holder or Additional Insured? The Difference That Decides Who Pays Your Defense
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong

Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot

Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open

A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026

A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot
Buying a car in Houston today? You need insurance before you can drive it off the lot. Here is exactly what the dealership and lender require, and how to get proof the same day.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.